

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
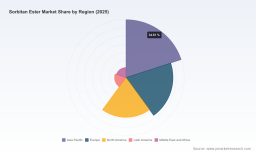
PW Consulting: Worldwide Sorbitan Ester Market to Reach USD 1.04B by 2032 on 4.8% CAGR; Asia‑Pacific Leads with USD 261.1M

Worldwide Sorbitan Ester Market: Strategic Insights for 2026 Decision‑Makers
PW Consulting’s new market brief on the Worldwide Sorbitan Ester Market is released as a decision-readiness tool for executives planning capital allocation, supply‑chain moves, and commercial strategy in 2026. The analysis synthesizes five years of historical performance, a seven‑year forecast horizon through 2032, and a set of executable playbooks that translate chemical market complexity into boardroom actions. This article summarizes the report’s strategic value: what senior teams need to know now, why it matters for 2026 planning cycles, and which tactical levers create optionality in an environment of modest growth and persistent input‑cost volatility.
Golf Course Mangement Solutions Market
Market snapshot: scale, trajectory and structural context
The global sorbitan ester market has moved from a mid‑single hundred million USD industry in the early 2020s to a broader specialty‑chemical market that crossed roughly three‑quarters of a billion USD in our 2025 base year. After a brief normalization in the immediate post‑base year period, our forecast indicates a steady expansion to exceed one billion USD by the end of the 2026–2032 forecast window, reflecting a compound annual growth rate (CAGR) of 4.8% over the period.
Concentrated Solar Power (CSP)-based Desalination Market
That growth profile is neither a rapid boom nor a stagnant commodity story; it is characteristic of specialty emulsifiers serving resilient end‑markets — food & beverage, cosmetics and personal care, and pharmaceuticals — where regulatory approval and formulation usefulness sustain long‑term demand. Market concentration is moderate: the top three manufacturers do not dominate the industry outright, and the top five account for roughly half of the market, leaving meaningful room for regional players, contract manufacturers and focused specialists to grow via technical differentiation or localization.
Worldwide Aseptic Bottle Closure Systems Market
What’s driving economics and where margins are vulnerable
- Upstream feedstock dynamics: Sorbitan esters are produced from sorbitol and fatty acids. Sorbitol price behavior remains a primary margin driver; recent data show a firm to slightly rising trend in global sorbitol prices into early 2026, with measured month‑on‑month increases in the US during spring 2026. Sorbitol production costs are highly sensitive to corn and wheat starch input costs (which represent the majority share of sorbitol’s cost base), amplifying feedstock pass‑through risks for producers.
- Fatty acid exposure: Fatty acids (palm, soy, tallow) add a second channel of volatility. Combined sorbitol + fatty‑acid exposure creates periodic margin pressure because long‑term supply contracts with downstream buyers often limit rapid price adjustment.
- Regulatory and quality premiums: Global approvals by regulatory authorities (e.g., food and personal‑care approvals) underpin broad adoption, but high‑purity grades and certified product variants (Kosher, Halal, pharma excipient‑grade) command a measurable price premium and counterbalance some margin pressure for producers willing to invest in compliance and quality systems.
Report contents — practical, transaction‑ready deliverables
Our full market study is designed as more than a market description; it is a toolkit for 2026 strategy execution. Key components include:
- A transparent market‑sizing model with historical reconciliation (2020–2025) and scenario‑based forecasts through 2032; the model is delivered in workbook form so teams can re‑run scenarios against customized input assumptions.
- Input‑cost sensitivity matrices that model margins under alternative sorbitol and fatty‑acid price paths, enabling rapid assessment of hedging or pass‑through clauses.
- Supply‑chain heatmaps and capacity mapping, distinguishing committed capacity, recent expansions and latent regional production capability (including recent North American capacity increases) to support rapid siting and sourcing decisions.
- Commercial playbooks for upstream producers and downstream formulators: go‑to‑market levers, value‑based pricing frameworks, and customer segmentation templates focused on technical service intensity rather than price alone.
- M&A and partnership frameworks: target archetypes, acquisition checklists, and integration pitfalls for buyers seeking to consolidate regional footprints or acquire formulation expertise.
- Regulatory and quality matrix for food, personal care and pharmaceutical channels, including compliance checklists that reduce time‑to‑market for new certified product variants.
Competitive landscape — how leading players are positioning
The sorbitan ester industry presents a mix of global specialty chemical houses, oleochemical specialists, and regional formulators. Our competitive mapping highlights three strategic clusters: global integrators that combine oleochemical sourcing with formulation R&D, regional cost‑advantaged producers, and niche suppliers targeting food or pharma certifications.
- Global specialty houses: Companies with broad surfactant portfolios bring scale and R&D leverage. Examples include BASF and Evonik, which position high‑purity grades and application‑specific formulations for bakery, confectionery and personal care; Croda leverages a well‑established brand and formulation support for personal care and pharma excipients.
- Oleochemical specialists: Firms such as KLK OLEO and Oleon leverage oleochemical feedstock integration to secure raw materials and offer consistent grades for food and personal‑care markets.
- Regional & niche players: A diverse set of manufacturers from Europe, China, India, and the Americas (including Stepan, Lonza, Lasenor, Sabo, and a range of smaller producers) provide local availability, food‑grade certifications, and competitive price points—factors important for CPG formulators and regional processors.
Recent industry moves illustrate these strategic patterns: Stepan announced a meaningful capacity expansion in North America in mid‑2025 to capture personal‑care demand; other manufacturers have introduced certified or enhanced‑performance grades targeted at food and confectionery applications. These actions show a market where incremental capacity and product innovation remain viable routes to share gains.
Strategic implications for 2026 planning cycles
For executives preparing budgets, capital plans and commercial targets in 2026, the report recommends five practical priorities:
- Lock in feedstock optionality: Implement dual‑sourcing strategies for sorbitol and diversify fatty‑acid procurement (palm vs. soybean vs. tallow exposures). Where possible, negotiate indexation clauses tied to transparent market benchmarks to mitigate short‑term margin shocks.
- Prioritize technical differentiation: Invest in certified grades (pharma‑ and food‑grade, Kosher/Halal) and application‑specific formulations for bakery/confectionery and personal care. These segments tolerate premium pricing and provide better margin resilience.
- Targeted capacity investments, not broad expansion: Given the moderate CAGR profile, greenfield builds should be selective. Faster routes to market include bolt‑on expansions at existing oleochemical sites or tolling agreements with regional specialists.
- Commercial sophistication: Move from commodity pricing to value‑based contracting with tiered service levels (technical support, supply guarantees, certification management) to sustain margins and deepen customer relationships.
- M&A as a strategic accelerant: Focus on acquiring formulation expertise, regulatory dossiers, or regional production to shorten market entry timelines and capture local demand advantages.
Decision‑making toolkit included with the report
To convert insight into action, the PW Consulting deliverables include:
- Interactive Excel model: baseline/alternative scenarios, margin sensitivity to sorbitol and fatty‑acid indices, and customizable revenue build‑ups by end‑use.
- Supplier scorecard and contracting checklist: a practical template to evaluate reliability, quality systems, certification status and pricing flexibility.
- Capex prioritization framework: NPV/IRR templates and payback thresholds adapted to specialty chemical investment horizons.
- Commercial negotiation playbook: clause language for indexation, minimum take‑or‑pay provisions, and technical service commitments.
- M&A target map and diligence roadmap: shortlists and red‑flag checks for feedstock exposure, customer concentration and regulatory compliance burden.
Why this matters for 2026
Decision windows in 2026 will be shaped by two tangible realities: first, the market’s steady expansion at a ~4.8% CAGR through 2032 means growth is available, but it is not a runaway market that justifies undisciplined capacity deployment. Second, upstream feedstock volatility and limited immediate pass‑through to contracted customers create recurring margin risk that must be actively managed through commercial design, procurement strategy and product differentiation.
For boards and executive teams, the right posture is to build modular optionality: secure raw‑material access, prioritize higher‑value product streams, and use M&A or partnerships to leapfrog capability gaps. Firms that pair technical service and certification credentials with smarter contracting will preserve margins and extend customer lock‑in even as commodity cycles fluctuate.
Next steps — where to find the full granular intelligence
This article sketches the strategic contours and highlights the practical levers contained in PW Consulting’s full Worldwide Sorbitan Ester Market report. The detailed segmentation, granular regional and application breakdowns, the complete capacity map and the interactive financial models are intentionally withheld here to preserve the report’s value as a subscription asset. Organizations that require the full dataset, downloadable models, and proprietary supplier scoring tools can access the complete report and supporting deliverables via PW Consulting’s report page.
PW Consulting stands ready to support tailored briefings, scenario workshops and acquisition diligence based on the dataset and playbooks in this study. For strategy teams preparing 2026 budgets and three‑to‑five‑year plans, the timing to align procurement, product and M&A activity is now—this report is designed to be the operative blueprint.
For detailed analysis of this topic, please visit the official page: Worldwide Sorbitan Ester Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com