

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: POE Market to Nearly Double from USD 4,200M in 2025 to USD 7,927.7M by 2032 at a 9.5% CAGR, Led by Asia Pacific

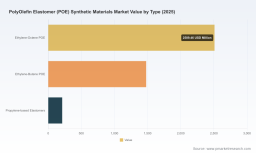
Polyolefin Elastomer (POE) Synthetic Materials Market: Strategic Imperatives for 2026
As companies enter 2026 under continued macroeconomic and energy-market uncertainty, PW Consulting’s latest PolyOlefin Elastomer (POE) Synthetic Materials Market report delivers the focused, executable intelligence procurement, product development, and corporate strategy teams need. Our analysis shows the POE market expanding from a 2025 base of approximately USD 4,200 million to roughly USD 7,928 million by 2032, implying a robust compound annual growth rate (CAGR) of 9.5% over the forecast horizon. This trajectory reflects structural demand from photovoltaics and automotive lightweighting, alongside supply-side shifts that will reshape sourcing and competitive advantage in the next three years.
Worldwide Pressureless Single Filers Market
Why this report matters for 2026 decision cycles
-
Timing: 2026 is a tipping point. Our forecast period (2026–2032) captures near-term capacity additions, regulatory implementation timelines, and technology adoption curves that will determine cost curves and supplier bargaining power.
Social Analytics App Market -
Actionable intelligence: We translate market-scale growth and volatility drivers into decision-ready tools—cost-pass-through models, hedging thresholds, and capex prioritization rules—that let leadership move from scenario awareness to execution.
Worldwide DC Combiners Market -
Competitive clarity: With a concentrated supplier base (our analysis highlights a top-three concentration characteristic indicative of high market influence, and a broader top-five concentration that further concentrates supply-side power), partnering and supply-security strategies will be decisive for margins and continuity.
Market trajectory and what it implies
The POE market’s projected near doubling from its 2025 base through 2032 is not uniform across applications, but the headline growth rate underscores three enduring themes that will guide profitable participation:
-
Structural demand growth in photovoltaics and electrified mobility-related applications, where POE’s combination of elasticity, impact resistance and processability is increasingly non-substitutable.
-
Rising premiumization: performance-differentiated grades (bio-attributed, low-seal-temperature, high-elasticity) are commanding price and specification premiums as OEMs and converters prioritize lifecycle and processing efficiencies.
-
Supply-side rebalancing: new capacity—particularly in Asia—combined with strategic integrations among incumbent producers will compress some import-dependent routes while sharpening competition on technical service and sustainability credentials.
Drivers, headwinds and tactical implications
-
Raw material volatility: POE feedstocks (ethylene, octene/butene co-monomers and propylene) remain sensitive to crude and refinery cycles. For instance, U.S. ethylene spikes tied to maintenance and regional demand have already pushed extrusion-grade cost buckets during 2025. Recommendation: adopt dynamic procurement triggers and index-linked contracts for sales that explicitly model a 6–9 month pass-through lag.
-
Localization and capacity additions: Chinese feedstock and POE capacity expansions accelerated during 2024–2025, reducing reliance on imports in several grades and applications. The practical effect for buyers is more nuanced: increased availability lowers spot premiums but shifts negotiation emphasis toward quality consistency, technical service, and shorter lead times. Recommendation: qualify regional second-source suppliers and retain capacity optionality for critical grades.
-
Regulatory tailwinds: tighter environmental standards in automotive (lightweighting, permeation control, recyclability mandates) increase OEM adoption of higher-performance POE grades. This creates premium niches that reward R&D and localized application engineering support.
-
Sustainability premium: the first commercially announced bio-attributed POE grades indicate a growing market for lower-carbon, certifications-compliant materials. Firms that can credibly offer mass-balance or bio-attributed supply will access new procurement frameworks and long-term contracts with large converters and OEMs.
Competitive landscape — capability maps and strategic postures
The POE supplier community combines global integrated majors, regional champions, and specialist producers. Key strategic patterns we identify:
-
Scale with application depth: Large chemical majors bring broad-grade portfolios and global logistics platforms, enabling rapid adoption in automotive and packaging chains. These players pair product breadth with service capabilities (application labs, technical compounding support).
-
Specialist differentiation: Producers that focus on metallocene-derived, performance-oriented grades or sustainability-linked feedstocks win in demanding niches—solar encapsulants, medical elastomers, and acoustic/insulation automotive components.
Representative players mapped against capability pillars (product breadth, technical service, regional capacity, sustainability credentials) include globally integrated producers and technology-focused suppliers. Their recent strategic moves are informative:
-
Horizontal integration and brand unification have been pursued to simplify customer management and cross-sell portfolio solutions.
-
JV consolidations and business integrations announced in late 2025 are designed to capture synergies across polyolefin value chains and accelerate scale in high-growth grades.
-
New product introductions that target bio-attributed feedstocks demonstrate a race to secure sustainability-differentiated positions ahead of procurement policy shifts.
Report scope — what PW Consulting delivers (and what we intentionally withhold here)
To preserve the strategic value of the full intelligence set, this release highlights the analytical framework and deliverables you will receive without reproducing primary segment tables and contract-level pricing data. The full report includes:
-
Market sizing and forecast by year (2020–2032), with scenario envelopes and sensitivity to ethylene/propylene price paths.
-
Granular supply-side coverage: capacity maps, commissioning schedules, and a validated capex pipeline by producer and plant class.
-
Competitive benchmarking and supplier scorecards assessing service, grade breadth, sustainability certifications, and capex flexibility.
-
Commercial playbooks: procurement triggers, indexation templates, and a negotiation framework for long-term offtake, tolling, and joint-development agreements.
-
Application-level demand models (photovoltaic encapsulants, automotive, wire & cable, specialty consumer and medical elastomers) and a recommended product roadmap for converters and OEMs.
-
Regulatory and sustainability impact matrices mapping compliance costs and market access thresholds by geography and product grade.
-
Deal flow and M&A screening toolkit identifying accretive targets and partnership archetypes aligned with demand growth pockets and margin expansion opportunities.
We intentionally exclude detailed segment tables and contract benchmark numbers from this summary: purchasing teams and strategy leads will find those datasets indispensable in the full report for supplier selection and capital allocation decisions.
Actionable recommendations for 2026
-
Procurement: implement dual-track sourcing—retain at least one geographically local qualified supplier while maintaining a global strategic supplier for premium grades. Employ index-linked pricing with floors and caps to stabilize margins.
-
Product strategy: accelerate qualification of sustainability-aligned grades where customer roadmaps already require ISCC or equivalent certifications. Prioritize grades that reduce processing energy or enable recyclability.
-
Supply security: model capacity exposure across a 12–36 month horizon, stress-testing for feedstock shocks and regional ramp delays. Consider strategic buffering for high-value grades rather than commodity inventory.
-
Commercial partnerships: target co-development and joint-qualification agreements with suppliers that can provide application engineering and localized R&D support—this materially shortens time-to-market for differentiated end-products.
-
M&A and JV criteria: prioritize targets that deliver immediate capacity, technical know-how in high-growth applications, or access to sustainability feedstock chains; quantify synergy capture timelines under conservative and aggressive scenarios.
Concluding perspective
POE is no longer a niche elastomer: it has become a strategic raw material class underpinning decarbonization, electrification, and the solar economy. The market’s projected near-term expansion and the concentrated supplier structure create both opportunity and fragility. Firms that pair disciplined procurement with targeted product investments—and that use supplier partnerships to de-risk supply while capturing application-driven premiums—will outperform.
PW Consulting’s full POE Synthetic Materials Market report provides the granular segmentation, contractual benchmarks, and supply-capacity maps that will convert these strategic imperatives into executable 2026 plans. For executives preparing budget cycles, supplier negotiations, or M&A screens, the right data ahead of contract renewals is the difference between margin preservation and margin erosion. Contact PW Consulting to access the full report and proprietary datasets that underpin these recommendations.
For detailed analysis of this topic, please visit the official page: PolyOlefin Elastomer (POE) Synthetic Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com