

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Worldwide Chassis-by-Wire Market to Grow at 19.5% CAGR, Reaching USD 29.3 Billion by 2032

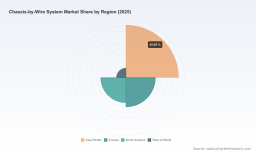
Worldwide Chassis-by-Wire System Market — Strategic Preview for 2026 Decision‑Makers
As the vehicle architecture shifts from mechanical architectures to software-defined systems, chassis-by-wire technologies (brake-by-wire, steer-by-wire, shift-by-wire and suspension-by-wire) have moved from niche proofs-of-concept to a foundational architecture for electrified, highly automated and connected vehicles. PW Consulting’s new Worldwide Chassis-by-Wire System Market study — based on a 2025 base year, a 2020–2025 historical window and a 2026–2032 forecast horizon — frames the commercial and technical inflection points that will define supplier strategies, OEM platform choices and investor decisions across 2026.
Worldwide Cloud Management Platform (CMP) Market
Macro picture: scale, speed and what it means for 2026
Our model shows the global chassis-by-wire market growing at a compound annual growth rate (CAGR) of 19.5% through 2026–2032. Measured in USD (revenue in millions), the market crosses the USD 10.1 billion threshold in 2026 under our base case and continues to compound materially toward the end of the forecast window. That pace of expansion alters traditional timeframes for ROI on new production lines, accelerates payback on software investments, and makes near‑term decisions (supplier selection, standards compliance, pilot deployments) strategically consequential for programs that begin production in 2027–2029.
3 Axis Horizontal CNC Milling Machine Market
Why this report matters for a 2026 strategy
- Decisions have shorter runway and higher stakes. The combination of high CAGR and rapid OEM platform commitments compresses evaluation and procurement cycles. Suppliers and OEMs that standardize architectures and establish validated safety cases in 2026 will capture preferential program positions for the next vehicle generation.
- Software and safety dominate capital allocation. The market is no longer just about actuators and sensors: software-defined motion control, validated fail‑operational architectures and cybersecurity stacks now represent a majority of program complexity and sunk cost. 2026 budget cycles must prioritize software lifecycle, over-the-air update strategies and functional safety investments at ASIL‑D level.
- Standards engagement is a competitive moat. With ISO 19725 entering publication activity and national rules (for example, recent Chinese steering system standards) updating the permissible architectures for steer-by-wire, active participation in standards and pre‑competitive groups materially reduces certification risk and time‑to‑market.
- Regional integration strategies matter. Standard harmonization (UNECE R79 allowances, China’s national standard updates, and ISO/SAE cybersecurity expectations) creates regionally differentiated compliance workstreams. A “global design, regional validation” approach is the pragmatic path for suppliers who aim for scale without proliferating SKUs.
What is in the PW Consulting report — practical, transaction‑ready content
PW Consulting designed this report to be operational for teams executing 2026 programs. Key deliverables include:
Worldwide Structural Engineered Glued Laminated Timber Market
- Market sizing and consensus forecast model (historical 2020–2025; forecast 2026–2032) with adjustable scenario levers (adoption timing, EV penetration, autonomy tranche) so procurement and strategy teams can run bespoke projections for their program timelines.
- Vendor benchmarking and capability scorecards across product, software, validation and production readiness — built from supplier interviews, public filings and in‑vehicle validation data.
- Standards & regulation readiness matrix mapping ISO 26262/ISO 19725 expectations, UNECE requirements and recent national standards to design and test deliverables needed for type approval and homologation.
- System‑level architectural playbooks (redundant controller options, dual‑power strategies, actuator redundancy patterns) with integration checklists to accelerate safety case generation.
- Supply chain risk register and unit cost/TCO modelling, including sensitivity to semiconductor availability and actuator sourcing, plus practical procurement mitigation measures.
- Go‑to‑market and M&A playbooks: target lists, valuation heuristics for strategic tuck‑ins (actuators, software stacks, functional safety houses), and JV models for China market entry.
- Operational templates — test protocols, cybersecurity hardening checklists, and sample ASIL‑D validation plans that can be adapted into supplier contracts and SRR/PRR milestones.
To preserve the commercial integrity of client deliverables and to comply with our “trailer” approach, the release intentionally omits granular region/application splits and line‑by‑line revenue tables from this public summary. The full dataset, vendor market shares and downloadable financial models are available in the PW Consulting report package and online portal.
Competitive landscape — who matters in 2026 and why
The supplier ecosystem is evolving into a landscape where systems integrators, traditional Tier‑1s and semiconductor specialists all play decisive roles. Our competitive analysis focuses on strategic positioning and near‑term moves that will influence awards in 2026:
- Continental AG — Positioned as an integrated systems supplier, Continental blends brake‑by‑wire and chassis control software with end‑to‑end vehicle integration capabilities aimed at software‑defined vehicle platforms. Expect continued emphasis on OEM partnerships and software monetization.
- ZF Friedrichshafen AG — ZF’s breadth (one‑box systems, hybrid portfolios for electrified platforms) gives it an advantage in multi‑domain program bids. The company’s 2025 portfolio unveilings show a strategy of offering modular stacks that reduce OEM integration effort.
- Robert Bosch GmbH — Bosch is strengthening full chassis integration with deep ADAS and automated driving alignment; their systems are attractive to OEMs that want a single supplier to assume broader validation responsibilities.
- Nexteer Automotive — The 2025 Electro‑Mechanical Brake product launch and subsequent ASIL‑D certification activity position Nexteer as a notable challenger in brake‑by‑wire and steer‑by‑wire for mass market EVs. Its active role in Chinese standards development is a strategic lever for access to local OEM programs.
- JTEKT Corporation — Focused on steer‑by‑wire scaling for EV and autonomous platforms; JTEKT is a contender where OEMs prioritize compact, high‑margin steering modules.
- Schaeffler AG — Building integrated actuation solutions with emphasis on density and packaging for electric platforms; attractive for OEMs looking to consolidate actuator sourcing.
- thyssenkrupp AG — Innovating on feedforward control and vehicle motion control integration, offering differentiated system behaviors for ride-and-handling tuning.
- Kongsberg Automotive — With fail‑operational systems and targeted acquisitions, Kongsberg is positioning for autonomous and commercial vehicle applications where robustness and certification are critical.
- Infineon Technologies AG — As a semiconductor enabler, Infineon’s high‑safety chipsets de‑risk motor control and safety islands — a strategic supplier for both established Tier‑1s and software-first entrants.
Market concentration metrics show a mid‑level consolidation dynamic — the top three suppliers capture a meaningful share of demand while the top five expand that reach further. That structure favors both incumbent scale and focused challengers that can exploit software or regional partnerships.
Regulatory and standards landscape — the guardrails for 2026 programs
- New standard activity (for example, the publishing process around ISO 19725) and national updates to steering system standards have shortened certification timelines: programs that align architectures to emerging guidance will avoid costly redesigns later in the development cycle.
- Functional safety and cybersecurity are non‑negotiable: ISO 26262 at ASIL‑D and ISO/SAE 21434 cybersecurity expectations drive architecture decisions (redundant controllers, dual power domains, fail‑operational strategies) and will be decisive in supplier selection rounds.
- UNECE R79 updates that allow steer‑by‑wire without mechanical backup under defined conditions open new packaging and space advantages for EV platforms — but they also increase the importance of validated self‑centering and fault management strategies.
Actionable 90‑day playbook for 2026
- Run a rapid architecture audit: map existing vehicle platforms to a standards readiness checklist and identify missing functional safety artefacts required for ASIL‑D certification.
- Initiate a supplier gate review: prioritize suppliers with validated redundancy architectures and semiconductor roadmaps, and require proof points on in‑vehicle failure mode testing.
- Lock a standards engagement plan: nominate technical leads to participate in ISO/industry working groups and track national standard timelines in priority markets.
- Budget for integrated software lifecycle: reallocate a portion of 2026 software spend towards OTA security, over‑the‑air validation and telemetry for in‑service fault analysis.
- Consider strategic investments or partnerships with actuator/semiconductor specialists to secure long‑lead components and preferential supply terms.
Closing perspective and next steps
Chassis‑by‑wire is transitioning from engineering novelty to strategic platform decision. The market’s high growth rate and regulatory momentum make 2026 a make‑or‑break year for supplier selection, standards engagement and architecture lock‑ins. PW Consulting’s Worldwide Chassis‑by‑Wire System Market study provides the forecasting backbone, vendor intelligence and implementation playbooks that procurement, engineering and corporate development teams will use to justify 2026 commitments.
We intentionally present this public summary as an executive “trailer” to our full deliverable: detailed regional and application splits, vendor market shares, financial models, and downloadable scenario workbooks are included in the complete PW Consulting report. For a walkthrough of the dataset, a tailored briefing for program timelines, or permissioned access to the model and vendor scorecards, contact PW Consulting to schedule a 2026 strategic briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Chassis-by-Wire System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com