

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
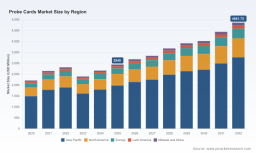
PW Consulting: Worldwide Probe Cards Market to Grow from USD 2,940.0 Million in 2025 to USD 4,861.8 Million by 2032 at a 7.45% CAGR — Asia Pacific Leads with USD 1,978.6M, Top 3 Hold 58.4%

Worldwide Probe Cards Market — Strategic Preview for 2026: Why Senior Leaders Need This Compass
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a market preview that frames the probe cards industry for boardroom decisions in 2026. Our new report uses 2025 as the analytical base year and projects the industry through 2032. At the macro level, the probe cards market is forecast to expand at a compound annual growth rate (CAGR) of 7.45% across the 2026–2032 forecast window, rising from a market size of approximately USD 2,940 Million in 2025 to an expected USD 4,862 Million by 2032. These headline numbers encapsulate persistent secular demand from advanced logic, memory, and heterogeneous packaging test requirements — but they only begin to tell the story that matters for strategic action.
Worldwide Solid End Mills Market
Why this matters for 2026 decision-making
Probe cards sit at the intersection of semiconductor test performance, test cost, and time-to-market. For chipmakers, foundries, OSATs, and test equipment suppliers, small changes in probe card capability or lead time can cascade into significant yield, throughput, and economic outcomes. The PW Consulting report translates the financial trajectory above into operational levers organizations can use immediately:
Computer XTX and ETX Module Market
- Risk-adjusted sourcing strategies to mitigate lead‑time volatility driven by materials and geopolitics.
- R&D and product roadmap choices that prioritize probe card architectures most likely to deliver near-term performance advantages at advanced nodes and high-pin-count wafers.
- Partnership and M&A playbooks focused on acquiring scarce MEMS know-how, vertical spring optimization, and localized production capacity.
In short, the market’s growth is meaningful and sustained, but it is neither uniform nor frictionless. Executives must translate forecasted expansion into tactical commitments that de‑risk supply and sharpen competitive differentiation.
RF Probe Holder Market
Key market dynamics shaping 2026 strategies
-
Technology mix and node transitions: The push to advanced nodes and chiplet/3D packaging increases demand for high‑precision probe solutions (MEMS, vertical architectures and specialized fine‑pitch designs). As a strategic priority, product and test engineers should prioritize multi‑architecture roadmaps that maintain compatibility across legacy and next‑gen wafer formats.
-
Concentration and supplier economics: The industry shows moderate-to-high concentration at the top end: the leading three firms capture more than half of the market, and the top five account for a clear majority. That structure benefits established providers with scale and IP, but it also creates openings for focused challengers with differentiated niche capabilities.
-
Supply chain and materials pressure: Geopolitical tensions, material shortages (including tungsten, copper and substrate materials), and policy-driven export controls have materially affected lead times — with industry observations of delays up to ~20% in recent years. Ceramic substrates (notably for 300mm applications) dominate relevant substrate demand and represented roughly an 84% share of the material segment in 2024, underscoring a single‑material dependence that buyers must manage.
-
Localized capacity expansion: Manufacturers are strategically investing in localized production and capacity expansions to shorten supply chains and capture regional demand. These investments change regional competitive dynamics and will affect lead times, qualification cycles, and incumbent relationships in 2026 and beyond.
Competitive positioning — what the major players are doing
Understanding competitor intent is crucial for offensive and defensive strategy. Our research synthesizes company disclosures, primary interviews, and industry filings to map where incumbents are investing — and why it matters to partners and buyers.
-
FormFactor Inc. (Livermore, CA): Continues to lead on scale and breadth, with recent M&A activity that adds MEMS patents and vertical spring enhancements. This reinforces FormFactor’s capability set around logic, foundry and high‑bandwidth memory testing and reduces time‑to‑market for vertically-integrated customers who require rapid qualification cycles.
-
Technoprobe S.p.A. (Italy): Expanding production footprint in Europe with a major new facility aimed at servicing regional fabs. The move signals a play to reduce lead times for European customers and to capture incremental demand driven by local wafer fabs and IDM reshoring initiatives.
-
Micronics Japan Co., Ltd. (MJC) & Japan Electronic Materials (JEM): Japanese suppliers continue to emphasize precision and qualification wins at the most advanced nodes. Recent co‑developed qualifications for leading foundries position these players as preferred partners for fine‑pitch, advanced node requirements.
-
MPI Corporation (Taiwan): Evolving from niche supplier to a strategic partner for AI/HPC testing through partnerships and targeted capacity expansion. Their investments in Taiwan aim to capture demand from local OSATs and IDM customers focused on AI chip validation.
-
Regional and specialized players (Nidec SV Probe, Feinmetall, Wentworth, STAr, and others): These firms reinforce differentiated value points — high‑voltage/current capability, specialized cantilever/knife‑edge contacts, and vertical architectures for specific application niches. They are the likely acquisition targets for global players seeking to fill capability gaps quickly.
Recent developments that recalibrate 2026 strategy
- Strategic acquisitions that expand MEMS IP and spring optimization capabilities.
- Facility expansions and capacity investments aimed at regional resilience (notably Europe and Taiwan).
- High‑profile supplier qualifications with leading foundries for 2nm and other advanced nodes.
- Partnerships between probe card manufacturers and OSATs to co‑develop chiplet‑ready and 3D/2.5D test solutions.
Each of these moves has practical implications for sourcing timelines, qualification workflows, and the negotiation dynamics between chipmakers and probe card vendors.
How buyers and suppliers should act in 2026 — prioritized recommendations
Our advisory synthesis translates market dynamics into pragmatic actions. Below are prioritized steps for procurement, product, and corporate strategy teams.
-
Procurement — pursue dual‑track sourcing and strategic buffer inventory: With material concentration and geopolitics elevating lead time risk, buyers should adopt dual‑sourcing for critical probe architectures and maintain strategic buffer inventories for long‑lead components (substrates, precision contacts). Scenario-based procurement contracts (including capacity reservations tied to roll‑rate commitments) can protect production ramps.
-
Product & test engineering — accelerate cross‑architecture compatibility: Invest in test methodologies and probe card specifications that support both MEMS and vertical/cantilever modalities where economically feasible. Prioritize investments that reduce qualification cycle time with foundries and OSAT partners.
-
M&A & partnerships — target capability fills over scale alone: Given the market’s concentration, targeted acquisitions (materials, MEMS IP, fine‑pitch capability) and co‑development alliances can be faster and lower risk than greenfield expansions for companies seeking capability parity.
-
Operations — localize where latency matters: For time‑sensitive test cycles (e.g., wafer acceptance tests for high‑value wafers), localized assembly and qualification can be a strategic differentiator. Investment in regional assembly lines and qualification labs should be economically modeled against the revenue exposure of the end devices being tested.
-
Risk management — stress‑test supplier networks: Build financial and operational stress tests into supplier evaluations, modeling scenarios that include material shortages, export restrictions, and rapid demand swings driven by AI/HPC design wins.
What the PW Consulting report delivers — practical content for immediate use
Our report is designed as an executable intelligence product for 2026 strategic planning. Key deliverables include:
- Macroeconomic and technology trend narratives that link semiconductor roadmaps to probe card demand.
- Forecasted market trajectory (2026–2032) with scenario variants and sensitivity analyses tied to node transitions and packaging shifts.
- Competitive mapping and capability gap analysis, including IP posture, manufacturing footprint, and recent M&A/partnership activity.
- Supplier selection framework and negotiation playbook tailored to probe card OEMs and chipmakers.
- Supply chain resilience playbook with stress‑test templates, inventory models, and regional manufacturing decision matrices.
- Practical TCO models and qualification roadmaps for migrating to new probe architectures while protecting yield.
- Executive slide set and board brief template optimized for procurement, operations, and R&D leaders to present recommended actions and investment cases.
This package is intentionally operational — designed to move from insight to execution within 30–90 days of adoption.
What we held back and why — the preview principle
To preserve the strategic value of the full report, this article intentionally omits granular segment tables and exhaustive regional/applicational splits that are central to supplier selection, competitive tendering, and investment valuation. The complete dataset — including decomposed regional, type, and application breakdowns, supplier financial overlays, and the full suite of scenario matrices — is available in the full PW Consulting Worldwide Probe Cards Market report. That repository also contains downloadable models you can run with your own inputs.
Final assessment — where to focus in 2026
Probe cards will remain a critical enabler of semiconductor throughput and yield as the industry scales advanced node and packaging complexity. The market’s projected growth to roughly USD 4.86 Billion by 2032 at a 7.45% CAGR is robust enough to justify prioritized investments, but the path to capture value requires deliberate moves: secure supply lines, accelerate cross‑architecture qualifications, and consider targeted M&A or partnerships to obtain specialized MEMS/IP and local capacity. Market concentration benefits incumbents, yet clear niches exist for agile suppliers that can deliver superior qualification speed, localized support, or niche technical capabilities for chiplet and 3D/2.5D applications.
For executives preparing capital allocation, procurement strategy, or R&D planning in 2026, the PW Consulting report is a decision‑ready tool. It links market numbers to operating levers and gives you the playbook to translate forecasted growth into defensible competitive advantage.
Access the full report
To obtain the complete Worldwide Probe Cards Market report — including the full dataset, supplier scorecards, scenario models and executable playbooks referenced above — visit our report page or contact PW Consulting’s industry practice. The detailed segment tables and downloadable financial models are published exclusively with the full report to preserve competitive value for subscribers and clients.
For detailed analysis of this topic, please visit the official page: Worldwide Probe Cards Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com