

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
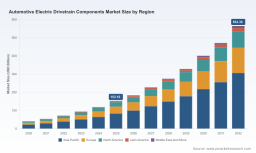
PW Consulting: Worldwide Automotive Electric Drivetrain Components Market to Soar from USD 153.16 Billion in 2025 to USD 564.36 Billion by 2032 at a 20.48% CAGR — Asia Pacific Leads with USD 83.07B, Electric Motors and BEVs Dominate

Worldwide Automotive Electric Drivetrain Components Market — Strategic Brief for 2026
PW Consulting’s new market study on the Worldwide Automotive Electric Drivetrain Components Market delivers the strategic intelligence senior leaders need as they set 2026 budgets, product roadmaps, and M&A agendas. The market that generated USD 153.16 Billion in 2025 has expanded rapidly from a 2020 base and — under current dynamics — is projected by our model to exceed USD 560 Billion by 2032, reflecting a compound annual growth rate of approximately 20.48% across the forecast window. Those headline metrics underscore a structural, capital-intensive shift in automotive powertrain economics: scale, platform modularity, raw-material exposure, and regulatory compliance will determine winners and losers over the coming 18–36 months.
Portable Blood Tube Sealer Market
Why this report matters for 2026 decision-makers
- Translate top-line growth into executable plans: Our analysis converts aggregate market momentum into tactical guidance for capex allocation, supply agreements, and product timing.
- De-risk technology choices: We map efficiency gains and cost trajectories across motors, inverters (including SiC adoption), and integrated e-axles so leadership can prioritize investments that preserve margin while meeting performance targets.
- Navigate supply-chain scarcity: The study overlays commodity concentration and semiconductor supply constraints onto supplier footprints to reveal where strategic stockpiles, alternative sourcing, or vertical integration are most urgent.
- Operationalize regulatory impact: With recent European legislative changes and particulate/ durability requirements maturing, the report identifies validation burdens and certification timelines that affect launch phasing and warranty exposure.
- Inform M&A and partnership strategies: Actionable heatmaps highlight acquisition targets, co-development matchups, and strategic investments that accelerate deployment of 400V/800V platforms and integrated drive systems.
Practical content you can use tomorrow
The report is built for boardrooms and strategy teams who must convert insight into action. It provides:
Disposable Balloon Uterine Lifter Market
- Robust methodology and traceable market-sizing — base year 2025 with full historical series (2020–2025) and a granular forecast for 2026–2032.
- Scenario-based outlooks that stress-test growth under alternative assumptions for commodity prices, regulatory tightness, and SiC supply bottlenecks.
- Technology deep dives on traction motors (including magnet vs magnet-free architectures), power electronics (Si vs SiC trajectories), integrated e-axles and multi-speed transmissions for electric platforms.
- Supplier profiles and capability matrices that rank OEM and Tier-1 positions on integration, vertical control, manufacturing scale, and software/controls ownership.
- Supply-chain risk maps and mitigation playbooks — from hedging rare-earth exposure through design choices, to procurement approaches for SiC and critical copper and lithium inputs.
- Commercial tools: price elasticity models, total cost of ownership worksheets for fleet customers, and negotiation frameworks for long-term component contracts.
- Interactive dashboards and downloadable data packages for internal modelling and committee briefings (note: detailed subsegment tables and proprietary supplier scores are included in the full package).
Key market dynamics shaping 2026 strategy
- Technology modularity and platform consolidation. Leading suppliers are investing in modular electric-drive architectures to shorten development cycles and serve multiple vehicle segments from a single platform. Modular solutions reduce per-unit cost at scale and increase cross-program reuse — a pivotal capability as OEMs compress time-to-market.
- Transition to high-voltage architectures and SiC adoption. The migration toward 400V/800V topologies and silicon carbide inverters is accelerating efficiency and charging performance, but it introduces new supplier dependencies and cost trade-offs that will influence product positioning and system margins.
- Supply concentration in raw materials and semiconductors. Critical inputs are unevenly distributed. Processing capacity for permanent-magnet rare-earth materials remains geographically concentrated, and SiC production is scaling but still faces cost and capacity challenges. Meanwhile, lithium price dynamics and base-metal volatility continue to reshape battery and drivetrain economics.
- Regulatory tightening and validation complexity. Recent regulatory packages in Europe (including accelerated CO2 targets and particulate/durability requirements) increase certification burdens for drivetrains and ancillary systems. Early adopters who integrate validation pathways into design cycles will realize time-to-market advantage and lower warranty risk.
- Consolidation and differentiated supplier strategies. Market concentration is measurable: a relatively small group of global suppliers collectively capture a notable share of industry revenue and influence platform choices. That concentration creates both negotiating leverage for large OEMs and expansion opportunities for integrated Tier-1s that can offer systems-level solutions.
Competitive landscape — what the leaders are doing
Our competitor analysis synthesizes capability, product roadmaps, and recent commercial moves for the industry’s most consequential players. Highlights include:
Intelligent Device Operation and Maintenance System Market
- European engineering houses are intensifying investment in integrated e-drive solutions and thermal management systems to capture platform-level value. These firms are placing strategic bets on modular architectures that span passenger and commercial vehicle segments.
- Japanese and Asian manufacturers continue to leverage deep motor and manufacturing know-how to drive efficiency and scale in traction motors and integrated e-axles, while selectively partnering with European suppliers on system integration and validation.
- North American players are differentiating through power-electronics expertise, high-voltage charging systems, and SiC-based solutions that target fast-charging and high-efficiency segments.
- Specialist newcomers and cross-border entrants are advancing compact, high-power e-axle systems and premium drivetrains for performance EVs, often via co-development deals with OEMs that have niche or luxury positioning.
Recent, illustrative corporate developments tracked in the study — from modular-drive unveilings to high-voltage drivetrain partnerships and mass-produced 7-in-1 e-axle introductions — concretize how capability investments are translating into competitive momentum and commercial footprints.
Supply-chain and raw-material imperatives
Material and semiconductor realities are among the most immediate constraints on growth. Processing of certain rare-earth elements used in traction magnets is heavily concentrated, creating sourcing vulnerability that directly impacts motor architecture choices. Meanwhile, lithium prices have experienced dramatic declines from 2023 peaks even as cobalt and nickel remain volatile and copper demand intensifies with electrification. Silicon carbide promises step changes in inverter efficiency but brings new supply and cost risks. The report offers concrete mitigation pathways — design alternatives (e.g., magnet-free motors), strategic procurement, and joint-investment models — that can materially reduce execution risk.
Regulatory realism — from CO2 targets to particulate limits
Regulatory developments, particularly in Europe, are elevating requirements beyond tailpipe CO2 to include battery durability and non-exhaust emission considerations (brake and tyre particulates). These changes increase validation scope for drivetrain systems and push cost into both R&D and testing budgets. Companies that align engineering roadmaps with regulatory trajectories early will secure faster access to regulated markets and minimize retrofit liabilities.
Three strategic pathways for 2026
- Scale and platform leadership. Prioritize modular 400V/800V architectures, invest in manufacturing scale for motors and inverters, and secure long-term supply agreements for key components to win volume-driven cost curves.
- Performance differentiation and technology ownership. Focus on high-efficiency architectures (SiC, integrated 7-in-1 solutions, multi-speed e-transmissions) and partner with premium OEMs to establish differentiated, higher-margin powertrain solutions.
- Risk-managed diversification and services. Build aftermarket, software-enabled optimization services, and diversified sourcing strategies (including localized production and strategic inventories) to buffer commodity and geopolitical shocks.
How boards and strategy teams should use the study
- Inform capital allocation deliberations: Use the report’s scenario outputs to size 2026–2028 capex ranges under divergent commodity and regulatory pathways.
- Drive supplier selection and contracting: Apply our supplier scores and risk maps to structure multi-year supply agreements, performance-based milestones, and joint-investment clauses.
- Prioritize product roadmaps and validation plans: Map feature launches against regulatory milestones and certification cycles to reduce time-to-market and warranty exposure.
- Screen M&A targets and partnerships: Use the M&A heatmap and capability overlay to accelerate inorganic growth where internal build is sub-scale or time-prohibitive.
PW Consulting’s Worldwide Automotive Electric Drivetrain Components Market report blends macro market sizing, detailed technology assessment, competitive benchmarking, and supply-chain risk analysis into a single, actionable package for 2026 decision-making. The executive brief above highlights our key strategic takeaways while preserving the proprietary segmentation, supplier scorecards, and granular financial forecasts that form the report’s commercial value. For organizations setting strategy in 2026, that granular intelligence — including downloadable datasets, interactive dashboards, and supplier negotiation templates — is decisive.
For access to the full report, interactive dashboards, and bespoke briefing options for your executive team, please visit the PW Consulting market reports page or contact our industry practice to schedule a private walkthrough.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Electric Drivetrain Components Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com