

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Vacuum Isolators Market Poised for Steady Expansion — 5.5% CAGR Forecast Through 2032

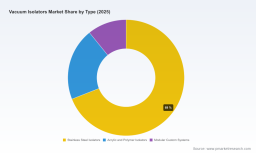
Vacuum Isolators Market — Strategic Insights for 2026 Decision‑Makers
PW Consulting’s latest market assessment on Vacuum Isolators translates technical complexity into board‑level clarity. Anchored to base year 2025 with a historical window from 2020–2025 and forward projections spanning 2026–2032, the study synthesizes hard market sizing, regulatory inflection points and supplier intelligence to guide capital allocations, sourcing strategy and product roadmaps. The sector is tracking a steady expansion (5.5% CAGR) — from approximately USD 420 million in 2020 to USD 550 million in 2025 — and is modeled to approach roughly USD 800 million by 2032. For executives making 2026 decisions, these headline dynamics establish the timing and scale of strategic options; the report converts them into executable playbooks.
Urban Intelligent Garbage Truck Dispatching System Market
Why this report matters in 2026
-
Regulatory inflection: Recent and imminent policy shifts tighten requirements for closed processing environments. EU GMP Annex 1 and the FDA’s updated QMSR both raise the bar on design, validation and lifecycle quality for isolators — accelerating replacement cycles and increasing the complexity of compliance documentation.
Mini Air Pump For Camping Market -
Capital intensity and economics: Pharmaceutical‑grade isolators remain a significant upfront investment with validation frequently adding a material percentage to ownership costs. That reality forces procurement teams to balance CapEx with long‑term Total Cost of Ownership (TCO) levers such as automation, retrofitting and service models.
Barium Titanate Modulators Market -
Market structure: The sector exhibits measurable concentration among top suppliers (CR3 and CR5 metrics indicate mid‑to‑high market aggregation). For buyers this means a limited set of strategic partners; for entrants it signals differentiated routes to scale such as niche specialization or aftermarket services.
-
Steady secular demand: Cross‑industry drivers — from biologics and sterile pharma to advanced electronics and energy storage R&D — maintain a base of stable, diversified demand that underpins predictable growth at the reported CAGR.
What the PW Consulting report delivers — operational, decision‑ready content
-
Robust market sizing and growth scenarios: granular scenario models that extend the headline 5.5% CAGR into alternative demand pathways, stress‑testing adoption rates for automation and retrofit programs.
-
Regulatory impact mapping: practical checklists and compliance timelines tied to Annex 1 and FDA QMSR changes, including the points where design choices materially affect validation scope, release timing and cost.
-
Technology and product landscape: comparative evaluation of stainless steel, polymeric and modular custom systems, with engineering trade‑offs, performance envelopes and retrofit compatibility matrices.
-
Supplier scorecards and procurement templates: side‑by‑side qualitative assessments of incumbent vendors, standardized RFx templates, contractual clauses to protect against lead‑time and obsolescence risk, and SLA frameworks for uptime and spare‑parts availability.
-
TCO and CapEx modelling tools: customizable calculators that fold in procurement price, validation adders, lifecycle maintenance, energy and labor impacts to quantify payback for automation investments like robotic gloveless designs.
-
M&A and partnership playbooks: screening criteria for strategic acquisitions, partnership models for small‑cap innovators, and exit/value creation levers for private equity and corporate development teams.
-
Field execution guides: validation timelines, FAT/SAT checklists, cleanroom integration workflows, and sample qualification documentation to compress time‑to‑commissioning and reduce rework risk.
Competitive landscape — how the vendor field shapes strategy
-
Zhejiang Tailin Bioengineering (China) — Strong in vacuum isolator and containment systems tailored to pharmaceutical dispensing and drying. Their value proposition favors integrated workflows for potent compound handling; buyers should evaluate fit for local regulatory acceptance and aftermarket reach.
-
Tema Sinergie (Italy) — A specialist in aseptic and containment isolators for pharma production and QC. Their European presence and compliance pedigree make them a natural partner for firms prioritizing Annex 1 alignment and legacy system replacements.
-
Comecer S.p.A. (Italy) — Known for gloveboxes and isolators engineered to integrate with vacuum ovens and tray dryers; attractive for API processing lines where integrated thermal processing is mission‑critical.
-
Schematic Engineering Industries (India) — Focused on Vacuum Tray Dryer (VTD) isolators in both rigid and flexible barrier formats. Their regional cost profile and system specialization can be compelling for cost‑sensitive retrofit programs.
-
Extract Technology Ltd. (UK) — Offers containment and aseptic isolators with compatibility for vacuum processes. Good candidate for customers emphasizing sterility testing and high containment performance.
-
Getinge AB (Sweden) and SKAN AG (Switzerland) — Global players offering high‑spec aseptic/containment platforms with advanced customization and service networks. Their scale supports multinational rollouts and long‑term service agreements.
-
Azbil Telstar (Spain) — Active innovator; recently launched dual‑mode isolators to enhance operational flexibility. Product developments like these are meaningful because they alter lifecycle economics and create new retrofit pathways.
Recent industry developments to watch
-
Product innovation: dual‑mode isolators and other modular designs increase utilization rates across different processes and reduce the need for duplicate capital outlay.
-
Automation shift: independent analyses and vendor studies have emphasized economic advantages of robotic gloveless isolators versus legacy glove systems; these advantages drive new procurement evaluations, especially in high‑volume sterile manufacturing.
-
Policy and compliance timing: firms that align procurement and validation timelines with regulatory milestones can realize first‑mover advantages and smoother licensing cycles.
Strategic playbook — recommended actions for 2026
-
Align CapEx with regulatory milestones: prioritize projects that are susceptible to Annex 1 or QMSR implications; defer non‑critical refreshes where safe to do so and reallocate budget to high‑impact compliance upgrades.
-
Budget validation early and explicitly: build the typical 20–30% validation adders into project finance models to avoid downstream cost overruns and schedule slippage.
-
Negotiate service‑centric agreements: because aftermarket service, spare parts and validation support materially affect TCO, structure contracts with performance‑based SLAs and predictable spare‑parts pricing.
-
Pursue modularity and retrofitability: where possible, choose platforms designed for phased upgrades and multi‑mode operation to preserve optionality as process needs evolve.
-
Evaluate supplier concentration risk: use CR3/CR5 market concentration insights to stress test single‑supplier dependency and create contingency sourcing lanes or dual‑sourcing strategies.
-
Consider automation ROI at the line level: deploy the report’s TCO tools to quantify when gloveless/robotic solutions outperform traditional isolators on labor, yield and contamination risk.
-
Scan for acquisition targets that add service capabilities or niche technologies: mid‑market consolidation and aftermarket monetization are credible value‑creation routes given current concentration patterns.
How to operationalize the findings at the executive level
-
Quarter 1 (90 days): run supplier scorecards against upcoming capital projects, lock in validation budgets and initiate compliance gap assessments tied to Annex 1/QMSR.
-
Quarter 2–4 (12 months): execute prioritized upgrades, pilot automation on a single critical line using the report’s TCO model and finalize long‑term service agreements that include performance incentives.
-
3‑year horizon: consolidate aftermarket service capability, pursue M&A or strategic partnerships to close capability gaps, and deploy multi‑site standardization to capture scale efficiencies as the market expands toward the projected 2032 level.
PW Consulting’s Vacuum Isolators Market report is deliberately constructed as an executive weapon: it pairs top‑line sizing (historical 2020–2025, base year 2025, and 2026–2032 forecasts), concentration metrics and scenario tools with transaction‑grade supplier intelligence and validation playbooks. The summary above highlights the strategic contours; the full report provides the proprietary segment tables, supplier scorecards, downloadable TCO calculators, and step‑by‑step validation templates you need to move from insight to implementation.
To access the complete dataset, segmentation tables and the operational annexes that power procurement negotiations and M&A diligence, please download the full report from PW Consulting. The executive summary will orient your leadership team; the appendices will let your project leads execute with confidence.
For detailed analysis of this topic, please visit the official page: Vacuum Isolators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com