

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Fluorozirconic Acid Market Poised for a Steady 4.6% CAGR in 2026–2032

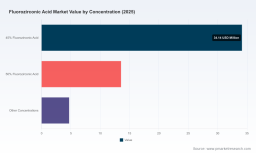
Worldwide Fluorozirconic Acid Market — Strategic Insights for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide Fluorozirconic Acid market delivers a focused intelligence package designed to inform procurement, manufacturing, and corporate strategy choices as firms enter 2026. The report synthesizes five years of historical performance (2020–2025) and a seven‑year forecast horizon (2026–2032), establishing a data-driven view of market scale, growth trajectory, supplier dynamics, and input-cost risk. At the aggregate level, the industry has demonstrated steady expansion in recent years, with the global market moving from just over USD 41 million in 2020 to approximately USD 52.4 million in 2025, and a forecast path that reaches the low‑70s (USD million) by 2032 under a baseline scenario. Our forecast period embeds an average annual growth trajectory consistent with a mid-single-digit CAGR, reflecting a balance of end‑market demand and input cost pressure.
Worldwide Rotary Version Precision Potentiometer Market
Why this report matters to 2026 planning
-
Clarity on scale and momentum: Executives need a reliable topline view to size investment, capacity and inventory commitments. Our topline time series provides that view up to 2032 and couples it with scenario stress tests for upstream shocks.
Black Lithium Tantalate Wafers Market -
Input-cost realism: The raw-material environment for fluorozirconic acid is unusually exposed to hydrofluoric acid and zirconium feedstock dynamics. The report quantifies the historic linkage between those inputs and finished‑goods pricing and offers procurement playbooks tuned to 2026 market realities.
Worldwide Cleats Shoes Market -
Competitive positioning checklist: With market concentration tilted toward a limited set of regional champions and a wide field of regional producers and distributors, corporate strategy must be calibrated between specialization, scale and secure sourcing. We translate these competitive realities into actionable options for industrial buyers and producers.
What the analysis reveals — high‑level takeaways
-
Measured growth, asymmetric risk: The market’s baseline trajectory points to consistent expansion over the forecast period, but near‑term upside and downside are driven largely by input-cost episodes and end‑industry demand shifts (metal finishing, specialty glass and other industrial uses). Firms should plan around a steady growth baseline while maintaining flexibility for episodic spikes or compressions.
-
Supplier structure favors a hybrid model: A small cohort of established producers and specialty distributors exerts substantial influence on trade flows and quality benchmarks. At the same time, a long tail of regional producers supplies bulk industrial demand. This hybrid structure creates both opportunities for selective consolidation and risks of localized supply tightness.
-
Raw‑material volatility is a decisive factor: Hydrofluoric acid price dynamics and zirconium feedstock availability are the primary near‑term cost drivers. In 2025 and early 2026, we observed meaningful upward pressure on hydrofluoric acid prices in several markets, while zirconium concentrate availability improved modestly, supporting feedstock availability but not removing price sensitivity.
Raw‑material and supply‑chain context
Two upstream themes dominated our analysis. First, hydrofluoric acid (HF) — the principal fluorine source for fluorozirconic acid synthesis — experienced notable price volatility in 2025, with domestic markets in key producer countries registering significant annual increases. Intra‑regional transaction prices in some markets remained materially higher than pre‑pandemic levels into early 2026, continuing to affect production cost models for fluorine‑based zirconium chemistries. Second, zirconium mineral concentrate production increased modestly in 2024, easing some feedstock availability concerns, but did not remove downstream exposure to price swings. Our scenario models demonstrate that short‑term HF shocks can compress producer margins and create sourcing arbitrage opportunities for buyers who have secured forward supply or alternative sourcing lanes.
Competitive landscape — what to watch
The market is populated by a set of established specialty producers and a broader group of regional manufacturers and distributors. Key profiles analyzed in the report include long‑standing European specialty producers with established quality credentials and certification records; multiple Chinese manufacturers supplying a broad range of industrial grades for metal treatment and optical applications; North American distributors with certification and quality systems; and regional suppliers in India and other Asia markets focusing on technical‑grade offerings and export markets.
-
European specialty producers: These firms typically emphasize product quality, regulatory compliance, and stable supply to high‑value industrial end uses.
-
Chinese manufacturers: Multiple enterprises offer a range of concentrations and packaging formats, serving both domestic industrial users and global trade channels.
-
Distributors and packagers: Companies operating in distribution and bulk packaging play a crucial role in bridging producer supply and industrial consumers, particularly for customers requiring certified supply chains or specific packaging formats.
For buyers and investors, the strategic implication is straightforward: differentiate supplier selection criteria depending on whether the priority is cost, certification, lead time, or application‑specific quality. The report includes supplier benchmarking matrices and a procurement scorecard to operationalize those choices.
Practical, actionable deliverables in the report
We designed this study as an operational tool — not an academic exercise. Among the deliverables are:
-
Topline forecast model with scenario branches for input‑cost shocks and demand contractions/expansions, exportable for client use.
-
Procurement playbooks that include hedging approaches, contract language templates for supply guarantees, and recommended inventory buffers tied to service‑level targets.
-
Supplier due‑diligence frameworks covering quality certification, environmental and safety compliance, packaging and logistics, and export controls.
-
An M&A and partnership diagnostic identifying target archetypes for vertical integration (e.g., securing HF or zirconium feed) and complementary product extensions into related zirconium chemistries.
-
Risk matrix and mitigation strategies covering regulatory tightening for fluorine chemicals, HF price volatility, transport and hazmat logistics, and geopolitical trade interruptions.
Strategic recommendations for 2026
-
Secure upstream access: Where feasible, negotiate multi‑year HF arrangements or participate in upstream partnerships to stabilize feedstock pricing. Short of vertical integration, consortia purchasing or advanced purchase agreements can materially reduce exposure to spot volatility.
-
Tier suppliers by role: Classify suppliers into strategic, preferred and transactional tiers, and allocate due‑diligence resources accordingly. Strategic suppliers should be subject to joint business planning; transactional suppliers should be managed via shorter, more flexible contracts.
-
Design flexible inventory strategies: Use a mix of safety stock, vendor‑managed inventory, and forward purchases aligned to the firm’s cash and working capital tolerance. The right combination will vary by your end‑use exposure and product quality sensitivity.
-
Differentiate by application focus: Companies serving high‑value industrial uses (e.g., optics, specialty ceramics) must prioritize quality, traceability and certifications; producers targeting commodity metal‑treatment volumes must prioritize cost and logistics efficiency.
-
Pursue bolt‑on or JV opportunities selectively: With a market structure that combines concentrated specialty suppliers and a broad base of regional producers, M&A or JVs focused on secure feedstock or market access can yield outsized strategic value.
-
Invest in compliance and safety: Regulatory scrutiny and transportation constraints for fluorine chemistry are heightened. Investing in environmental controls, hazardous materials handling and transparent chain‑of‑custody documentation reduces operational and reputational risk.
Risks and contingencies we modeled
-
Input‑cost shocks: Acute hydrofluoric acid price spikes materially compress margins in a matter of months. Our scenarios quantify margin sensitivity and suggest breakpoints for contract renegotiation or price pass‑through.
-
Regulatory tightening: Stricter transportation or production rules for fluorine compounds would disproportionately affect smaller producers lacking compliance infrastructure.
-
Trade disruptions: Tariff actions, export controls, or sudden logistic capacity constraints can create short‑term dislocations in specific markets; contingency sourcing and multi‑port routing reduce exposure.
-
Quality incidents: Given the toxicity and handling complexity of HF‑derived chemistries, even isolated incidents can trigger customer migration and stricter certification demands.
How PW Consulting’s work supports executable 2026 moves
The report is built to be used at the boardroom and plant level. Beyond the topline market series, we supply the executable artifacts procurement teams need: scorecards, contract templates, and supplier audit checklists. For strategy and corporate development teams, our M&A diagnostic and valuation levers translate market structure into deal rationale and integration priorities.
Importantly, the study also provides a playbook for operational leaders facing immediate 2026 decisions: when to convert spot exposure into forward coverage, how to prioritize capital projects in response to shifting demand signals, and what certifications or distribution partnerships unlock premium end‑markets.
Next steps — where to find the full intelligence
This article outlines the strategic value of PW Consulting’s Worldwide Fluorozirconic Acid market report and highlights the types of decisions the full study enables. For executives and practitioners preparing 2026 plans — whether optimizing procurement, sizing capacity investments, or evaluating M&A options — the full report contains the granular segmentation, supplier scores, and downloadable forecasting models necessary to operationalize the insights presented here.
To gain access to the complete dataset, the proprietary segmentation tables, and the supplier benchmarking models referenced throughout this summary, please visit the PW Consulting report page or contact our industry practice team for a briefing and tailored extract aligned to your use case.
For detailed analysis of this topic, please visit the official page: Worldwide Fluorozirconic Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com