

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Car Video Monitors Market to Surge from USD 1,010.5 Million in 2025 to USD 1,670.57 Million by 2032 at a 7.45% CAGR

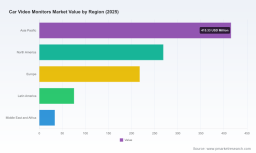
Worldwide Car Video Monitors Market — Strategic Outlook for 2026: PW Consulting Executive Brief
PW Consulting’s newest market study on Worldwide Car Video Monitors positions 2026 as a pivotal decision year for vehicle OEMs, Tier‑1 suppliers, panel makers and aftermarket specialists. Built on a 2025 base-year assessment and a detailed forecast covering 2026–2032, the market is modeled to grow at a compound annual growth rate (CAGR) of 7.45% through the forecast horizon. Our top-line sizing shows the global market crossing the billion‑dollar threshold in the base year and expanding toward mid‑range billions by the end of the forecast period — a trajectory that validates strategic investments but also raises structural questions about supply, regulation and competitive positioning that executives must resolve in 2026.
Industrial Monocular Microscopes Market
Why this report matters for 2026 strategic decisions
-
Timing of product roadmaps: As in‑vehicle experiences migrate from single-screen clusters to distributed, immersive video environments, 2026 is the year to decide which display technologies (OLED, microLED, foldable/rollable formats, or advanced LCD variants) will be core to a three‑to five‑year vehicle roadmap.
Portable Arteriosclerosis Detector Market -
Supply‑chain resilience: Heightened export controls and critical‑materials policy shifts make 2026 the inflection point for dual‑sourcing, long‑lead procurement, and reconsideration of vertical integration for key display and semiconductor components.
Worldwide Wasabi Sauce Market -
Channel strategy (OEM vs aftermarket): The market’s growth dynamics create distinct value pools for OEM-installed systems and aftermarket upgrades. Choices made in 2026 will determine revenue mix, margin profile, and service ecosystems for the coming vehicle generation.
-
Regulatory risk management: With new trade‑compliance constraints and mineral‑policy updates taking effect in recent years, 2026 will require hardened compliance playbooks that go beyond traditional customs checks to incorporate software provenance and hardware origin screening for connected vehicle components.
What’s inside the PW Consulting report (practical deliverables)
-
Executive demand model and scenario suite — top‑down and bottom‑up projections that translate vehicle production, equipment fitment rates and in‑use lifetime replacement into revenue and unit forecasts across the 2026–2032 horizon.
-
Product maturity and road‑mapping framework — technology adoption curves for OLED, microLED, foldable and interactive window concepts with feature‑level implications for cost, reliability and manufacturability.
-
Supplier scorecards and negotiation playbooks — comparative assessments of panel specialists, Tier‑1 integrators and aftermarket leaders including capability matrices, risk ratings and acquisition/win‑win partnership scenarios.
-
Channel and go‑to‑market playbooks — OEM and aftermarket segmentation strategies, pricing architectures, warranty/service models and software monetization options.
-
Supply‑chain risk heatmap — raw‑material dependencies, single‑sourced process steps, logistics choke points and mitigation tactics such as hedging, local content strategies and strategic inventory buffering.
-
Regulatory impact matrix — tailored to cross‑border compliance, secure‑software supply chain requirements and anticipated controls on critical minerals and electronics equipment.
-
3× M&A and partnership shortlist — tactical targets and deal rationales designed to accelerate access to critical technologies, panel capacity or regional market entry with modeled valuation scenarios under multiple growth assumptions.
Market dynamics distilled for action
-
Demand pull is structural not cyclical. Consumers and fleet operators are treating in‑vehicle video as part of the core mobility experience — driven by longer dwell times in automated or shared vehicles, rising expectations for entertainment and productivity in transit, and growing integration with vehicle infotainment and telematics platforms.
-
Technology is fragmenting; winners will be integration‑focused. While advanced display technologies (OLED, microLED, flexible formats, and mixed‑reality windows) are moving from demonstration to commercialization, the ability to integrate those panels with software, sensors and networked services will determine commercial success.
-
Price tiers create distinct economics. Entry‑level smart displays remain cost‑sensitive with typical component prices that keep replacement and aftermarket solutions accessible; premium integrated systems command higher ASPs and attract profitability for OEMs and Tier‑1 integrators. Our price benchmarking identifies practical thresholds for feature vs. cost tradeoffs that should guide 2026 product prioritization.
Competitive landscape — strategic implications
-
Display manufacturers (leading panel specialists): Major panel producers continue to invest heavily in automotive‑grade OLED and next‑generation microLED technologies. Their scale advantages and manufacturing roadmaps make them indispensable partners for anyone seeking premium in‑cabin experiences. Expect intensified competition on yield improvement, automotive certification and long‑term supply contracts.
-
Tier‑1 integrators and systems suppliers: Global Tier‑1s are expanding beyond mechanical systems into digital cockpits and RSE (rear seat entertainment) ecosystems. Their strength is systems integration — combining displays, control units and software — which creates high switching costs for OEMs and opens opportunities for co‑development partnerships.
-
Aftermarket specialists and infotainment incumbents: Longstanding audio and infotainment brands retain strong channel relationships and aftermarket distribution. They are best positioned to monetize retrofit demand and provide software update paths that extend product lifecycles.
-
Strategic moves to watch: Recent product demonstrations and showcases indicate a shift toward immersive, interactive rear‑seat solutions and form‑factor innovation (e.g., round displays, rooftop OLEDs, XR‑enabled windows). Partnerships between panel makers and cockpit software providers will be the primary route to commercialize these concepts at scale.
Regulation and raw‑material headwinds — what to prepare for
-
Trade and ICTS rules: New export controls and restrictions on certain hardware/software flows into connected vehicles in major markets introduce commercial friction. Procurement teams must incorporate compliance gates into supplier onboarding and establish forensic supply‑chain traceability for software and hardware components.
-
Rare‑earth and raw‑material policy shifts: Tightening export controls on critical materials and updates to critical‑minerals lists introduce upstream price volatility and potential capacity constraints for display and semiconductor inputs. Early engagement with raw‑material suppliers and investments in material substitution or recycling can materially lower procurement risk.
-
Cost pass‑through and pricing strategy: Given component pricing differentials across entry and premium tiers, firms must design adaptable price ladders and bundled service offers that protect margins while remaining competitive on vehicle spec sheets.
Practical 90/180/365‑day moves for 2026
-
0–90 days: Freeze product priorities and launch supplier due‑diligence on critical display and semiconductor suppliers. Establish compliance checkpoints for software provenance and origin documentation.
-
90–180 days: Execute pilot co‑development agreements with one display manufacturer and one Tier‑1 integrator. Finalize contingency plans for raw‑material sourcing and begin inventory tokening for long‑lead components.
-
180–365 days: Scale selected prototypes to limited production, formalize aftermarket upgrade programs, and implement a commercial contract structure that balances price, capacity assurances and IP sharing for joint innovations.
How PW Consulting’s analysis supports dealmaking and execution
-
We provide executable models that map product choices to margin outcomes, production capacity needs and channel economics so that commercial teams can quantify tradeoffs quickly.
-
Our supplier scorecards reduce selection uncertainty by combining technical capability assessments with regulatory and geopolitical risk scoring.
-
Our M&A shortlist and valuation scenarios are calibrated to the market’s growth profile and to plausible disruption vectors — giving strategy teams a defensible basis for bids or strategic alliances.
Concluding perspective
For 2026, car video monitors are not a niche adjunct to infotainment; they are a strategic lever. The market’s steady compound growth underscores an expanding addressable opportunity, but success will be determined by timely choices on technology partners, supply‑chain architecture, and compliance resilience. PW Consulting’s report equips decision makers with scenario‑tested roadmaps, supplier intelligence, pricing benchmarks and regulatory playbooks that turn market potential into operational advantage — without exposing confidential subsegment forecasts in this overview.
To access the full dataset, subsegment breakdowns, supplier scorecards and downloadable demand models that underpin these conclusions, visit our report page and request the comprehensive Worldwide Car Video Monitors Market study. The full deliverable is designed to be immediately actionable for 2026 planning cycles and board‑level investment decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Car Video Monitors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com