

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Industrial-Grade Ammonium Pentaborate Market to Reach USD 259.86 Million by 2032, Expanding at a 4.15% CAGR

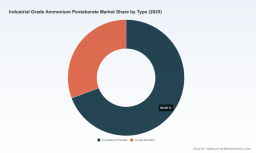
PW Consulting Strategic Brief: Worldwide Industrial Grade Ammonium Pentaborate Market — A 2026 Decision-Ready Preview
As PW Consulting’s Chief Industry Analyst, I present a focused, decision-oriented preview of our latest market study on industrial grade ammonium pentaborate. This briefing is designed to support C-suite and corporate strategy teams preparing 2026 investment, sourcing, and product roadmap decisions. It demonstrates the analytical depth of our full report while intentionally withholding the granular segment and regional datapoints that corporate decision-makers will need to unlock from the full study.
Worldwide Handwritten Notes Software Market
Market snapshot and trajectory
The ammonium pentaborate market has moved from roughly USD 160 million in 2020 to approximately USD 195.5 million in 2025, reflecting steady recovery and structural demand across industrial end uses. Our modelling projects continued expansion through the forecast window (2026–2032) at a compound annual growth rate (CAGR) of 4.15%, reaching an aggregate market size approaching USD 260 million by 2032. This trajectory underscores a market that is neither hypercyclical nor saturated — but one in which disciplined positioning, supply assurance, and regulatory foresight will separate winners from laggards.
Worldwide Punch & Die Storage Cabinet Market
Why 2026 is a strategic fulcrum
- Macro and midstream stability, with short-term inputs to monitor. Upstream feedstocks such as boric acid and borax remain determinative for cost and margin management. Our intelligence shows boric acid exhibiting a modest decline in Q1 2026 due to stable supply and measured downstream demand, while historical borax pricing experienced momentum shifts in late 2025. These dynamics create a near-term window for procurement optimization but also require ongoing monitoring for volatility.
- Regulatory tightening and risk reclassification. Key regulatory actions are already shaping commercial risk: ammonium pentaborate tetrahydrate is handled explicitly in REACH dossiers with reproductive toxicity concentration thresholds and PBT/vPvB considerations; in Canada the risk-management scope for boric acid and related salts was revised in March 2025, with stakeholder engagement continuing. These developments materially affect product stewardship costs, permissible uses in sensitive applications, and approval timelines for new formulations.
- Trade and tariff friction influence supply choices. Tariff regimes — for example, U.S. import duties that combine base HTS rates with additional country-specific levies — create differentiated landed-cost profiles by source. Companies importing solutions or finished formulations must factor tariff identity and country-of-origin into supplier selection, inventory strategies, and pricing models.
What the full PW Consulting report gives you (without revealing the core segmented intelligence here)
Our full study blends proprietary modelling with primary interviews and public data to provide operationally actionable intelligence. Highlights include:
Single-Flow Zinc-Nickel Battery Market
- Top-down and bottom-up market-sizing that reconciles production, trade, and end-use consumption to generate defensible forecasts through 2032.
- Scenario-based modelling (base, constrained supply, regulatory shock) that quantifies downside exposure and upside opportunity to 2032 for planning and capital allocation.
- Supplier mapping and a proprietary supplier scorecard that evaluates feedstock integration, quality certifications, ESG exposure, and scale economics.
- Pricing and margin models that translate boric acid and borax price trajectories into finished-product margin sensitivity across common commercial structures (bulk, tolling, contract manufacturing).
- Regulatory impact playbooks that detail compliance costs, likely market exclusions, and mitigation pathways—critical for procurement and new product introductions.
- Commercial go-to-market blueprints for differentiated offers (e.g., formulation services, pre-validated grades for electronics) and downstream channel plays.
Note: To preserve the integrity of competitive decision-making, we do not publish granular regional or application revenue splits in this preview. The full report includes those segment-level datasets, dashboards, and downloadable models.
Competitive landscape — positioning and strategic takeaways
The market shows a moderate concentration profile. The top three and five suppliers account for a meaningful, but not overwhelming, share of global supply — a structure that allows both incumbents and well-capitalized challengers to influence selective value chains.
- U.S. Borax (Rio Tinto) — With integrated borates operations and world-class mining upstream, this player leverages feedstock control to offer stable supply and scale economics. Strategic implication: competitors must evaluate long-term sourcing agreements or develop secondary supply options to avoid single-supplier exposure.
- Spectrum Chemical Manufacturing Corporation — Notable for manufacturing breadth and grade variety, including tetrahydrate options, Spectrum has pursued capacity expansion targeted at flame retardant and electronics demand. Strategic implication: niche premium positioning (quality grades, customized solutions) remains a high-value defense against commodity compression.
- Regional manufacturers and specialty suppliers (e.g., Larderello Group, DMCC Specialty Chemicals, Addenda Chemicals, Shravan Chemicals, Chemical Bull) — These suppliers gain traction via proximity to end markets, flexible batch capabilities, and customer intimacy. Strategic implication: multinational buyers should weigh total landed cost and technical service availability against pure unit price.
The competitive field is dynamic: established miners and large chemical players defend via upstream integration and long-term contracts, while nimble regional firms compete on service, customization, and price. Our report includes company-level strategy matrices and risk exposure heat maps to guide procurement, partnership, or M&A decisions.
Operational and strategic priorities for 2026
Based on our market modelling and client engagements, we recommend these prioritized actions for corporates planning 2026 initiatives:
- Revisit feedstock strategies immediately. Secure tiered purchase agreements for boric acid/borax with built-in flex for market swings and include explicit clauses for regulatory-driven supply disruptions.
- Embed regulatory forecasting into product development. Reassess any formulations that may breach updated REACH thresholds or fall under revised national risk management plans. Invest in data packages and testing upfront to shorten approval lead times.
- Optimize trade routes and tariff engineering. Where feasible, consider near-shore manufacturing, bonded warehousing, or alternative sourcing to mitigate country-specific duties that materially affect landed costs.
- Differentiate beyond price. Accelerate development of value-added services — technical onboarding, application validation for electronics and flame-retardant systems, and bespoke packaging — to protect margin against commoditization.
- Stress-test M&A and partnership plays. Use our scenario models to evaluate bolt-on acquisitions that close capability gaps (e.g., specialty grades, downstream formulation expertise) or secure feedstock linkages.
- Invest in supply-chain visibility and traceability. Enhanced traceability lowers recall risk, accelerates compliance responses, and is increasingly required by OEMs in sensitive sectors.
Decision-ready analytics: how PW Consulting helps you act in 2026
For corporate teams making capital allocation, sourcing, and product strategy decisions in 2026, the full PW Consulting report supplies:
- Integrated financial-impact calculators that map raw-material price swings and tariff scenarios to P&L outcomes.
- Segment and regional dashboards (interactive) that let you test “what-if” moves — e.g., changing product mix, redirecting volumes, or switching supply origins.
- Supplier scorecards with audit-ready due diligence outputs and recommended contracting language to accelerate negotiations.
- Regulatory playbooks and compliance timelines keyed to jurisdictions with active rulemaking.
These deliverables are purpose-built to convert market insight into executable project plans and procurement negotiations in 2026.
Closing perspective
The industrial grade ammonium pentaborate market presents an environment of stable overall growth (our base-to-forecast trajectory and a 4.15% CAGR through 2032), coupled with pockets of structural change driven by feedstock pricing, regulatory tightening, and trade policy. For companies that move early to secure diversified, compliant, and service-oriented supply strategies, 2026 offers a favorable window to lock in advantage. For those who wait, the twin pressures of regulatory compliance and tariff-driven cost shifts will raise barriers to rapid market response.
PW Consulting’s full report contains the segment-level revenues, regional splits, end-use share matrices, and company scorecards necessary to finalize procurement, investment, and M&A decisions. To access the complete dataset, forecasting models, and actionable playbooks referenced here, please visit our report page or contact your PW Consulting representative.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Grade Ammonium Pentaborate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com