

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Capsule Endoscope Attitude Controller Market Poised to Accelerate at a 10.45% CAGR, Forecast Indicates

Worldwide Capsule Endoscope Attitude Controller Market — Strategic Outlook for 2026 Decision-Makers
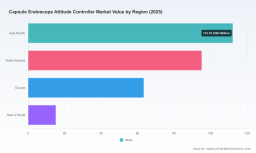
PW Consulting’s latest market research release — the Worldwide Capsule Endoscope Attitude Controller Market report — translates six years of historical performance into a forward-looking blueprint for executives, investors and clinical leaders preparing strategic decisions in 2026. The market for magnetically steered and attitude-controlled capsule endoscopy systems has exited the experimental phase and is consolidating into a competitive, clinically validated specialty with clear commercial inflection points. Our analysis quantifies that momentum: having reached approximately USD 285.8 million in 2025, the market is forecast to accelerate into a multi‑hundred‑million dollar market by the end of the 2026–2032 forecast window, rising at a compound annual growth rate (CAGR) of 10.45% and approaching an estimated USD 573.1 million by 2032.
Worldwide Wedge Bonders Market
Why this report matters for 2026 strategic choices
-
Timing and resource allocation: 2026 will be the year many organizations decide whether to scale commercial deployments, invest in next‑generation optical and magnetic subsystems, or pivot to adjacent therapeutics. The report aligns market timing with realistic clinical and reimbursement adoption curves so that capital, regulatory, and go‑to‑market plans are synchronized.
Capillary Columns Market -
Risk‑balanced opportunity identification: by combining macro forecasting with scenario testing, the study surfaces high‑probability commercialization vectors and the low‑probability, high‑impact events that could re‑rate company valuations within 12–24 months.
Worldwide Agricultural Pest Control Market -
Competitive nuance without overexposure: our competitive benchmarking highlights strategic strengths and weaknesses of incumbent and challenger firms while deliberately withholding proprietary sub‑segment leaks — directing decision‑makers to the full dataset for transaction‑level commitments.
Market dynamics that will shape boardroom decisions in 2026
-
Regulatory maturation is a differentiator, not a checkbox. Systems that have secured clearances for broader indications are already commanding premium access to tertiary centers. Recent de novo and indication expansions demonstrate a pathway: regulatory wins translate to measurable acceleration in commercial uptake, but payer recognition remains uneven. Executives must plan regulatory dossiers in tandem with payer evidence-generation.
-
Payer and reimbursement ambiguity remains the gating factor. While capsule endoscopy for small‑bowel indications sits on established reimbursement frameworks, magnetically controlled upper‑GI applications face varying degrees of investigational classification across payers. Our analysis identifies the most effective clinical endpoints and health‑economic evidence that have persuaded payers in pilot jurisdictions — tactical inputs for 2026 HEOR strategies.
-
Technology differentiation is clustering around control fidelity and image quality. Vendors who combine deterministic magnetic attitude control with optics that minimize distortion are being positioned as the standards for diagnostic confidence. In 2026, procurement committees will weigh the marginal diagnostic yield against total cost of ownership; vendors must make compelling, quantified claims about diagnostic delta, procedure throughput and training burden.
-
Commercial concentration materially affects partnership and M&A strategies. The market exhibits high top‑tier concentration, with leading groups commanding a dominant share. This structure creates both entry barriers and targeted acquisition windows: smaller platform innovators and subsystem suppliers become attractive bolt‑ons for clinical systems integrators seeking rapid capability expansion.
Competitive landscape — what to watch in 2026
The market is anchored by a small set of specialist companies that have converted clinical research into deployable platforms. PW Consulting’s report profiles the competitive spectrum from platform integrators to micro‑actuator innovators, dissecting go‑to‑market strategies, IP positioning, clinical evidence bases and channel footprints.
-
AnX Robotica Corp. (formerly Ankon Technologies) has rapidly positioned itself at the center of the commercial market through regulatory advances and product iterations. With recent expanded clearances and the U.S. commercial introduction of a small bowel‑optimized capsule featuring aspherical optics, AnX demonstrates a strategy of regulatory first‑mover advantage paired with incremental product improvements to lift diagnostic yield. For partners, AnX represents a strong anchor with demonstrated market access and a growing real‑world dataset.
-
IntroMedic Co., Ltd. brings a compact, hand‑held magnetic controller paradigm that emphasizes clinician ergonomics and point‑of‑care flexibility. Their approach appeals to outpatient centers and practice groups focused on procedure economics and space efficiency. In 2026, IntroMedic’s competitive play will center on usability claims and localized clinical adoption in markets with favorable device pathways.
-
JIFU Medical (Shenzhen Jifu Medical Technology) is executing a hybrid strategy that emphasizes hospital partnerships and regional deployment. Recent institutional agreements highlight the pathway from clinical validation to routine clinical service. JIFU’s roadmap suggests an emphasis on scale deployment within health systems that value integrated training and service models.
-
Chongqing Jinshan Science & Technology is notable for its integrated capsule families and an eye toward automation. Their fully automated navigation concepts aim to reduce operator variability and create standardized imaging workflows — attributes that could appeal to healthcare systems looking to lower training costs and improve throughput.
These vendors illustrate the variety of strategic plays — regulatory leadership, ergonomic differentiation, institutional partnerships, and automation — that buyers and investors must weigh when constructing roadmaps in 2026. Importantly, the market’s top tiers capture a sizable share of sales, producing a concentrated landscape that influences channel power and pricing dynamics.
What the PW Consulting report delivers (practical, actionable content)
-
Robust market sizing and forecasts with conservative, base, and upside scenarios that reconcile clinical adoption timelines and reimbursement shifts — enabling three‑way sensitivity analysis for capital planning.
-
Regulatory and payer matrices that map indications, approval status, and payer policy positions across priority territories — including an operational playbook for evidence generation tailored to the 2026 policy environment.
-
Technology benchmarking and clinical utility mapping that quantify the tradeoffs between magnetic control architectures, imaging optics, and autonomy levels — used to prioritize R&D investments and supplier selection.
-
Commercial due‑diligence templates and M&A scorecards that translate clinical, regulatory and market signals into valuation levers and integration risks.
-
Case studies and hospital deployment guides illustrating staffing models, training timelines and throughput improvements observed in early adopter centers — all designed to accelerate site adoption with minimal operational disruption.
Practical recommendations for corporate strategy in 2026
-
Align regulatory and HEOR plans: submit parallel regulatory and payer evidence strategies so that clearances are complemented by payer‑persuasive economic endpoints. This reduces time‑to‑net reimbursement and speeds commercial uptake.
-
Differentiate around total procedure economics: vendors should quantify downstream savings (reduced sedation, shorter recovery, improved diagnostic pathways) rather than rely solely on diagnostic sensitivity claims.
-
Pursue partnerships, not just sales: strategic alliances with imaging centers and health systems can create reproducible implementation playbooks that reduce adoption friction; these partnerships are often precursors to regional scale.
-
Prepare for consolidation by identifying bolt‑on technologies that fill clinical gaps (e.g., enhanced optical stacks, autonomous navigation modules) and by defining clear integration milestones and IP checkpoints.
-
Scenario‑proof contracts: structure buy‑side agreements to reflect regulatory and reimbursement milestones so that pricing, volume commitments and risk‑sharing are aligned to clinical evidence generation.
Key risks and market triggers to monitor in 2026
-
Major payer policy reversals or broad negative coverage decisions could slow conversion in non‑approved indications.
-
Breakthroughs in alternative diagnostic modalities or rapid cost reductions in competing technologies would compress adoption curves.
-
Supply chain constraints for magnets, optics or microelectronics could create temporary bottlenecks at critical deployment junctures.
-
Regulatory delays in priority markets would shift commercial timelines and reposition local incumbents.
Conclusion — using this report as a strategic lever
PW Consulting’s Worldwide Capsule Endoscope Attitude Controller Market report is deliberately designed as a decision‑ready intelligence product for 2026. It connects market sizing (the market reached roughly USD 285.8 million in 2025 and is forecast to grow at a 10.45% CAGR through 2032 to approach USD 573.1 million), competitive mapping, regulatory and reimbursement playbooks, and operational deployment guidance into a single actionable resource. The market’s concentration among a few leaders creates both opportunity and clarity: entrants and investors who align clinical evidence, regulatory timing and payer strategy will be best positioned to capture upside.
This release serves as a strategic trailer — showcasing the analytical depth and practical recommendations available in the full study while preserving transaction‑sensitive sub‑segment detail for subscribers and purchasers. For procurement teams, corporate strategy groups and investment committees preparing for decisions in 2026, the full report contains the datasets, model files and playbooks required to convert insight into action.
To secure the comprehensive dataset, scenario models, and executive brief designed for boardroom use, access the full report on the PW Consulting publications portal.
For detailed analysis of this topic, please visit the official page: Worldwide Capsule Endoscope Attitude Controller Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com