

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts 11.12% CAGR for Worldwide Custom LED Lighting Solutions Market in 2026–2032

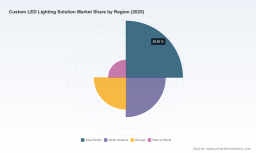
Worldwide Custom LED Lighting Solution Market: Strategic Imperatives for 2026
PW Consulting’s latest market study—anchored on a 2025 base year and projecting through 2032—finds the global custom LED lighting solution market at a pivotal inflection point. The market reached roughly USD 18.7 billion in 2025 and, driven by accelerating adoption of smart integration, energy-efficiency mandates, and bespoke architectural demand, is expected to expand at a compound annual growth rate (CAGR) of approximately 11.12% across the 2026–2032 forecast window, culminating in a near-term outcome that meaningfully reshapes supplier economics, procurement strategies, and innovation roadmaps for lighting-intensive industries.
Worldwide OLED Equipment Market
Why this report matters for executives in 2026
For corporate leaders, procurement chiefs, product strategy teams, and private equity investors, 2026 is not “business as usual.” Geopolitical pressures on critical minerals, surging upstream costs, and acceleration of smart and sustainable product requirements mean decisions made this year will lock-in cost structures and market access for the remainder of the decade. Our report delivers a decision-ready synthesis: validated market sizing, scenario-tested forecasts, and tactical playbooks that translate macro trends into transactional actions. To preserve competitive advantage, stakeholders need a crisp map of winners and risks—without being overwhelmed by data noise. This is the map.
Worldwide Desktop Search Software Market
What the analysis delivers (operationally focused)
- Robust market sizing and trend validation: historical series (2020–2025) reconciled against primary interviews and vendor shipment data, plus an independent forecast (2026–2032) reflecting multiple demand and supply scenarios.
- Actionable segmentation framework: region, product type, and application matrices with implied demand drivers and elasticities—presented as decision levers rather than raw tabulations.
- Competitive scorecards: strategic positioning, capability gaps, go-to-market models, and M&A targets for global and specialized suppliers.
- Procurement playbooks: supplier negotiation templates, hedging approaches for critical material exposure, and supplier qualification checklists that address both cost and resilience.
- Technology and sustainability roadmaps: lifecycle carbon implications, recycled-material adoption benchmarks, and retrofit vs. new-build economics.
- Risk registers and scenario toolkits: supply shock, regulatory dislocation, and premiumization scenarios, quantified to inform capex and inventory policy.
- Financial decision tools: ROI calculators, contract optimization models, and sensitivity analyses tailored for buyers, integrators, and OEMs.
Market structure and competitive dynamics
The custom LED lighting space remains commercially attractive yet structurally fragmented—the three- and five-firm concentration ratios are low, indicating ample room for niche specialists and new entrants to scale through differentiation and vertical integration. Fragmentation creates opportunities for focused players to capture value by owning intellectual capital, trusted installation services, or mission-critical certifications.
iSIM Module Market
Our competitive analysis profiles global leaders and high-performing specialists. Key strategic observations:
- Signify (Philips Lighting) continues to leverage brand scale and sustainability commitments to push recycled-material innovations and broaden its geographical reach in value-conscious growth markets. Recent product introductions that emphasize recycled content showcase how sustainability can be weaponized defensively to secure specification wins.
- OSRAM (ams OSRAM) maintains its edge on high-performance LED components and bespoke system integration for automotive and industrial customers—areas where thermal management and optical fidelity command premium pricing.
- Acuity Brands and Eaton (Cooper Lighting) are deploying integrated control stacks to lock in downstream recurring revenue from services and building-management tie-ins; these firms are models for revenue extension beyond one-time fixture sales.
- Cree Lighting’s recent strategic manufacturing agreement in the U.S. underscores an industry trend: near-shoring capacity to restore delivery performance and insulate customers from offshore disruptions—especially for heavy-duty and harsh-environment lighting segments.
- Mid-market specialists—Zumtobel, ProPhotonix, Acolyte (GENLED), AspectLED and several U.S.-based bespoke manufacturers—are exploiting design credibility or application-specific certifications to defend margin in architectural and mission-critical segments.
- Smaller OEMs and innovators (e.g., Addlux, American Illumination, Lumiron, HitLights, LANTANA LED) are winning with fast customization cycles, localized service, and targeted certifications. Notably, LANTANA LED’s 2026 certification for mission-critical data center lighting signals an example of certificate-driven market entry into high-value use cases.
Supply chain realities that will determine winners
Two systemic supply-side dynamics will drive 2026 decision-making:
- Critical mineral concentration: China’s dominant production of gallium and germanium—key inputs for LED optoelectronics—continues to create asymmetric supply risk. U.S. import reliance metrics remain elevated, and export-control dynamics have already introduced procurement friction for many buyers.
- Upstream cost pass-through: LED packaging and component vendors implemented price increases in recent periods, and certain manufacturers in China executed 2026 price adjustments in response to chip and substrate pressure. Procurement teams must anticipate periodic cost repricing and plan contract structures accordingly.
Compounding these pressures are regulatory moves that can re-write trade economics. A U.S. Presidential directive in early 2026 signaled active negotiations and potential tariffs on processed critical minerals—creating a plausible path to materially higher landed costs for some suppliers and an immediate rationale for re-evaluating sourcing strategies.
Strategic choices for 2026 (concise playbook)
- Prioritize supplier diversification and qualification: dual-source critical modules and maintain a second-sourcing pipeline for key optics and drivers to reduce single-point-of-failure exposure.
- Hybrid near-shore manufacturing: accelerate partnerships with local contract manufacturers for mission-critical and regulated applications while optimizing offshore production for commoditized fixtures.
- Embed sustainability into specs where it creates commercial advantage: recycled content and packaging changes can become specification gates in public-sector and enterprise procurement.
- Negotiate price-protection clauses tied to material indices and certification milestones to share upside and limit downside from raw-material volatility.
- Invest selectively in certification and controls IP: mission-critical certifications and systems-integration capabilities create durable pricing power and client stickiness.
Scenario insights: how to stress-test 2026 decisions
Our scenario-based modeling evaluates three actionable situations executives must pressure-test:
- “Supply Tightening” scenario—moderate export controls and a 5–15% upstream price shock: consequences include shorter lead times, higher inventory carrying, and re-prioritization of retrofit projects.
- “Regional Decoupling” scenario—trade barriers extend across several processing steps: strategic responses include accelerated near-shoring, re-certification investments, and supply chain transparency programs.
- “Smart Premiumization” scenario—rapid adoption of integrated controls and services: winners are those who monetize recurring software-as-a-service and managed lighting contracts.
How C-suite teams should use this intelligence in 2026
Boards, CEOs, and procurement chiefs should convert the report’s insights into three immediate actions:
- Run a 90-day supplier risk audit using our supplier scorecard to identify top exposures and engage contingency partners.
- Re-scope at least one major tender to include sustainability and lifecycle cost criteria—this yields procurement leverage and defensible premium capture.
- Commission a two-year capability roadmap to determine whether to build, buy, or partner for smart integration and certification competencies.
Closing and how to access the rest
This release is a strategic preview designed to surface the most consequential themes and to demonstrate the operational utility of our analysis—without disclosing the granular segment-level tables and paywalled proprietary models that underpin procurement playbooks and investment memos. PW Consulting’s full Worldwide Custom LED Lighting Solution Market report includes detailed regional and application breakdowns, company-level financial estimates, downloadable procurement templates, and scenario-adjustable financial models that senior teams can use directly in board and investment decision cycles.
For access to the complete intelligence suite, including vendor scorecards, certification matrices, and the downloadable ROI calculators that informed our 2026 recommendations, please visit the PW Consulting research portal or contact your client engagement lead.
For detailed analysis of this topic, please visit the official page: Worldwide Custom LED Lighting Solution Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com