

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts 12.42% CAGR for Worldwide Copper-Clad Laminate for 5G Market During 2026–2032

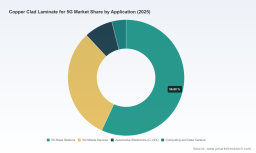
Worldwide Copper Clad Laminate for 5G Market: Strategic Preview for 2026 Decision-Makers
As 5G deployments accelerate from macro rollouts into dense, performance-driven architectures—mmWave small cells, cloud-RAN sites, and high-speed edge data centers—the supply chain for copper clad laminates (CCL) faces an inflection point. PW Consulting’s new market study (base year 2025) finds that the global CCL market for 5G applications grew rapidly during 2020–2025 and reached approximately USD 4,285.5 Million in 2025. Our model projects the market will expand to roughly USD 5,003.0 Million in 2026 and climb toward USD 9,725.4 Million by 2032, reflecting a compound annual growth rate (CAGR) of 12.42% across the 2026–2032 forecast horizon.
Electronically Controlled Food Dehydrator Market
Why this report matters for 2026 strategic planning
-
Timing: 2026 is the year when network densification moves from pilot to procurement phase in many geographic clusters. Procurement windows, BOM re-specifications, and supplier qualification cycles are compressing—creating short, high-stakes decision windows for OEMs, PCB fabricators, and material suppliers.
Gas Turbine Maintenance Service Market -
Margin pressure and pass-through: The CCL cost base is under renewed pressure from glass fiber, copper foil and resin supply dynamics. Buyers that fail to lock in strategic hedges or alternative material designs will face margin erosion or lengthened lead times where allocation is tight.
Ball Tow Hook System Market -
Technology differentiation: Material choices at the laminate level (low-loss, thermal stability, thin-core fabrics) are now primary gating factors for antenna and mmWave module performance. The suppliers who can combine low insertion loss with manufacturability at scale will shape platform roadmaps.
-
Consolidation opportunities: The market concentration metrics indicate meaningful aggregation in supplier share—three-firm and five-firm concentration levels show an industry where several global players exert significant influence. That dynamic raises strategic questions around supply security, dual-sourcing thresholds, and M&A timing.
Macro and supply-side forces to monitor
-
Raw material inflation and lead times: Our industry tracking through April 2026 shows persistent cost inflation for high-end thin fabric glass fiber and notable copper foil constraints. Several suppliers have announced sizable price adjustments to reflect input-cost trajectories; at least one major producer formalized a double-digit sheet and prepreg price uplift in early 2026. These moves are leading to extended lead times and allocation behavior among tier‑1 buyers.
-
Geopolitical and regulatory friction: Export controls on certain processing equipment and strategic materials enacted in 2025 have introduced new complexity into cross-border sourcing strategies. Firms with tight single-country sourcing for critical chemistries or equipment should assume longer qualification timelines and possible re-shoring or near-shoring costs.
-
Demand mix shift: The portfolio of CCL demand is diversifying beyond traditional base-station boards into higher-value categories—mmWave front-end modules, high-speed switch fabrics, and automotive C-V2X platforms. This rebalancing favors materials that deliver ultra-low loss and thermal endurance, but also requires suppliers to reconcile multi-technology manufacturing footprints.
Competitive landscape — positioning and strategic moves
The competitive set is a mix of incumbent global chemical conglomerates, specialized high-frequency material houses, and high-volume laminate producers. Key players are executing differentiated plays across product innovation, capacity expansion, and vertical integration:
-
Shengyi Technology Co., Ltd. (SYTECH) — leveraging deep process expertise in high-frequency laminates, SYTECH has publicly announced capacity expansion to serve accelerating 5G and data-center demand. Their strategy emphasizes scale for high-frequency cores and a fast ramp model to capture base-station and mmWave module demand.
-
Panasonic Holdings Corporation — a product-led strategy focused on ultra-low transmission-loss materials. In March 2025 Panasonic launched next‑generation MEGTRON variants targeted at server and network equipment operating above 112 Gbps. Their differentiator is integration of low-loss chemistries with multi-layer, halogen-free solutions for high-reliability platforms.
-
Doosan Corporation Electro‑Materials and other Asian heavyweights — pursuing verticalization and regional capacity to meet both domestic carrier rollouts and export demand. Their playbooks combine local manufacturing proximity with customized material blends.
-
Specialist western suppliers (Isola Group, Rogers Corporation) — focusing on high-performance low-loss laminates and global distribution networks. These firms are capitalizing on design-in relationships with high-performance RF module and antenna suppliers in Western markets, emphasizing product certification and supply traceability.
-
Taiwan-based laminate innovators (ITEQ, Ventec, TUC, Nan Ya, Kingboard) — concentrating on a broad portfolio that spans RF/mmWave to high-density interconnect solutions, with capability to support both prototyping and high-volume manufacturing.
-
Japanese specialty-chemicals (AGC, Mitsubishi Gas Chemical) — offering substrate chemistry depth (BT resins and other high-frequency laminates) and emphasizing high-reliability sectors where long-term material stability is mission‑critical.
Competitive implications: incumbency still matters, but speed-to-qualified-supply is emerging as the decisive competitive axis. Firms that combine product innovation with flexible regional capacity and robust input-cost hedging will seize disproportionate share as network upgrades shift into procurement cycles.
Operational playbook embedded in the report
PW Consulting’s report is designed as a practitioner’s toolset for 2026 planning cycles. Rather than a purely descriptive market narrative, the study delivers operational frameworks and executable artifacts that procurement, product and corporate development teams can apply immediately:
-
Supplier scorecards and qualification checklists calibrated for RF/mmWave and high-speed PCB requirements—enabling procurement teams to reduce qualification time by targeting the right material attributes and test protocols.
-
Supply-chain stress-tests and scenario models—three-tier scenarios (baseline, constrained raw materials, and accelerated densification) quantify inventory, working-capital and lead-time exposure under different market paths.
-
Technology roadmaps and material selection matrices—comparison frameworks that map performance trade-offs (loss tangent, dielectric constant stability, thermal cycling) to end-application R&D priorities.
-
Go-to-market playbooks for materials suppliers—commercial strategies for premiumization, channel segmentation, and hybrid capacity models to address both high-volume base stations and niche mmWave modules.
-
M&A and partnership screening—prioritized lists of capability gaps and strategic targets, with valuation sensitivity to raw material inflation and regional regulatory risk.
-
Regulatory impact analysis—practical remediation options for firms exposed to export controls and cross-border equipment restrictions, including localization thresholds and dual‑source roadmaps.
Practical recommendations for executives in 2026
-
Define critical‑material thresholds now: Establish a cross-functional definition of “critical” (by performance and supply risk) that triggers dual-sourcing, strategic inventory, or long-term contractual hedges.
-
Accelerate supplier qualification for high-frequency laminates: Shorten design-in cycles by pre-negotiating test plans and lot acceptance criteria with 2–3 prioritized suppliers that align to your product roadmap.
-
Price-risk and pass-through playbook: Update commercial contracts to include transparent pass-through mechanisms or material‑cost escalation clauses tied to agreed indices to avoid unilateral margin squeeze.
-
Scenario finance planning: Build three-year cash flow scenarios that include material price shocks and allocation-driven production constraints; quantify the OPEX/CAPEX trade-offs of onshoring or near-shoring select laminate production.
-
Pursue targeted partnerships: For OEMs dependent on performance laminates, consider engineering alliances with specialist material houses to co-develop next-generation laminates that reduce PCB complexity downstream.
What we intentionally withhold here—and why
This article is a strategic preview intended to guide executive prioritization in 2026. In adherence to our “trailer” principle, we have highlighted market-scale trends, competitive postures, and operational levers while intentionally omitting granular segmentation tables and detailed regional/application share data. Those detailed breakdowns—regional revenue splits, material-type penetration by application, and fine-grained supplier share tables—are contained in the full PW Consulting report and are essential for execution-level sourcing and product decisions.
Closing: the value proposition for 2026 decision cycles
For 2026, the question is no longer whether CCL demand linked to 5G will grow—the macro trajectory is clear and steep—but how procurement, product and strategy teams will manage the intersection of escalating input costs, supplier concentration, and technology-driven performance demands. PW Consulting’s study arms organizations with a detailed, operational toolkit to reduce supplier risk, compress design cycles, and capture margin in a rising-cost environment.
Executives who treat 2026 as a strategic inflection—locking down supplier architectures, validating material choices under stress scenarios, and pre-positioning for regulatory shifts—will avoid reactive choices that erode margin and product roadmaps. For teams preparing procurement plans, product roadmaps, or strategic M&A moves this year, the full report provides the data granularity and actionable templates required to move from insight to implementation.
Contact PW Consulting to access the comprehensive dataset, supplier scorecards, scenario models and the complete segmentation analytics that underpin these strategic recommendations.
For detailed analysis of this topic, please visit the official page: Worldwide Copper Clad Laminate for 5G Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com