

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide SAS‑RAID Controller Market to Reach USD 4,589.5 Million by 2032

Worldwide SAS-RAID Controller Market — Strategic Outlook for 2026: A PW Consulting Preview
As enterprises accelerate data-driven initiatives in 2026, storage architecture decisions are shifting from vendor preference to strategic imperatives. PW Consulting’s latest Worldwide SAS‑RAID Controller Market report (base year 2025) synthesizes five years of historical performance and a seven‑year forecast to deliver the decision-grade intelligence CIOs, storage architects, and procurement leads need to act with confidence. This preview highlights the report’s strategic value for 2026 planning while intentionally withholding deep segment-level tables and proprietary scorecards to encourage direct access to the full study.
Worldwide Event Planning Service Market
Executive summary: why this matters for 2026
The SAS‑RAID controller market has demonstrated steady expansion across 2020–2025, culminating in an estimated total market value of approximately USD 3.35 billion in 2025. PW Consulting projects the market will continue to grow through the 2026–2032 forecast window at a compound annual growth rate (CAGR) of 4.6%, reaching a materially larger market size by 2032. This trajectory reflects the intersecting forces of data center modernization, the persistent lifecycle refresh of enterprise storage, and the practical need to bridge legacy SAS/SATA investments with NVMe economics and performance.
Worldwide Vibratory Hammer Market
For 2026 specifically, our analysis identifies a narrow set of structural inflection points that will determine winners and laggards: migration patterns toward higher‑speed interfaces and tri‑mode controllers, supply‑chain dynamics for semiconductor components, and the concentrated competitive structure of the market that favors a handful of global suppliers. Organizations that align procurement cadence, technology roadmaps, and supplier risk mitigation to these realities will materially reduce total cost of ownership and operational disruption over the next 24–36 months.
Industrial Overload Relays Market
Market trajectory and macro drivers
-
Measured, durable growth: The market’s historical performance from 2020 through 2025 demonstrates steady incremental expansion rather than boom‑and‑bust volatility, setting a foundation for predictable planning. The projected 4.6% CAGR through 2032 signals continued adoption driven by upgrades and platform migrations rather than speculative demand.
-
Technology migration as the organizing principle: OEMs and enterprise buyers are directing investments toward higher‑speed interfaces and tri‑mode solutions that allow unified management of SAS, SATA, and NVMe devices. This is not merely a performance play — it is a lifecycle strategy that preserves prior storage investments while opening a clear upgrade path to NVMe.
-
Supply‑chain realism: Component lead times remain a practical risk. Our fieldwork and supplier interviews confirm MCU lead times averaged roughly 13–14 weeks in mid‑2025 — a level that forces procurement teams to bake inventory and lead‑time buffers into 2026 budgets and refresh cycles.
-
Consolidation and bargaining power: The market is highly concentrated; a small set of vendors controls the majority of addressable revenue. This concentration simplifies sourcing in some respects but elevates vendor dependency risk for organizations that lack alternative qualified supply lines.
Competitive landscape — short profiles and tactical implications
Our competitive analysis identifies a compact field of established vendors and specialist OEMs active in enterprise, industrial, and high‑performance markets. Rather than attempt a full ranking in this preview, we highlight each company’s strategic posture and what it means for buyers in 2026.
-
Broadcom Inc. — Positioned as a technology leader with MegaRAID and tri‑mode offerings, Broadcom has guided older 6Gb/s families to end‑of‑life, accelerating enterprise transitions to 12Gb/s, 24Gb/s and Tri‑Mode technology. For buyers, Broadcom’s roadmap signals stability but also a requirement to anticipate obsolescence-related refreshes.
-
Microchip Technology — With Adaptec SmartRAID product lines advancing to 24G and NVMe RAID accelerators, Microchip is framing a growth play in AI and data center acceleration segments. Recent firmware and product launches through 2025–2026 underscore an active investment cycle — an important factor for teams prioritizing continuous feature uplift and long‑term firmware support.
-
Marvell Technology — Focused on RAID‑on‑Chip (RoC) and enterprise SAS IO, Marvell’s solutions target mission‑critical environments where integrated silicon and power/performance efficiency matter. Marvell’s approach is attractive to hyperscalers and systems vendors seeking tight end‑to‑end platform integration.
-
Specialists and system integrators — Vendors such as Areca, Advantech, ATTO and HighPoint provide differentiated offerings for niche and industrial use cases: tri‑mode support in small form factors, embedded RAID for edge appliances, and flexible I/O stacks for specialized workloads. These players are crucial for buyers with non‑standard Form Factor or ruggedization requirements.
Recent vendor events — from Microchip’s firmware and product releases to Broadcom’s documentation updates in 2026 — reflect a competitive environment where software/firmware support and clear product lifecycles are as important as raw performance. PW Consulting’s report includes vendor scorecards and a timeline of product and firmware milestones to help buyers assess upgrade risk and supplier responsiveness.
Strategic imperatives and recommended actions for 2026
Based on our quantitative forecast and qualitative vendor assessment, PW Consulting recommends the following prioritized actions for enterprise and service provider decision‑makers planning in 2026:
-
Adopt a staged tri‑mode migration strategy. Evaluate tri‑mode controllers as the default choice for new deployments where mixed drive populations exist. They present the most cost‑effective path to accommodate legacy SAS/SATA investments while enabling NVMe adoption on a controlled timetable.
-
Shift procurement from spot buys to cadence‑driven contracts. Given multi‑month MCU lead times, negotiate cadence-based supply agreements and maintain a rolling buffer stock aligned to expected refresh cycles. This reduces project delays and mitigates forced upgrades at premium pricing.
-
Prioritize firmware governance and update discipline. Vendor firmware releases and documentation updates materially affect operational stability. Invest in staging and testing pipelines for controller firmware prior to broad rollouts — especially in heterogeneous estates.
-
Design for vendor concentration risk. With a small set of vendors dominating revenue, maintain validated secondary suppliers and cross‑train systems teams on alternative vendor toolchains to avoid single‑vendor lock‑in.
-
Model TCO with migration scenarios. Build financial models that compare extending existing SAS infrastructures against phased NVMe adoption using tri‑mode adapters. Include support, firmware validation, power/cooling, and potential downtime in the analysis.
-
Embed lifecycle triggers in modernization roadmaps. Use vendor EOL signals — such as Broadcom’s retirement of older 6Gb/s lines — to create clear lifecycle triggers that align refresh budgets, testing windows, and decommission plans.
What the full PW Consulting report includes
The full Worldwide SAS‑RAID Controller Market report delivers operationally actionable content tailored to technology and procurement leaders, including:
-
Detailed market sizing and seven‑year forecasts with scenario analysis and sensitivity tests.
-
Vendor benchmarking across product portfolio, roadmap clarity, firmware practices, and after‑sales support.
-
Use‑case economics and migration playbooks for data centers, enterprise servers, and regulated storage environments.
-
Supply‑chain risk maps with component lead‑time monitoring and mitigation playbooks, including alternate sourcing strategies.
-
Procurement templates, RFP language samples, and an operations readiness checklist to reduce deployment friction and firmware‑related incidents.
-
Appendices with methodology, primary research interview notes, and a curated timeline of vendor product and firmware events through mid‑2026.
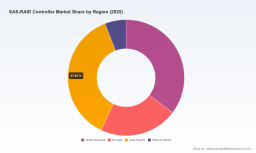
To preserve the strategic value of this intelligence, we have intentionally withheld detailed segment-specific tables and granular regional splits in this preview. The full report contains those datasets as downloadable exhibits, along with interactive charts that allow buyers to tailor the market view to their footprint and workload mix.
How to use this research in 90/180/365‑day planning cycles
-
90 days: Lock in supplier cadence agreements for critical controller SKUs, validate firmware testing pipelines, and initiate inventory buffers aligned to upcoming refresh windows.
-
180 days: Execute pilot deployments of tri‑mode controllers in mixed-drive clusters, compare operational metrics, and refine TCO models based on measured power/performance and management overhead.
-
365 days: Transition to a staged NVMe adoption plan for prioritized workloads informed by pilot outcomes, finalized vendor contracts, and the full market segmentation intelligence available in the report.
Conclusion — signal versus noise
In 2026, storage decisions will increasingly be governed by pragmatic trade‑offs: preserving prior investments, unlocking NVMe performance, and managing supplier and component risk. PW Consulting’s Worldwide SAS‑RAID Controller Market report delivers the market-level clarity and operational toolkits necessary to convert those trade‑offs into executable plans. This preview surfaces the strategic themes and recommended actions; the full report contains the granular segmentation, vendor scores, and downloadable financial models your teams will need to execute with confidence.
To access the complete market dataset, vendor scorecards, and procurement templates, please visit the PW Consulting report page or contact our industry practice. Our analysts stand ready to brief executive teams and customize the findings to your organization’s risk profile and modernization timeline.
For detailed analysis of this topic, please visit the official page: Worldwide SAS-RAID Controller Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com