

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Tubular Tongs Market Hits USD 1,654.37 Million in 2025, Poised to Grow at a 5.15% CAGR

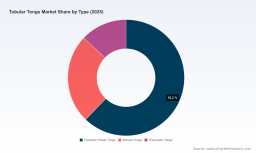
Worldwide Tubular Tongs Market: A Strategic Brief for 2026 Decision-Makers
Executive summary
PW Consulting’s new market study on the Worldwide Tubular Tongs Market — with base year 2025 and a forecast horizon running from 2026 through 2032 — delivers an evidence-backed roadmap for procurement leads, operations directors, product strategists, and private-equity investors planning moves in 2026. The global market, measured in USD Million, demonstrated steady recovery and expansion through 2020–2025 and is projected to grow at a compound annual growth rate (CAGR) of 5.15% over the forecast period. Our projections show the installed and addressable market expanding materially from the 2025 base into 2026 and beyond, reaching a clear strategic inflection point by the later years of the forecast.
Dual Chamber Bag (DCB) Market
Why this matters in 2026
-
Operational leverage: As drilling and completion activity rebalances across onshore and offshore programs, buyers face a decision set that extends beyond unit price — lifetime throughput, torque performance for premium connections, serviceability under API standards, and compatibility with mechanized or automated rig platforms are decisive.
Worldwide Oil & Gas Processing Seals Market -
Capex versus rental strategies: With mechanization and safety upgrades top of OPEX/CAPEX agendas, operators must choose between purchasing higher-specification hydraulic tongs or shifting to rental fleets that can deliver flexibility without long-term capital lock-up.
Dynamic High Pressure Pumps Market -
Supplier selection under concentration dynamics: Market concentration data indicate a mid-degree of incumbent strength among leading manufacturers (the top-three and top-five concentration levels are material but not prohibitive). This creates opportunities for differentiated entrants while requiring disciplined supplier risk management from large buyers.
Market trajectory at a glance
Historical analysis in the report traces the market from a post-2020 baseline through 2025, showing steady recovery in line with upstream investment flows. The 2025 base year is the analytical springboard for our forecast (2026–2032), which applies a 5.15% CAGR to model market outcomes under a central-case macro scenario. By quantifying both the market’s historic resilience and the likely paths under plausible oilfield activity scenarios, the study equips leaders to test procurement, service, and product development plans against realistic demand envelopes.
What’s inside the report — practical, transaction-ready intelligence
-
Decomposed demand drivers mapped to drilling, completion, workover, and tubing-service workflows — emphasizing torque demands, cycle rates, and duty profiles that determine equipment specing and maintenance schedules.
-
Supplier performance matrices that benchmark torque-to-weight ratios, modularity, interchangeability, and API compliance; these are linked to real-world operational needs for mechanized rigs and automated tubular-handling systems.
-
Procurement playbooks for 2026: decision frameworks for purchase vs. rental, lifecycle cost modelling templates, and inspection & maintenance KPIs you can deploy with vendors or service partners.
-
Capital allocation scenarios and ROI calculators tailored for different operational footprints (onshore-focused, deepwater, and well-servicing fleets) so finance teams can stress-test investment cases.
-
Regulatory and materials risk assessments — covering API specifications and the impact of alloy-steel inputs and steel market volatility on delivery schedules and unit economics.
-
Actionable M&A and partnership checklists for private-equity and corporate development teams that want to evaluate tuck-ins, technology partnerships, or aftermarket service platforms.
Competitive landscape — how incumbents and specialists shape choice
The market is populated by a mix of long-established manufacturers and specialist tooling houses. Our competitive analysis profiles the technical and go-to-market strengths of leading firms and what those strengths mean for buyers in 2026:
-
Eckel Manufacturing Co., Inc. (Odessa, TX) — recognized for an extensive model range and very high torque capacity variants suitable for premium connections; an attractive option where torque range and local serviceability are priorities. ( https://www.eckel.com/)
-
McCoy Global Inc. (Edmonton, AB) — notable for torque monitoring and digital-suite integration on selected models; strong when operators prioritize torque-control traceability and integration with smart-rig initiatives. ( https://www.mccoyglobal.com/)
-
Weatherford International (Houston, TX) — offers broad portfolio compatibility and tong-positioning system integration; strategically relevant for operators that prefer single-vendor systems across rig equipment. ( https://www.weatherford.com/)
-
Starr Power Tongs, LLC (Youngsville, LA) — a mid-sized supplier with focused product durability narratives and strong aftermarket partner networks, visible at recent industry shows. ( https://starrpowertongs.com/)
-
Magnum Manufacturing / Premiere, Inc. (Houston, TX) — specialist in high torque-to-weight designs and modular gear trains; valuable where truck-deployability and weight-sensitive operations matter. ( https://www.magnumcasingtools.com/)
-
Midland Oil Tools (MOT) (Midland, TX) — API-certified tooling with offerings tailored to drilling and well-service environments; of interest to compliance-focused operators. ( https://www.m-o-t.com/)
-
Forum Energy Technologies (Houston, TX) — competes on range and ruggedization for rig-floor equipment up to very large sizes; relevant to full-service drilling contractors. ( https://www.f-e-t.com/)
-
National Oilwell Varco (NOV) (Houston, TX) — integrates power tongs into broader rig technology suites; attractive when equipment interoperability is a buying criterion. ( https://www.nov.com/)
Recent market signals underscore active trade-show presence, expanded equipment listings across rental marketplaces, and continued catalog updates from regional suppliers — signals we interpret as vendors positioning for both replacement demand and a shift toward higher-spec mechanized rigs.
Supply chain, materials, and regulatory dynamics
-
Raw materials: High-strength alloy steel remains the dominant input for tong bodies and drive components. Price levels for structural and alloy grades have been above historical averages through 2025, and our supply-risk model anticipates moderate price pressure into 2026 linked to energy-infrastructure activity.
-
Standards and safety: API 7K (design/manufacture/testing of drilling and well-servicing equipment) and API 8A, along with ISO 9001 quality frameworks, continue to be the baseline for product qualification. Compliance is non-negotiable for operators and materially affects time-to-contract for new equipment buys or rental approvals.
-
Technology trend: Demand is coalescing around hydraulic systems that can be retrofitted to digital torque-tracking or integrated into smart-rig consoles. The mechanization trend increases the value of modular, serviceable designs that can be rapidly certified for various torque and connection types.
Strategic implications and five pragmatic moves for 2026
-
Prioritize modularity and serviceability in procurement specs. Insist on interchangeable gear trains and documented spare-part kits to lower downtime risk and simplify cross-fleet logistics.
-
Adopt a hybrid sourcing model. Combine strategic purchases for high-utilization assets with agile rental agreements for campaign-driven demand to optimize CAPEX and utilization simultaneously.
-
Mandate API and digital compatibility clauses in contracts. Require suppliers to demonstrate compliance and provide torque-data export capabilities to integrate with your rig analytics.
-
De-risk supply by qualifying secondary vendors. The concentration profile of the market means second-source relationships can materially reduce schedule and pricing exposure.
-
Embed lifecycle TCO in capital approval gates. Use the report’s TCO templates to compare up-front price, expected uptime, service frequency, and residual values in procurement decisions.
How to use the PW Consulting report in 2026 planning cycles
Think of the report as both a diagnostic and a transaction tool. Use the diagnostic sections to align internal stakeholders on realistic demand scenarios and the supplier shortlists to accelerate RFQ/RFP timelines. The procurement playbooks and ROI calculators are designed for immediate use in 2026 capital and operational planning meetings. For M&A and strategic sourcing teams, the competitive profiles and concentration analytics spotlight where bolt-on targets or JV partners could unlock differentiated service models or geographic reach.
Final note — what we deliberately hold back here
This release intentionally showcases the analytical depth and decision-ready outputs of PW Consulting’s study while withholding certain granular segmentation tables and discrete regional and application-level dollar splits that are provided exclusively in the full report. That segmentation is the precise intelligence many teams need to finalize procurement volumes, rental fleet sizing, or localized service strategies — and it is reserved for subscribers and licensed report purchasers.
Next steps
Executives and teams preparing capital plans or supplier strategies for 2026 should request the full report to obtain the detailed segmentation, downloadable TCO templates, supplier scorecards, and model inputs required to operationalize the insights summarized above. Visit the PW Consulting report page to review the full table of contents, sample exhibits, and subscription options.
For detailed analysis of this topic, please visit the official page: Worldwide Tubular Tongs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com