

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Rotary Separator Market Set to Grow at 4.71% CAGR Through 2032 as Asia Pacific Leads

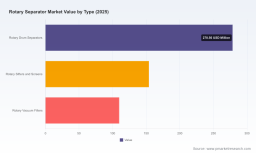
Worldwide Rotary Separator Market: Strategic Imperatives for 2026 — PW Consulting
Executive summary
As industries from agriculture to pharmaceuticals accelerate automation and hygiene-focused processing, rotary separators have emerged as a small-but-critical element of industrial productivity. Our new Worldwide Rotary Separator Market report uses a 2025 base year and a 2026–2032 forecast horizon to quantify how the market is evolving and what that means for capital allocation, product strategy, and M&A in 2026. At the macro level, the market reached USD 542.4 Million in 2025, is estimated to be approximately USD 577.5 Million in 2026, and is forecast to expand at a 4.71% compound annual growth rate to reach roughly USD 748.6 Million by 2032. Historical performance (2020–2025) demonstrates steady recovery and structural growth driven by processing capacity investments, regulatory demand for sanitary equipment, and the replacement cycle of legacy machinery.
Blood Weighing Scale Market
Why this matters for 2026 corporate decisions
-
CapEx prioritization: Companies planning plant upgrades or greenfield builds in 2026 must align separator procurement timelines with capacity forecasts and lead-time risk mitigation plans. Incremental growth disguised in the headline CAGR masks pockets of accelerated demand tied to automation and hygienic retrofits—insights the full report unpacks at a granular level.
Worldwide Renewable Energy Technology Market -
Product strategy: OEMs and equipment suppliers need to choose materials, finishes, and control architectures that balance initial cost with lifecycle performance. Food and pharmaceutical buyers increasingly demand sanitary designs and CIP (clean-in-place) compatibility; material choices such as food-grade stainless alloys are now design requirements rather than optional upgrades.
All-in-One Vital Signs Monitors Market -
Supply‑chain and procurement: Raw‑material dynamics, particularly stainless steel and nickel, are tangible drivers of cost and schedule. Global stainless-steel production reached 64.2 million metric tons in 2025, and nickel—critical to many corrosion‑resistant alloys—has traded in a band approximating USD 15,000–20,000 per metric ton due to supply-side shifts. Procurement teams should incorporate multi‑tier hedging and alternative‑material evaluations into 2026 budgets.
-
M&A and partnership sourcing: The market’s concentration profile (top three and top five manufacturers account for a modest portion of industry revenue) highlights opportunity for consolidation plays, bolt-on acquisitions focused on service networks, and technology tuck‑ins that accelerate product differentiation.
What the PW Consulting report delivers (practical, action‑oriented content)
-
Top‑line market sizing and a seven‑year forecast (2026–2032) with scenario analysis tied to key macro, raw material and regulatory variables.
-
Segmented demand analysis by type, application and geography with buyer-behavior overlays and procurement cycle benchmarks. Note: this release intentionally omits the granular segment tables—access to the full dataset is included with the report.
-
Competitive mapping and supplier scorecards that evaluate product breadth, engineering capabilities, aftermarket reach, and capital intensity.
-
Technology and product dossiers covering hygienic rotary sifters, rotary drum separators, magnetic and centrifugal solutions, and high‑throughput screening systems—each tied to validated use cases, specification checklists, and implementation risk registers.
-
Supply‑chain risk playbook including raw‑material exposure modeling (stainless steel and nickel scenarios), lead‑time stress tests, and mitigation strategies like strategic inventory, dual sourcing, and design-for-alternatives.
-
Commercial playbooks for go‑to‑market in adjacent sectors—waste and recycling, mining, and food processing—together with customer decision-trees and expected payback timelines for typical retrofit and new‑install scenarios.
-
Valuation and M&A screening templates that translate market dynamics into acquisition yardsticks and integration priorities for 2026 deal activity.
Competitive landscape: who matters and why
The rotary separator market remains varied: established machine builders, specialized hygienic‑equipment suppliers, magnetic‑separation manufacturers, and agricultural OEMs all compete for overlapping applications. The market concentration metrics indicate that while several global leaders have meaningful scale, a large portion of demand is served by regional specialists and niche innovators—creating fertile ground for competitive differentiation.
-
Profile Industries (Minnesota, USA): Strength in rotary sorters for food, seed and grain—notable for broad application engineering and aftermarket parts support.
-
Rotex Group (USA) and SWECO (USA): Leaders for high‑capacity gyratory and vibratory screening across minerals and bulk solids, with robust service footprints for large processing plants.
-
Kason Corporation (USA) and Russell Finex (UK): Focused on centrifugal and centrifugal‑force sifters for powders and slurries—preferred by food and chemical processors requiring hygienic designs and gentle handling.
-
Kongskilde Industries (Denmark): Specialist in industrial waste removal and multi‑purpose rotating separators for plastics, paper and packaging lines—an example of product specialization that addresses specific industry pain points.
-
Provisur Technologies (USA): Combines rotary separation with recovery technologies for meat and poultry processing—demonstrating how application‑specific engineering can command premium margins.
-
McLanahan, Ocrim and Doda: Agricultural and grain‑processing specialists that provide turnkey engineering and are key partners for large-scale milling and farming integrators.
-
Great Magtech and Huate Magnet (China), plus erimaki and other regional builders: Providers of magnetic and industrial screening solutions—important for price‑sensitive, high‑volume segments where local service is crucial.
For 2026, suppliers that combine strong aftermarket services, modular product lines, and validated hygienic credentials will be best positioned to capture growth. Strategic alliances between global OEMs and regional specialists can accelerate market penetration without requiring full manufacturing presence in every geography.
Market dynamics and material context
Several cross‑cutting dynamics will shape spending decisions in 2026:
-
Regulatory pressure: Food‑safety and pharmaceutical hygiene standards are driving adoption of sanitary rotary sifters and CIP‑ready equipment. Buyers will trade up to compliant machines to reduce compliance risk and product waste.
-
Automation and throughput: High‑capacity processing requirements in packaging, plastics recycling, and agriculture are increasing demand for robust rotary separators with integrated control and diagnostic features.
-
Raw material volatility: Stainless‑steel availability and alloy pricing are already influencing design economics. With stainless‑steel production at an estimated 64.2 million metric tons in 2025 and nickel prices under pressure from geopolitical and EV‑sector demand, procurement strategies must be integrated into engineering choices to avoid cost overruns.
-
OEM signals: Product updates from large OEMs—such as the introduction of enhanced twin‑rotor combines—are evidence of end‑market investment in separator technology and compel downstream suppliers to synchronize R&D and supply readiness.
Implications and recommended actions for 2026
-
Prioritize modularity: Design platforms that allow hygienic upgrades and alternative materials to manage stainless and nickel exposures without a full product redesign.
-
Lock strategic supply agreements: Negotiate multi‑year commitments with raw‑material suppliers and consider price‑cap collars where appropriate.
-
Expand aftermarket service offers: Service contracts, OEM retrofit kits, and predictive maintenance capabilities increase margins and reduce cyclicality in revenue streams.
-
Targeted M&A: Acquire capabilities that close product gaps (e.g., magnetic separation, high‑hygiene designs) and extend service nets into fast‑growing regional markets.
-
Regulatory readiness audits: Run compliance gap analyses for food and pharmaceutical customers to create prioritized product roadmaps with clear ROI for upgrades.
Methodology and confidence framework
Our analysis synthesizes historical data from 2020–2025, a 2025 base‑year assessment, and scenario‑based forecasts across 2026–2032. The headline projection (4.71% CAGR to 2032) reflects a central scenario calibrated to industry capital projects, raw‑material price paths, and regulatory adoption rates. Sensitivity testing in the report quantifies upside and downside cases if stainless or nickel prices deviate materially, or if automation capex re‑rates faster than anticipated.
Next steps
The summary above highlights the strategic questions that will define leadership in the rotary separator space in 2026. PW Consulting’s full Worldwide Rotary Separator Market report contains the granular segment tables, supplier scorecards, price and volume forecasts, and procurement tools referenced here. These materials are intentionally gated to preserve their tactical value and to enable executive teams to act with confidence.
To obtain the complete dataset, supplier scorecards, and scenario models that support 2026 decision‑making, contact PW Consulting or visit our website to download the report and supporting Excel models. For bespoke advisory—M&A screening, procurement strategy, or product‑line transformation—our industry team is available for rapid engagements.
For detailed analysis of this topic, please visit the official page: Worldwide Rotary Separator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com