

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Rehabilitation Retractor Market Poised to Expand at a 5.85% CAGR Through 2032

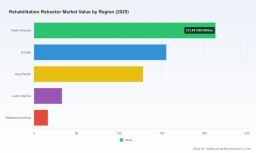
Worldwide Rehabilitation Retractor Market: Strategic Imperatives for 2026 — A PW Consulting Executive Brief
PW Consulting’s new market study on the Worldwide Rehabilitation Retractor market (base year 2025, historic 2020–2025, forecast 2026–2032) equips executives with the quantitative foundation and pragmatic playbook required to make confident decisions through 2026 and beyond. Our integrated forecasting shows a market value of approximately USD 545.6 Million in 2025, growing at a compound annual growth rate (CAGR) of 5.85% across the 2026–2032 projection window. By 2032, the market is projected to approach the low‑to‑mid USD 800 Million range — a trajectory that combines steady clinical demand, product innovation, and increasing home‑care adoption.
Mini LiDAR Market
Why this study matters for 2026 decision cycles
-
Timing: 2026 will be an inflection year for several industry vectors — device modularity, regulatory harmonization for traction units, and payor recognition of home rehabilitation programs. Our study aligns market sizing and demand drivers to that inflection horizon so leadership teams can prioritize investments and partnerships now.
Cell Identification and Characterization Testing Services Market -
Risk‑calibrated growth: With a broadly predictable mid‑single digit CAGR, the opportunity is substantial but not hyper‑rapid. Companies must balance volume plays with margin preservation via differentiated features (safety controls, automated calibration, telemetry) rather than competing purely on price.
Worldwide Respiratory Measuring Devices Market -
Concentration dynamics: Market concentration is meaningful but not prohibitive — the top three players account for roughly 38% of market revenues while the top five collectively control just over half. This creates a two‑track strategic environment: incumbents defend premium clinical relationships while challengers carve niches in cost‑sensitive and home‑use segments.
What the report delivers — practical, decision‑grade content
PW Consulting’s report is built for operators and investors, not just academics. It contains:
-
Proprietary, audited market sizing for 2020–2025 and a transparent forecast model for 2026–2032, delivered in an interactive spreadsheet so teams can re‑run scenarios against their own assumptions.
-
A demand‑driver framework mapping clinical indications, channel evolution (clinical vs. home), and reimbursement regimes to adoption velocity — enabling prioritization of product roadmaps and go‑to‑market resourcing.
-
Regulatory and safety playbook that translates Class II device requirements (illustrated by units such as the ITO TM‑400) into a practical product development checklist and time‑to‑market timeline.
-
Competitive profiles and capability maps for the leading manufacturers and regional challengers — from Chattanooga (Enovis) and Enraf‑Nonius to ITO, OG Wellness, and a curated selection of emerging regional vendors — highlighting technology differentiators, channel footprints, and service models.
-
Commercial guidance: pricing buckets, service & consumables strategies, after‑sales economics, and a distributor selection matrix specific to rehabilitation traction and retractor equipment.
-
Investment and M&A heatmaps identifying consolidation opportunities, white‑space product adjacencies, and bolt‑on targets for incumbents focused on accelerating home rehabilitation offerings.
Competitive landscape — positioning and playbooks
The market exhibits a mixture of established global suppliers and ambitious regional players. Key archetypes and their strategic implications:
-
Full‑line rehabilitation equipment incumbents (example: Chattanooga, part of Enovis) — leverage deep clinical relationships and broad service networks. Their advantage lies in integrated offerings (traction + adjunct rehab modalities) and institutional procurement scale. Strategy: defend clinical exclusivity through bundled contracts, clinical outcomes data, and lifecycle service agreements.
-
Specialist traction innovators (examples: ITO, Enraf‑Nonius, OG Wellness) — focus on device precision, automatic calibration, and multiple traction modes (static, intermittent, progressive). Strategy: translate technical superiority into clinical evidence packages and targeted clinician training programs to accelerate adoption in high‑acuity centers.
-
Regional cost‑agile challengers (examples: V2U Healthcare and a cluster of Asia/EMEA vendors) — compete on price, rapid localization, and simplified user interfaces suitable for outpatient and home use. Strategy: pursue volume through distributor partnerships, low‑touch service models, and digital tutorials to offset limited clinical trial budgets.
-
OEM & component specialists (small manufacturers and electronics firms) — supply critical subsystems (control modules, sensors, tensile systems). Strategy: grow via strategic supplier agreements and licensing into larger OEM platforms where margins can be protected by IP and regulatory know‑how.
Across these archetypes, the most successful firms converge on three winning capabilities: demonstrable safety and outcomes data, scalable aftermarket service, and an integrated channel approach that aligns hospital, clinic, and home‑delivery models.
Regulatory and clinical dynamics to watch in 2026
-
Device classification and compliance: Rehabilitation traction devices are commonly regulated as Class II devices in mature markets. Manufacturers should front‑load compliance activities — risk management, software validation, and human factors testing — to minimize launch delays.
-
Evidence threshold rising: Payors and large healthcare systems increasingly request real‑world evidence of functional improvement, reduced readmissions, or cost‑per‑episode benefits for home rehabilitation offerings. A pragmatic clinical trial design and registry strategy will be a competitive advantage.
-
Interoperability and digitalization: Expect increasing demand for telemetry, session data capture, and integrations with electronic medical records and telerehab platforms. Regulatory scrutiny on data privacy and cybersecurity is intensifying in parallel.
Strategic recommendations for 2026 (actionable priorities)
-
Manufacturers — sharpen portfolio segmentation: Adopt a two‑track product strategy: a premium clinical line emphasizing precision, safety protocols, and service; and a simplified home line focused on reliability, ease of use, and remote support. Avoid one‑size‑fits‑all SKUs that dilute brand positioning.
-
Distributors & channel partners — build bundled care propositions: Move beyond one‑time device sales to subscription models that combine hardware, consumables, clinician training, and remote monitoring. This increases customer lifetime value and captures recurring revenue from home programs.
-
Healthcare providers — pilot tele‑integrated rehab pathways: Launch controlled pilots that pair traction devices with telehealth coaching and outcome tracking to validate cost offsets and patient adherence improvements prior to broad adoption.
-
Investors & corporate development — target differentiated niches: Seek targets that offer one or more of: strong clinical evidence, proprietary control systems/sensors, recurring consumables, or embedded service franchises. Given the market’s moderate concentration, well‑timed M&A can accelerate scale and geographic reach.
-
R&D teams — prioritize safety automation and usability: Invest in automated calibration, fail‑safe controls, and simplified interfaces that enable non‑specialist caregivers to supervise home use with minimal risk.
Supply chain and operational considerations
Operational resilience will determine winners in 2026. Key considerations we outline in the report:
-
Component sourcing flexibility for motors and control electronics to avoid single‑source bottlenecks.
-
Service footprint optimization — use hybrid models combining local third‑party field engineers with centralized remote diagnostics to lower fixed service costs.
-
Localized manufacturing or final assembly in target regions to reduce lead times and enable competitive pricing for cost‑sensitive channels.
What we are intentionally withholding here — and why
In this executive brief we present the market’s macro trajectory and the actionable playbooks executives need to start planning for 2026. In accordance with our “trailer” approach, we deliberately do not disclose core segment tables (detailed splits by geography, device type, or clinical application) or the full financial models that underpin the forecasting. These granular data layers (including regional and application breakouts, channel economics, and our scenario model) are available exclusively in the full PW Consulting report and its accompanying interactive Excel toolkit.
How to use the full report to accelerate 2026 outcomes
-
Run your own sensitivity analyses using our licensed forecast model — test price erosion, accelerated home‑use penetration, or alternative reimbursement scenarios.
-
Access the competitor capability matrix to identify gaps for targeted product investments, partnership or acquisition targets.
-
Leverage our go‑to‑market playbooks to align sales incentives, distributor contracts, and clinical education investments to the 2026 budget cycle.
Final note — strategic clarity meets practical execution
The rehabilitation retractor market offers a pragmatic growth story: predictable mid‑single digit expansion underpinned by clinical demand, incremental product innovation, and a decisive shift toward home rehabilitation services. For 2026, leaders must pair measured capital allocation with focused product differentiation and evidence generation to capture upside. PW Consulting’s full market study provides the quantitative foundation, competitive intelligence, and executional blueprints required to move from strategy to measurable outcomes.
To obtain the complete dataset, scenario models, and the full suite of strategic tools referenced here, visit the PW Consulting website to request the Worldwide Rehabilitation Retractor Market report and associated analytics package.
For detailed analysis of this topic, please visit the official page: Worldwide Rehabilitation Retractor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com