

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Cloud-first SD-WAN Market Set to Expand at a Robust 18.5% CAGR, New Report Shows

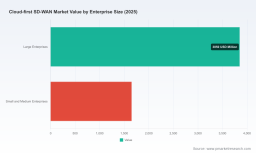
Cloud-first SD-WAN Market: A Strategic Preview for 2026 Decision-Makers
As enterprises shift networking priorities to accelerate cloud adoption, optimize SaaS performance, and unify security at the edge, PW Consulting’s latest Cloud-first SD-WAN Market report (base year 2025) delivers an indispensable strategic lens for 2026 planning. Our analysis synthesizes a rigorous historical review (2020–2025) with a forward-looking forecast through 2032, quantifying a sustained industry expansion at a compounded annual growth rate of 18.5%. The market that reached roughly USD 5.5 billion in 2025 is projected to more than triple by the end of the forecast window — a trajectory that reframes networking procurement, architecture, and vendor selection initiatives for every cloud-first enterprise.
Cloud Incident Response Market
Why this market matters for 2026
-
Execution window: 2026 is not a planning year — it’s the execution year. Investments initiated now will determine whether organizations realize cloud performance gains and security posture improvements or become locked into suboptimal legacy architectures.
10 Gigabit Electrical Interface Modules Market -
Convergence of networking and security: SD-WAN is no longer solely about link aggregation; it’s the conduit for SASE, edge security, and application-aware routing, making vendor choice and architectural patterns critical to long-term operational resilience.
Semi-synthetic Amoxicillin Market -
Fast-moving risk landscape: From supply-chain pressures to evolving regulatory regimes and the emergence of quantum-threat considerations, the stakes around cryptographic hygiene and infrastructure sourcing are escalating.
Market trajectory — what the numbers indicate (strategic takeaways)
PW Consulting’s market sizing shows a pronounced acceleration entering 2026 after steady growth through 2020–2025. With an 18.5% CAGR baked into our base scenario, the Cloud-first SD-WAN market is transitioning from early enterprise adoption to broad mainstream deployment across multiple industry verticals. This creates three strategic realities:
-
Time premium for differentiation: Early adopters that rationalize WAN estates and introduce cloud-native SD-WAN architectures in 2026 will capture outsized operational and cost benefits by 2028–2030.
-
Supply-side specialization: Vendors are increasingly packaging connectivity, acceleration, and security as integrated, managed offerings — buyers must weigh the value of converged platforms versus best-of-breed ecosystems.
-
Capital allocation implications: Network modernization programs should be evaluated not just on initial capex but via TCO across performance, security risk reduction, and cloud access economics over a 3–5 year horizon.
Competitive landscape — positioning themes and implications
The vendor ecosystem in Cloud-first SD-WAN is maturing. Rather than a simple vendor matrix, the landscape is best read as overlapping archetypes: cloud-native network providers leveraging global backbone optimizations; incumbent infrastructure vendors extending SD-WAN as part of broader networking/security suites; and specialist managed-service and AI-driven optimizers focused on internet-first resilience.
-
Aryaka Networks — Positions itself as a cloud-first SD-WAN player with a private global backbone and unified SASE-as-a-service offerings. Strategic implication: organizations prioritizing predictable multi-cloud/SaaS performance and a managed overlay should assess backbone SLAs and peering strategies closely.
-
Bigleaf Networks — Focuses on AI-powered internet optimization and SLA-backed managed services. Strategic implication: enterprises seeking cost-efficient broadband-first resilience with active-path remediation will find this model attractive for distributed locations.
-
Cisco Systems — Brings depth through Catalyst (Viptela) and Meraki portfolios with Cloud OnRamp capabilities. Strategic implication: large, heterogenous estates will value Cisco’s integration breadth, but should evaluate operational complexity and cloud-native fit.
-
Fortinet — Emphasizes integrated Secure SD-WAN with AI-driven optimization. Strategic implication: security-first organizations should benchmark policy orchestration, visibility, and performance trade-offs across encrypted traffic.
-
Versa Networks — Delivers a Universal SASE platform with converged networking and security. Strategic implication: enterprises aiming for unified SASE adoption should examine convergence maturity and migration pathways from legacy appliances.
-
VMware (Broadcom) — Offers cloud-centric SD-WAN via VeloCloud, strong for hybrid/multi-cloud environments. Strategic implication: hybrid cloud operators must map VeloCloud’s orchestration model to their IaaS and SaaS topologies.
-
Palo Alto Networks — Prisma SD-WAN is application-performance-centric with embedded security. Strategic implication: firms with high-compliance workloads will benefit from tight security-policy integration and content inspection capabilities.
-
HPE Aruba — Positions EdgeConnect SD-WAN as an MPLS replacement with a focus on resilience and cost efficiency. Strategic implication: organizations replacing MPLS should validate migration playbooks and user-experience metrics under business-critical loads.
For procurement leaders, the decisive questions are less about vendor logos and more about assurance models: Who owns end-to-end service delivery? How are SLAs measured across multi-cloud paths? What guarantees exist for application experience and security policy enforcement?
Technology dynamics and emerging risks
-
Post-quantum readiness: Not a theoretical concern any longer. Recent market moves — including carrier and vendor launches of quantum-resilient SD-WAN offerings and partnerships to integrate post-quantum cryptography — indicate that forward-looking buyers should include crypto-agility requirements in RFPs where long-term confidentiality is required.
-
AI-driven optimization: Vendors are increasingly embedding ML/AI to automate path selection, congestion remediation, and anomaly detection. Effective evaluation requires buyers to test models under real traffic mixes to validate claimed uplift.
-
SASE convergence: The conflation of SD-WAN and security into SASE continues to define purchasing strategies. Organizations must decide whether to adopt a single-vendor SASE or a hybrid approach combining best-of-breed security controls with SD-WAN routing.
Cost and infrastructure pressures shaping vendor and deployment choices
Network modernization doesn’t occur in a vacuum. Infrastructure cost inputs and policy shifts materially affect total cost and deployment risk. For example, fiber deployment and aerial installation costs remain significant drivers for last-mile strategy, while data center build and power economics shape on-premise versus colocation decisions. Concurrent regulatory dynamics — notably data sovereignty and evolving broadband policy — are creating a patchwork of requirements that influence edge placement and traffic localization strategies.
These factors push organizations to re-evaluate assumptions about MPLS replacement timing, broadband-first resilience strategies, and the economics of managed-SASE bundles versus in-house orchestration.
What PW Consulting’s Cloud-first SD-WAN report delivers (practical, actionable content)
-
Executive decision frameworks to align network modernization with cloud and security roadmaps, enabling CIOs and network leaders to prioritize initiatives for 2026–2028.
-
Vendor scorecards and differentiated capability matrices that map real-world performance, manageability, and security integration — enabling shortlists for RFP and pilot phases.
-
Operational playbooks and migration templates covering site assessment, MPLS-to-broadband cutover, phased SASE adoption, and rollback contingencies to reduce deployment risk.
-
TCO models and ROI calculators that capture capex, opex, connectivity economics, and productivity uplift over a multi-year horizon — designed for CFO-level investment decisions.
-
Security checklists including crypto-agility requirements, post-quantum considerations, and audit-ready policy templates for compliance-driven industries.
-
Procurement-ready RFP language and scoring rubrics that operational teams can deploy immediately to accelerate vendor selection cycles.
How C-suite and network teams should use this report in 2026
-
Board-level narrative: Translate the market trajectory and risk profile into a concise investment narrative, prioritizing programs that reduce cloud friction and address emerging cryptographic risk.
-
Procurement acceleration: Use the vendor scorecards and RFP templates to compress procurement cycles while maintaining rigorous evaluation of SLAs, security posture, and support model clarity.
-
Proof-of-value pacing: Start with high-impact pilots that mirror production traffic and security controls — measure user experience and security telemetry against defined KPIs before broad rollout.
-
Cross-functional alignment: Ensure network, security, cloud platform, and application owners collaborate on policy definitions and failover expectations to avoid operational handoffs that erode promised gains.
Why PW Consulting’s approach is distinct
Our analysis blends quantitative market modeling with qualitative, practitioner-tested deployment guidance. We do not stop at vendor rankings; we translate the forecast (which shows the market expanding from an approximate USD 5.5 billion base in 2025 at a sustained 18.5% CAGR) into executable pathways that reduce risk and accelerate cloud performance outcomes. The report’s methodology, validated through vendor briefings, customer interviews, and hands-on lab verification, is designed to inform decisions that impact both near-term budgets and multi-year platform trajectories.
Next steps — how to act on these insights
-
For CIOs: Commission a 90-day SD-WAN readiness assessment that pairs our migration playbook with live traffic baselining.
-
For CISOs: Integrate crypto-agility requirements and quantum-resistant roadmap milestones into security architecture plans and supplier contracts.
-
For procurement leaders: Leverage the report’s RFP templates and TCO models to move from exploratory pilots to enterprise-wide procurement with clear success metrics.
PW Consulting’s Cloud-first SD-WAN Market report is crafted to arm decision-makers with the analysis and tools required to act decisively in 2026. To preserve the tactical integrity of procurement and competitive intelligence, this preview highlights our principal findings and strategic frameworks while directing practitioners to the full report for vendor-level scorecards, deployment templates, and the detailed financial models that support executive decisions. Access the complete report and supporting toolkits via PW Consulting’s research portal to convert market momentum into measurable business outcomes.
For detailed analysis of this topic, please visit the official page: Cloud-first SD-WAN Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com