

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Juvenile Idiopathic Arthritis Treatment Market Poised to Grow at a 5.4% CAGR Through 2032

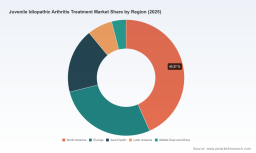
Worldwide Juvenile Idiopathic Arthritis Treatment Market — Strategic Outlook for 2026: PW Consulting Perspective
The juvenile idiopathic arthritis (JIA) treatment market is entering a pivotal phase where clinical innovation, payer dynamics, and supply‑chain realities converge to reshape access and value. PW Consulting’s latest market study — using 2025 as the base year and projecting through 2032 — places the global market at approximately USD 2,350 million in 2025 and forecasts growth to roughly USD 3,396 million by 2032, reflecting a compound annual growth rate (CAGR) of 5.4% over the forecast horizon. For strategic leaders planning 2026 budgets, launches, or M&A activity, these headline figures are only the starting point: the tactical imperatives embedded in the report are the real determinant of success.
Worldwide Integration Software as a Service Market
Why this report matters for 2026 decision‑making
- Actionable forecasting that translates headline growth into route‑to‑market choices: our models explicitly map how variable uptake assumptions, payer responses, and biosimilar penetration alter revenue trajectories across realistic scenarios.
- Balanced risk and opportunity framing: the study synthesizes clinical, regulatory, reimbursement, and supply‑chain signals so leadership teams can prioritize investments with quantified upside and downside cases.
- Playbooks and templates designed for execution: in addition to analysis, the report delivers practical tools — pricing playbooks, payer engagement scripts, HTA dossiers, and launch sequencing frameworks — that accelerate decision cycles in 2026.
Key market dynamics shaping 2026 strategy
- Biologic dominance and the rise of targeted small molecules. Biologics remain the clinical backbone in moderate‑to‑severe JIA, while targeted oral agents and JAK inhibitors are progressively capturing share in specific polyarticular indications. This duality creates differentiated commercial models — infusion/administration logistics versus outpatient oral adherence programs.
- Biosimilars and pricing pressure. The post‑exclusivity era for key TNF inhibitors has materially altered pricing dynamics and access. Biosimilar competition has driven significant list‑price reductions for some originator therapies and changed negotiation levers for payers and hospital systems.
- Regulatory safety communications altering physician behavior. Regulatory advisories — notably FDA requirements for prominent safety warnings on TNF blockers due to infection and malignancy risks in pediatric populations — are shifting treatment algorithms, increasing the importance of clear risk‑benefit communications and long‑term safety evidence.
- Reimbursement nuances for infusion vs. subcutaneous products. Infusion‑based biologics continue to benefit from certain payer coverage pathways, including Medicare Part B billing constructs that influence hospital versus outpatient adoption. Understanding billing drivers remains material to commercial forecasting.
- Supply chain fragility. Shortages in foundational agents used in first‑line regimens have occurred due to API manufacturing disruptions, creating episodic access issues that cascade into prescribing shifts and temporary demand spikes for alternative therapies.
Competitive landscape: what leading companies are positioning for
- AbbVie — Humira (adalimumab): Historically a cornerstone therapy for polyarticular JIA. The loss of primary exclusivity has opened the market to biosimilars, forcing AbbVie to pivot on defense strategies, lifecycle investments, and value‑based contracting to preserve share.
- Amgen — Enbrel (etanercept): A long‑standing TNF blocker in pediatric rheumatology. Safety communications affecting TNF agents require Amgen to double down on education, pediatric data generation, and patient support solutions to sustain uptake.
- Bristol‑Myers Squibb — Orencia (abatacept): Positioned as a T‑cell co‑stimulation option with both infusion and subcutaneous formulations; its reimbursement positioning for infusion products continues to be an important commercial lever.
- Genentech (Roche) — Actemra (tocilizumab): An IL‑6 receptor inhibitor used across systemic and polyarticular forms; the product’s hospital infusion positioning aligns with existing Medicare reimbursement pathways, but WAC and net pricing dynamics warrant careful negotiation and contracting strategies.
- Novartis — Ilaris (canakinumab) and Cosentyx (secukinumab): Novartis is pursuing label expansions into pediatric psoriatic and enthesitis‑related JIA subtypes, reflecting a tactical emphasis on widening indications where unmet need meets commercial feasibility.
- Pfizer — Xeljanz (tofacitinib): The oral JAK inhibitor offers a differentiated oral administration profile; commercialization strategies hinge on demonstrating pediatric safety and durable response versus biologics.
- Swedish Orphan Biovitrum (Sobi) — Kineret (anakinra): An IL‑1 antagonist with an established role in systemic presentations; smaller specialty players can flex agility and clinical engagement to defend niche leadership.
- UCB — Cimzia (certolizumab pegol): A PEGylated TNF option positioned for pediatric use, with strategic focus on patient support and biologic administration convenience.
- Sanofi (with Regeneron) — Dupixent (dupilumab): The recent FDA approval of Dupixent as an add‑on maintenance therapy for polyarticular JIA (October 2024) marks a notable entrant, introducing new mechanistic options and competitive pressure for existing maintenance regimens.
Recent regulatory and market signals to factor into 2026 plans
- New approvals and label expansions are actively reshaping eligible patient pools and commercial positioning (example: recent approvals expanding pediatric indications for biologics).
- Safety advisories for TNF inhibitors continue to affect prescribing preferences and patient counselling requirements.
- Patent expirations have accelerated biosimilar rollouts, with real‑world pricing impacts observed — some originator price points have fallen substantially in competitive markets.
- Payer policy mechanics (e.g., Medicare Part B coverage rules for infusion products) remain a determinative factor for hospital and clinic utilization.
- Supply incidents — such as API‑driven shortages of common injectable methotrexate — can rapidly reallocate demand across therapeutic classes and increase volatility in 12‑ to 18‑month forecasts.
- Pricing datapoints underscore commercial pressures: for instance, list WAC references for certain subcutaneous biologics remain elevated relative to the downward pressure seen for products with biosimilar competition.
What the PW Consulting report delivers — practical content for execution
- Top‑down and bottom‑up market sizing with transparent assumptions; scenario models quantify the impact of biosimilar penetration, policy shifts, and supply disruption on revenues to 2032.
- Competitor playbooks that include positioning maps, launch readiness checklists, and likely commercialization countermeasures for the next 18 months.
- Payer and HTA engagement templates tailored to pediatric rheumatology, including economic model outlines and stakeholder messaging for different healthcare systems.
- Supply‑chain risk registry and mitigation matrix that identify critical API nodes, alternative sourcing strategies, and inventory hedging options calibrated for 2026 operational cycles.
- Investment and M&A heatmaps highlighting therapeutic niches and capability gaps where bolt‑on deals or licensing could accelerate time‑to‑market.
- Interactive financial model (Excel) and slide‑ready summaries for board and investor briefings that translate epidemiology and uptake into investible KPIs.
Top recommendations for 2026 (prioritized)
- Reconcile portfolio sequencing with payer levers: prioritize label expansions and formulations that align with payer coverage pathways and reduce reliance on hospital‑based infusion reimbursements.
- Design differentiated access approaches for biosimilar environments: originators should combine targeted rebates, real‑world evidence (RWE) generation, and patient support to defend value; biosimilar entrants must focus on contracting speed and provider conversion.
- Secure upstream supply resilience: implement multi‑source API contracts and buffer stock strategies for agents where substitution is clinically constrained, especially given prior methotrexate shortages.
- Accelerate pediatric safety and outcomes data collection: with regulatory safety communications influencing prescribing, robust pediatric long‑term safety RWE will be a competitive moat.
- Pursue selective M&A/licensing for modality diversification: acquiring or licensing small molecule/biologic adjacencies can de‑risk pipelines in the medium term.
- Operationalize value‑based contracting pilots where outcomes can be objectively measured, reducing payer resistance and creating stickiness in formulary placements.
Scenario triggers to monitor in 2026
- Major biosimilar launches with aggressive contracting in key markets.
- New safety advisories or label changes for TNF inhibitors or emerging small molecule classes.
- Supply interruptions at API origin points or changes in manufacturing capacity that affect core injectables.
- Payer policy shifts affecting infusion reimbursement or uptake of subcutaneous/self‑administered options.
- Clinical readouts or regulatory decisions that materially expand pediatric indications for non‑TNF mechanisms.
In a market where clinical complexity, payer power, and supply vulnerabilities intersect, the difference between strategic consensus and decisive execution is clarity of scenarios and the availability of tested playbooks. PW Consulting’s Worldwide Juvenile Idiopathic Arthritis Treatment Market report provides both: rigorous forecasting grounded in transparent assumptions, and the practical, executable levers that commercial, clinical development, and corporate strategy teams will use to shape 2026 outcomes.
Worldwide Retail LMS Software Market
For the full dataset — including detailed segmentation, country‑level revenue splits, and the granular models that underpin our scenarios — please consult the complete PW Consulting report and interactive dashboard. The executive summary above is deliberately high‑level to preserve the integrity of the underlying, proprietary subsegment analyses available in the full publication.
Power Transmission Cables Market
For detailed analysis of this topic, please visit the official page: Worldwide Juvenile Idiopathic Arthritis Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com