

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
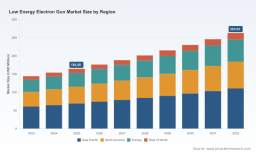
PW Consulting: Worldwide Low Energy Electron Gun Market to Grow from USD 164.9 Million in 2025 to USD 263.0 Million by 2032 at a 6.85% CAGR — Asia Pacific Leads with USD 69.3M

PW Consulting Strategic Brief: Worldwide Low Energy Electron Gun Market — Actionable Intelligence for 2026 Decision-Makers
Executive summary
PW Consulting’s latest market study on the Worldwide Low Energy Electron Gun market (base year 2025, historical window 2020–2025, forecast 2026–2032) delivers a concise, decision-focused synthesis for corporate strategists, procurement leads, R&D heads, and M&A teams preparing plans for 2026. The market is expanding steadily, with a compounded annual growth rate of 6.85% through our forecast horizon. Total industry revenue is anchored at approximately USD 164.88 Million in 2025 and is forecast to reach roughly USD 176.26 Million in 2026, progressing toward an estimated USD 263.03 Million by 2032. Market concentration is moderate, with the top three and top five suppliers accounting for meaningful but not dominant shares (CR3 and CR5 metrics highlight a balance between incumbents and specialist entrants).
Micro-Barrel Connectors Market
Why this matters for 2026 planning
Low energy electron guns (LEEGs) are a core enabling technology across surface analysis, semiconductor metrology, nanoscience, and emerging industrial imaging use-cases. The measured growth trajectory—steady, technology-led, and resilient to cyclical headwinds—creates a window for strategic investments that can materially improve competitive positioning in 2026. Suppliers and end-users face a mix of regulatory complexity, technology differentiation, and supplier-side cost pressures; the right strategic moves this year will compound advantages over the coming 3–5 years.
Worldwide Automotive Thermostat Valve Market
What the study delivers: practical intelligence, not vanity metrics
- Market sizing and validated forecast (2026–2032) with clear assumptions and scenario variants to support budgeting and capex prioritization.
- Competitive landscaping focused on product families, engineering capabilities, aftermarket services, and supplier economics rather than raw unit counts.
- Regulatory and standards matrix (EU import/operation licensing, regional registration regimes, and ISO calibration/sterilization standards) mapped to product and end-use risk profiles.
- Supply chain vulnerability assessment, including cathode commodity and vacuum-system dependencies, with mitigation playbooks for procurement teams.
- Transaction playbook — valuation drivers, integration risks, and quick-win synergies for M&A or JV opportunities.
Key market dynamics shaping 2026 decisions
- Steady growth with room for premiumization: The projected CAGR of 6.85% reflects sustained demand across research and industrial segments. This supports selective premium product rollouts and service monetization strategies.
- Supplier pricing and cost pressure: Recent supplier moves have signaled pricing re-calibration. Suppliers and OEM partners should model margin sensitivity to component cost inflation and consider tiered pricing or bundled service offerings.
- Regulatory and standards friction: Several jurisdictions require explicit licensing, registration, or demonstrated conformity to standards for installation and operation. Regulatory compliance is now a board-level operational risk in many deployments.
- Technology differentiation: Multiple electron source architectures and cathode materials remain commercially relevant. Design choices (e.g., cathode chemistry, emission mechanism, spot size control, UHV compatibility) are increasingly determinants of value capture.
- Moderate concentration, meaningful specialist niches: Market concentration metrics indicate that while a few established suppliers command significant positions, there is ample room for specialist entrants and differentiated service models.
Competitive snapshot — implications for partnering and rivalry
The competitive set spans legacy OEMs, specialist surface-science vendors, and components-focused manufacturers. Key names include established U.S. and European suppliers known for broad product portfolios and customization capability, as well as global microscopy and industrial systems players with integrated offerings. Recent firm-level developments—such as supplier product catalog refreshes and pricing adjustments—underscore an active market where product refresh cycles, aftermarket support, and supply continuity are material differentiators.
Wireless HART Gateways Market
- For incumbent suppliers: prioritize modular product platforms and predictable aftermarket revenue streams (service contracts, spare cathodes, power supplies), and accelerate digital diagnostic capabilities to reduce field service costs.
- For new entrants and component specialists: pursue narrow, high-margin niches (e.g., high-current flood sources, specialty cathodes, compact analytical guns) and build alliances with instrument OEMs to accelerate validation cycles.
- For system integrators and OEM customers: implement multi-sourcing strategies, and embed long-lead items into contracts to mitigate single-vendor disruptions.
Regulatory and standards checklist for 2026
Regulatory constraints and standardization requirements materially affect time-to-market, total cost of ownership, and installation complexity. Notable compliance elements that should be integrated into 2026 plans include:
- EU licensing and CE requirements for self-shielded electron beam systems; risk analyses and conformity documentation are essential prior to deployment.
- Registration obligations in North American jurisdictions for radiation-emitting equipment — suppliers and end-users must budget administrative lead time and local compliance costs.
- ISO-level calibration and sterilization norms relevant to metrology and healthcare applications (e.g., kinetic energy calibration standards and radiation sterilization requirements). Integrating these standards into product development reduces aftermarket friction and supports premium pricing.
Supply chain and materials — constraints and opportunities
Cathode materials and ultra-high vacuum components are technical bottlenecks for many LEEG product families. Common cathode chemistries have distinct performance and lifetime trade-offs; sourcing strategies should therefore consider long-term availability, substitution risk, and supplier qualification timelines.
- Develop dual-source strategies for critical cathode types and high-precision vacuum components to reduce single-point failure risk.
- Invest in cathode lifetime testing and predictive maintenance algorithms to transform consumable replacement into a service revenue stream.
- Where feasible, pursue co-development arrangements with material suppliers to secure priority supply and improve unit economics.
R&D and product strategy recommendations for 2026
- Prioritize modular architectures that enable rapid reconfiguration across emission mechanisms (thermionic, field emission, photoemission) without full platform redesign.
- Invest in miniaturization and low-power control electronics to broaden addressable applications (benchtop analyzers, in-situ process monitoring) and capture adjacent markets.
- Embed compliance-by-design: document calibration procedures, risk analyses, and sterilization pathways during product development to shorten regulatory cycles.
- Accelerate development of digital diagnostics and remote-service capability to lower cost-of-service and improve uptime guarantees — a differentiator valued by high-utilization end-users.
Commercial and pricing playbook
Given supplier pricing adjustments observed in the market and the steady demand profile, go-to-market strategies should blend product differentiation with flexible commercial terms:
- Introduce tiered warranties and performance-based pricing to share operational risk with customers and to capture upside from higher-utilization sites.
- Sell solutions, not just components: combine hardware with calibration services, spare parts subscriptions, and training packages to raise switching costs and improve margin visibility.
- Negotiate long-term supply and price escalation clauses with critical component vendors, using forecast visibility to secure capacity and shield margins from short-term spikes.
M&A and partnership lens for 2026
The market’s moderate concentration and the fragmented specialist landscape create transactional opportunities that can be executed quickly with compact integration risk:
- Acquaint targets with stable recurring revenues (service contracts, consumables) that improve acquirers’ cash-profile and cross-sell potential.
- Look for bolt-on acquisitions that provide unique cathode IP, miniaturized gun designs, or niche high-current flood sources to accelerate product roadmaps.
- Use strategic alliances to access regional compliance expertise, distribution networks, or laboratory validation facilities rather than attempting greenfield entry in heavily regulated jurisdictions.
Scenario planning — preparing for three plausible 2026 states
- Base case (most likely): Continued steady growth along forecast trajectory. Firms focusing on modular products and services capture disproportionate share gains.
- Upside case: Accelerated adoption in adjacent industrial use-cases (e.g., in-line metrology, manufacturing process monitoring) drives faster-than-expected premium product uptake — favor aggressive commercial expansion and capacity investments.
- Downside case: Heightened regulatory friction in key markets or raw material shortages compress near-term volumes. Prioritize liquidity management, supply chain hedging, and contractual flexibility.
How PW Consulting’s report supports 2026 decisions
This study is built to be operational: beyond headline forecasts, it provides scenario-based financial models, supplier due-diligence templates, a regulatory compliance checklist keyed to likely jurisdictions, and a transaction playbook with valuation sensitivities. Importantly, we deliberately withhold granular segmentation tables in this briefing to protect the tactical insights contained in the full report; these detailed splits and supplier-by-supplier profiles are available in the paid report package and through direct consultation.
Immediate next steps for leaders
- Procurement: Lock-in dual-source agreements for critical cathodes and UHV components; run stress tests on supplier continuity.
- Product & Engineering: Initiate modularization sprints and certify designs for applicable ISO and CE requirements to minimize time-to-deploy.
- Corporate Development: Screen acquire-or-partner targets that provide consumables revenue, niche IP, or regulatory footholds in restricted geographies.
- Compliance & Quality: Establish a regulatory roadmap for each target market and integrate conformity evidence into product design plans.
Closing — why 2026 is a tipping point
The low energy electron gun market is entering a phase where disciplined product strategy, supply chain resilience, and regulatory fluency will determine which organizations capture the expanding value pool. With the market moving from a research-dominated footprint to broader industrial adoption, 2026 is the year to convert technical competence into defensible commercial advantage. PW Consulting’s full report provides the granular segmentation, supplier profiles, and tactical annexes you will need to operationalize these recommendations. For access to the complete dataset, segmentation tables, and bespoke advisory support, visit our report page or contact PW Consulting directly.
For detailed analysis of this topic, please visit the official page: Worldwide Low Energy Electron Gun Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com