

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Global Pharmaceutical-Grade Bentonite Powder Market Poised to Expand at a 5.35% CAGR

PW Consulting Releases Strategic Brief: Worldwide Pharmaceutical Grade Bentonite Powder Market — Strategic Imperatives for 2026
PW Consulting today publishes an executive-level overview of our new market research: Worldwide Pharmaceutical Grade Bentonite Powder Market (base year 2025). The study synthesizes five years of historical analysis (2020–2025) and a forward-looking forecast (2026–2032), delivering the actionable intelligence life‑science, pharmaceutical supply‑chain and specialty minerals leaders need to shape strategy in 2026 and beyond.
Electrohydraulic Servo Valve (EHSV) Market
Snapshot: scale, trajectory, and concentration
-
The market expanded steadily through 2025, rising from the low‑nine‑dozens (Million USD) territory in 2020 to an established base in 2025. Our modelling projects continued expansion across the forecast window to 2032, reflecting a compounded annual growth rate (CAGR) of 5.35% over the 2026–2032 forecast period.
Worldwide Thermography Software Market -
Market structure is neither atomized nor monopoly: the three largest suppliers command a meaningful share (CR3 ~42%), while the top five firms account for roughly 58% of market volume — a profile that creates both consolidation opportunities and tactical openings for well‑capitalized challengers.
Worldwide Inbound Call Tracking Software Market -
Price dynamics and feedstock availability are now material strategy levers. In early 2026 Europe experienced a notable uptick in bentonite spot pricing versus late 2025, while North American prices softened in the same window — developments that directly affect margin and sourcing decisions for pharmaceutical‑grade buyers.
Why this report matters to executive teams in 2026
-
Supply‑chain resilience is a boardroom topic: pharmaceutical manufacturers need validated, pharmacopeia‑compliant inputs, and bentonite is no exception. Our report translates market signals into board‑level implications for procurement, quality and R&D.
-
Regulatory risk is concrete and quantifiable. Pharmaceutical‑grade bentonite must meet USP/EP/NF thresholds — including tight limits on heavy metals (typically below ~10 ppm), impurity and microbial controls (commonly maintained under ~2%), and specification requirements for montmorillonite content (industry practice targets in excess of ~70%). These constraints reshape supply qualification and cost curves.
-
Capital allocation choices for 2026 hinge on credible upside scenarios: should companies pursue insourcing, long‑term supply contracts, vertical integration, or bolt‑on acquisitions? Our scenario modelling quantifies the revenue and margin sensitivities under different strategic paths.
Key market dynamics shaping 2026 strategies
-
Demand quality over quantity: end‑use growth is driven by formulation needs — excipient roles in tablets and capsules, stabilization in suspensions and emulsions, and increasing interest in topical applications. Buyers are placing a premium on traceability, batch consistency and documented pharmacopeial compliance.
-
Supply fundamentals: selective mining, beneficiation (frequent water‑washing or equivalent purification) and rigorous impurity removal are prerequisites for NF/USP‑grade bentonite. These processing steps raise cost but are non‑negotiable for pharmaceutical application.
-
Price signals and input volatility: regional price movements in early 2026 underscore how end‑market demand (industrial vs pharmaceutical) and production costs interplay. Europe saw a near‑double‑digit percentage increase versus late 2025, while North America experienced a mid‑single‑digit percentage easing in the same period — dynamics that inform near‑term hedging and contract length decisions.
-
Regulation and quality governance: with pharmacopeial compliance enforced by regulatory authorities, manufacturers must maintain rigorous supplier qualification, regular heavy‑metal testing, and validated microbial control. Non‑compliance is an existential risk for pharma buyers and creates premiums for certified suppliers.
Segmentation and application landscape — what the report covers (without revealing trade secrets)
-
Product types: the market is principally bifurcated by sodium and calcium bentonite chemistries, each with differentiated processing requirements and formulation roles. Our study maps the functional advantages, qualification pathways and margin profiles for both product families.
-
Applications: we examine the role of pharmaceutical‑grade bentonite across core use cases — suspensions & emulsions, tablet and capsule excipients, topical formulations, and other specialty detox and ancillary uses — and translate these into demand curves and product specs.
-
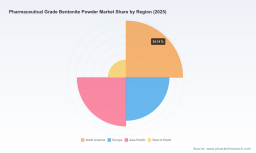
Regional dynamics: the report contains a regional analysis covering demand drivers, supply base characteristics and trade flows—valuable for sourcing and market entry. (Note: in this public summary we withhold the granular split data to preserve the analytical integrity of the primary dataset.)
Competitive landscape — profiles and strategic implications
We profile the most consequential players active in pharmaceutical‑grade bentonite today and derive tactical implications for buyers, suppliers and investors. The report’s company intelligence includes public and proprietary data, capability mapping and supplier scorecards.
-
Kutch Bentoclay (India) — A focused manufacturer and exporter of high‑purity sodium bentonite, notable for pharmacopeial compliance and export orientation. Strategic implication: strong alternative for companies seeking lower‑cost validated sources with export capacity.
-
Minerals Technologies / Bentonite Performance Minerals (United States) — Operating Wyoming sodium deposits, BPM brings scale and consistent grades for pharmaceutical applications. Strategic implication: scale + established quality systems create a supply anchor for large formularies.
-
Wyo‑Ben, Inc. (United States) — Domestic producer with access to Wyoming resources, important for North American onshore sourcing and shorter lead times for qualifying batches.
-
Ashapura Minechem and other Indian integrated producers (e.g., CMS Industries, Seema Minerals & Metals, J&H Minerals, Pratham Minechem) — High monthly production capacity, ISO certifications and a focus on export markets make India a strategic pool for pharma buyers seeking volume and price discipline.
-
Imerys and Kunimine Industries — Global mineral specialists with diversified portfolios and technical support capabilities, offering opportunities for co‑development and long‑term partnership models.
Across these profiles, the strategic themes are consistent: certification and traceability command a premium; geographic diversification of supply reduces regulatory and logistic risk; and vertical integration — whether via upstream interest in mining assets or downstream blending/packaging — is increasingly attractive to secure quality‑assured volumes.
What the PW Consulting report delivers — pragmatic, execution‑facing outputs
-
Market models and forecasts (2026–2032): scenario‑based revenue and volume projections with sensitivity analyses around price shocks, regulatory tightening and demand shifts.
-
Supplier scorecards and due‑diligence templates: third‑party audit checklists, pharmacopeial compliance verification steps, and supplier risk ratings to accelerate supplier qualification.
-
Procurement playbooks: recommended contract structures (indexing, fixed‑term, rolling), dual‑sourcing frameworks, and cost‑to‑qualify calculators to estimate the real economics of switching or qualifying new suppliers.
-
Commercial and R&D guidance: formulation impact assessments by bentonite chemistry, cost versus functionality tradeoffs, and guidance for reformulation to manage raw material inflation.
-
M&A and partnership intelligence: target screening criteria, valuation sensitivity checks, and integration checklists tailored to bentonite assets and service providers.
-
Interactive dashboards and proprietary datasets: downloaded models, regional demand drivers, and supplier performance metrics that empower in‑house analysts and strategy teams.
How to use this intelligence in 2026 — pragmatic next steps
-
Procurement and quality teams should immediately update supplier qualification timelines to incorporate enhanced heavy‑metal and microbial testing cadence and evaluate contracting models that hedge short‑term price volatility.
-
R&D should run parallel formulation trials comparing sodium vs calcium grades to identify cost‑neutral substitution windows and to quantify any downstream stability tradeoffs.
-
Strategy and corporate development teams should prioritize bolt‑on acquisition targets in jurisdictions where supply risk is high or where certification barriers create defensible margins.
-
Risk and compliance functions must codify pharmacopeial thresholds into SLAs and acceptance criteria, and ensure that supplier audits and documentation (COAs, traceability chains) are enforced contractually.
Conclusion — why this is a 2026 boardroom imperative
Pharmaceutical‑grade bentonite is a small but strategically significant input for many formulations. The market’s steady mid‑single‑digit CAGR and the current supplier concentration profile create both opportunity and exposure for drug manufacturers, contract formulators and specialty minerals players. Price signals in early 2026 and stringent regulatory expectations emphasize the need for proactive commercial, quality and supply‑chain strategies.
PW Consulting’s comprehensive report provides the empirical foundation and execution tools to design those strategies. For executives preparing 2026 budgets, sourcing roadmaps and M&A pipelines, our research converts market complexity into operationally prescriptive guidance — while preserving the proprietary models and supplier scorecards that accelerate implementation. To access the full dataset, downloadable models, supplier scorecards and interactive dashboards, please visit the PW Consulting report page.
For detailed analysis of this topic, please visit the official page: Worldwide Pharmaceutical Grade Bentonite Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com