

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
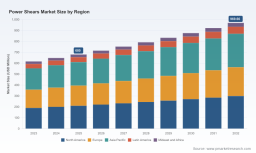
PW Consulting: Worldwide Power Shears Market to Grow from USD 680.0 Million in 2025 to USD 969.66 Million by 2032 at a 5.2% CAGR

Worldwide Power Shears Market — Strategic Briefing for 2026 Decisions
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a concise, insight-driven briefing drawn from our new Worldwide Power Shears Market report (base year 2025, forecast 2026–2032). The industry is moving from post‑pandemic recovery into a technology-led upgrade cycle. This briefing highlights the macro trajectory, the near-term decision levers for 2026, competitive posture observations, and the practical intelligence contained in the full report. To preserve the highest commercial value of our segmented datasets and granular models, we intentionally withhold detailed subsegment tables here; the full dataset is available through our report portal.
Fireproof Doors Market
Executive snapshot
The global power shears market has demonstrated steady expansion in recent years, with total market revenue rising from USD 616.0 Million in 2023 to USD 680.0 Million in 2025. Our model projects continued growth at a compounded annual growth rate (CAGR) of 5.2% across the 2026–2032 forecast window, lifting total market revenue toward the high‑nine‑hundreds of millions by 2032. Market concentration is moderate: the top three vendors control a meaningful share but do not exhibit the lock‑in seen in adjacent heavy machinery categories (CR3 ~38.5%; CR5 ~52.1%).
Worldwide Digital Marketing Analytics Market
Why this matters for 2026 corporate planning
-
Capital allocation: The mid‑single digit CAGR and predictable replacement cycles enable disciplined CAPEX planning — both for incumbents expanding automation portfolios and for end users upgrading shop-floor tooling.
Worldwide Manufacturing Intelligence Software Market -
Product roadmap timing: 2026 is a pivotal year to operationalize Industry 4.0 enablement (CNC integration, digital controls, predictive maintenance) before mandatory regulations and buyer expectations accelerate adoption.
-
M&A and partnership scouting: Moderate concentration and attractive mid-market dynamics create fertile ground for bolt‑on acquisitions and distribution partnerships, especially for firms seeking geographic expansion or automation software capabilities.
Market trajectory and interpretation
The revenue trend from 2023 through our base year (2025) shows resilient demand driven by refurbishment cycles in fabrication, steady construction activity in key markets, and rising interest in cordless and highly automated solutions among OEMs and contracting shops. Our 2026–2032 forecast reflects a combination of sustained replacement demand, incremental penetration of automation and digital services, and cyclical sensitivity to raw material price shifts and trade policy dislocations.
Key dynamics shaping 2026 choices
-
Raw material cost volatility: Input cost moves—illustrated by materially higher rolled steel and scrap prices in 2024—are compressing margins for fabricators and influencing buyer price sensitivity for capital equipment. Suppliers need nimble pricing and value‑packaged financing to maintain order flow when steel price spikes pressure buyers’ cashflows.
-
Regulatory acceleration: New machinery and digital safety mandates (notably regional regulatory frameworks introducing requirements for documented digital risk assessments) will force OEMs and large end users to adopt formal control and traceability features by 2027. Firms that preempt compliance with integrated software and evidence trails will realize procurement advantages.
-
Labor and productivity pressure: Significant unfilled fabrication jobs in large manufacturing markets persist. This structural labor tightness is driving demand for automation, ergonomic tooling, and lower‑skill operation modes — a long‑term demand accelerator for CNC‑enabled and easier‑to‑operate shears.
-
Trade and tariff effects: Continued import tariffs on key inputs in some jurisdictions increase the total landed cost of equipment. Manufacturers with localized supply footprints or strong supplier hedging strategies have a competitive cost advantage in 2026.
Competitive landscape — what we observe
The competitive field includes established global OEMs and strong regional specialists. Our coverage profiles the strategic positioning and recent initiatives of leading players, with emphasis on product innovation, automation partnerships, and market reach. Select highlights:
-
Cincinnati Incorporated (Harrison, OH) continues to push CNC control enhancements in its Ace series, spotlighting operator productivity and integration at industry shows.
-
Amada Co., Ltd. (Isehara, Japan) remains focused on precision mechanical and hydraulic shears, recently emphasizing angled‑cut solutions attractive to specialty fabrication applications.
-
Durma Makina and several European manufacturers are expanding their variable‑rake CNC offerings and heavy‑duty platforms for plate and shipbuilding segments, aligning product families to higher capacity needs.
-
Smaller and mid‑market suppliers (including firms specializing in ironworkers, pneumatic systems, and compact hydraulic units) are leveraging distribution networks and aftermarket service to defend share against larger system integrators.
Our granular company profiles include headquarters, product focus, channel footprints, and a short tracker of recent public activities (product launches and trade show debuts through late 2024). These corporate vignettes help executives benchmark technology roadmaps and identify potential collaboration or acquisition targets.
Recent industry moves and what they imply
-
Product refreshes and trade show activity in 2023–2024 demonstrate a clear race to embed smarter CNC controls and software ecosystems into shear platforms — a precursor to larger aftermarket services pools (remote diagnostics, consumables, and paid upgrades).
-
New variable‑rake and precision miter solutions suggest suppliers are targeting niche premium segments where value capture is higher and price elasticity lower.
-
Overall, innovation is incremental and execution‑centric: the winners will be firms that combine mechanical reliability with software and services capable of reducing total cost of ownership for customers.
What the PW Consulting report delivers (practical content)
Our Worldwide Power Shears Market report is structured to support executable decisions in 2026 across commercial, product, and M&A agendas. Key practical components include:
-
Top‑line market model: historical series (2020–2025) and detailed forecasts (2026–2032) with scenario toggles for macro drivers and commodity shocks.
-
Demand drivers matrix: segment‑level narratives (by product family, application cluster, and distribution channel), elasticity estimates, and replacement cycle windows. Note: While we summarize drivers here, the full report contains the granular segmented datasets and sensitivity tables behind these narratives.
-
Supplier benchmarking: operational profiles, technology stacks, aftermarket strategies, and a proprietary scoring rubric for build vs buy decisions.
-
Commercial playbooks: pricing checklists, finance/leasing program templates, and a three‑step field validation guide for piloting automation-enabled shears in production environments.
-
M&A and partner pipeline: identification of high‑fit targets by capability and region, informed by our CR3/CR5 concentration analysis and distribution gap mapping.
-
Risk and compliance compendium: a staged plan to align products and documentation with emerging machinery safety and digital assessment mandates.
Actionable recommendations for 2026 (four focus moves)
-
Prioritize retrofit and digital services: For OEMs, accelerate offerings around digital control retrofits and subscription‑style diagnostics. For fabricators, plan pilot deployments of remotely monitored shears to quantify labor and uptime gains within 6–12 months.
-
Hedge input cost exposure: Implement input price indexing in major contracts or expand localized sourcing in tariff‑sensitive geographies. Maintain flexible financing offers tied to commodity cycles to keep order pipelines active.
-
Design compliance roadmaps: Embed regulatory readiness for digital risk assessment requirements into product release schedules in 2026, converting compliance to a marketable safety differentiator.
-
Pursue targeted inorganic moves: Use CR and gap analysis to identify regional distributors and software control specialists for bolt‑on acquisitions that can accelerate access to automation and aftermarket service revenue.
How to use this intelligence
Executives should use the report as a near‑term playbook to set 2026 budgets, prioritize product investments, and build M&A screening lists. Operational teams will find the benchmarking and pilot templates immediately actionable for shop‑floor proof‑of‑concepts. Investment teams can leverage our scenario outputs to stress‑test valuation models against commodity and regulatory shocks.
Closing — where to get the full dataset
This briefing is intended as a strategic preview. Full access to the segmented tables, regional and application breakdowns, supplier scorecards, and interactive forecast models is available in the complete Worldwide Power Shears Market report. Visit PW Consulting’s report portal to request a sample, arrange a briefing with our analyst team, or license the dataset for integration into enterprise planning systems.
For decision makers preparing 2026 strategies, the time to act is now: align product roadmaps to automation and compliance requirements, secure supply and pricing flexibility, and consider targeted M&A to close capability gaps. PW Consulting’s detailed models and execution playbooks will shorten the path from insight to market impact.
For detailed analysis of this topic, please visit the official page: Worldwide Power Shears Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com