

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Carbon-14 Market to Expand at a 6.51% CAGR Through 2032, Fueling Growth in Drug Development

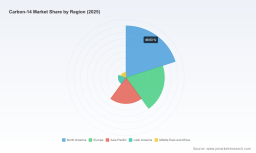
Worldwide Carbon-14 Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a distilled briefing from our forthcoming Worldwide Carbon-14 Market study. This release is designed as an executive trailer: it reveals the structural drivers, strategic inflection points, and practical frameworks that should shape corporate decisions through 2026 — while reserving the report’s full, transaction-grade segment tables and supplier scorecards for subscribers and clients.
Worldwide Medical Spray Market
Why Carbon-14 matters to corporate strategy in 2026
Carbon-14 is no longer a niche input confined to radiocarbon dating. Over the last half-decade it has moved from constrained supply and episodic scarcity to a more diversified supply landscape, driven by technology innovations (reactor harvest, enrichment) and new commercial entrants. The market’s overall size reached approximately USD 239.7 Million in our base year (2025) after steady expansion from 2020. Under our central forecast, the market will continue to expand through the decade, reaching an estimated USD 372.5 Million by 2032 — a compound annual growth rate of 6.51% for the 2026–2032 period. This trajectory underscores Carbon-14’s growing strategic relevance to pharmaceutical R&D, diagnostic development, environmental science, and specialized industrial research.
Variable Inductance Shunt Reactors Market
What this preview covers — and what we deliberately withhold
- We outline the macro growth drivers, supply/demand dynamics, regulatory inflection points, and competitive behaviors that will determine access and pricing in 2026.
- We summarize the operational and strategic implications for buyers, suppliers, and investors: procurement hedging, capacity investment, partnership structures, and M&A plays.
- We intentionally do not disclose detailed numeric splits for regional, application, or product subsegments in this release. Those granular tables and supplier-specific production volumes are available only in the full report and client appendices — precisely the intelligence needed for contracting, tendering, and diligence.
Market dynamics: supply diversification and the end of chronic shortage
From 2020 to 2025 the market expanded meaningfully as demand from drug development and diagnostic applications accelerated. Historically, supply bottlenecks were a principal market constraint: a small number of reactor-sourced producers and a reliance on legacy facilities created intermittent shortages that cascaded into price volatility and project delays for end-users.
Hemostasis Reagent Market
That dynamic is changing. In 2025 several structural supply shifts occurred that matter for 2026 planning:
- Commercial heavy-water reactor production has scaled to commercial dispatch and, in at least one case, export. This transition converts previously local or intermittent supply into a continuous, contractable stream.
- New enrichment technologies and commercial facilities have entered production, adding flexibility — particularly for enriched 14C grades used in high-value pharmaceutical and diagnostic applications.
- Innovative harvest-from-waste approaches are emerging, reducing the market’s historical dependence on a small set of legacy sources.
Collectively these developments reduce tail-risk for buyers, but they also create a two-speed market: a baseline of more predictable commodity-grade supply and a premium layer for high-specific-activity material and contracted specialty services. Strategic purchasers should therefore differentiate between commodity hedging and value-chain partnerships that secure priority access to premium product streams.
Regulatory and quality pathways that determine market access
For pharmaceutical and clinical applications, regulatory compliance is the gating factor. The market is shaped not only by isotope availability but by the ability to deliver GMP-compliant carbon-14 labelled APIs, traceable supply chains, and validated analytical support. One prominent supplier has publicly aligned its manufacturing to relevant U.S. regulatory guidance, illustrating how regulatory alignment is a competitive moat.
In practice, this means that contracts for supply intended for clinical programs should be evaluated not just on price and volume, but on documented regulatory readiness: validated processes, GMP certifications, batch traceability, and analytical stability studies. Our report includes a regulatory matrix that maps common use-cases to compliance checklists — a tool designed to reduce audit cycles and time-to-study enrollment.
Competitive landscape — who matters in 2026
The market is concentrated: the top three suppliers control a meaningful majority of commercial volumes, and the top five expand that dominance further. That concentration has softened slightly with new entrants and alternative production routes, but supplier selection remains a strategic decision.
Key market participants to monitor:
- RC14 (Canada) — pioneering sustainable harvesting from reactor waste, positioning itself as a long-term supplier for pharmaceutical and agrochemical customers seeking predictable, recycled-feed sources.
- China National Nuclear Corporation / Qinshan operations — commercialized reactor production and, following recent activity, commenced international exports; this introduces a new scale source that market actors must now factor into global procurement strategies.
- ASP Isotopes — launched an enrichment route in 2025 that adds materially to the premium-grade supply pool, particularly for clients requiring enriched isotopes for high-sensitivity assays.
- Established radiochemistry service providers (e.g., Moravek, Almac Group, Selcia/Eurofins, Novandi, ARC) — these firms convert bulk isotope supply into GMP-labelled APIs, custom radiolabelling services, and end-to-end analytical packages that many drug developers rely upon.
For buyers, the strategic takeaway is clear: secure a mix of tiered relationships. Commodity hedges with scale producers guard operating continuity; strategic partnerships with contract radiochemistry specialists create prioritized capacity for development and clinical phases. For investors, the differentiated value lies in companies that couple feedstock access with regulatory-service capabilities.
Strategic implications and recommended actions for 2026
Below are pragmatic, prioritized actions we recommend for corporate leaders whose 2026 plans depend on reliable access to Carbon-14 and its associated services.
- Procurement and supply-chain leaders: implement a two-tier sourcing strategy. Use long-term offtake agreements with base-volume producers to de-risk supply, and negotiate capacity options or rolling contracts with specialist radiochemistry providers for premium-grade needs and GMP-labelling windows.
- R&D and clinical program heads: map your isotopic requirements by development phase and lock regulatory-ready supply lines early. Our report’s decision framework helps translate assay sensitivity and regulatory milestones into contract terms (lead time, quality attributes, and contingency clauses).
- Corporate development and investors: prioritize targets that offer vertical integration (feedstock plus GMP conversion) or unique, scalable production technology. Market concentration metrics indicate room for consolidation around players that can deliver validated, exportable volumes.
- Policy and compliance officers: prepare for more cross-border flows and associated regulatory scrutiny. Export-capable suppliers introduce geopolitical and compliance variables that must be incorporated into procurement governance and vendor risk assessments.
What the full PW Consulting report delivers to subscribers
This briefing intentionally omits the granular tables and numeric segment splits that many practitioners need for execution. The full Worldwide Carbon-14 Market report (base year 2025, historical 2020–2025, forecast 2026–2032) provides:
- Transaction-grade market sizing and scenario forecasts through 2032, with sensitivity runs that stress-test pricing and availability under alternate production-adoption curves.
- Region, product-type, and application segmentation with supplier-level capacity matrices — available only to clients to protect commercial utility.
- Detailed company profiles and benchmarking, including recent commercial milestones and technology assessments for new production routes.
- Procurement templates, contract language recommendations, and a supplier due-diligence checklist aligned to regulatory and quality frameworks.
- An M&A playbook and valuation yardsticks for investors assessing platform and bolt-on opportunities in production, enrichment, and contract radiochemistry services.
Closing perspective: use 2026 to lock value, not just volume
As the market matures, the strategic premium shifts from mere volume to assured quality, regulatory readiness, and integrated services. Companies that move in 2026 to structure supply agreements that capture priority access, traceability, and regulatory guarantees will convert isotopic availability into program certainty. Conversely, organizations that treat Carbon-14 like any other commodity risk delays and costly program contingencies.
PW Consulting’s full report arms decision-makers with the granular inputs required to operationalize these strategies — from precise vendor scorecards to contract templates and capital investment models. For organizations with time-sensitive development pipelines or for investors evaluating platform plays, this is a pivotal year to convert market insight into defensible contracts, partnerships, and investments.
For access to the full dataset, segmented modelling, and supplier appendices — including the proprietary scorecards we use for vendor selection and M&A screening — please consult the complete Worldwide Carbon-14 Market report or contact PW Consulting directly for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Carbon-14 Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com