

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Mechanical Transmission Azimuth Thruster Market Poised for 5.48% CAGR — Strategic Insights Released

Worldwide Mechanical Transmission Azimuth Thruster Market — Strategic Outlook for 2026 Decisions
As vessel owners, system integrators and component suppliers plan capex and commercial strategies for 2026, mechanical transmission azimuth thrusters are moving from a niche maneuvering technology to a core enabler of modern vessel performance. PW Consulting’s new market study — covering historical performance (2020–2025), a 2025 base year, and an actionable forecast (2026–2032) — equips executives with the quantitative backbone and playbooks required to convert propulsion trends into defendable investment choices.
Food Extruders Market
Market snapshot: size, growth and concentration
The global mechanical transmission azimuth thruster market demonstrates steady, resilient expansion. Our topline model shows growth from USD 425.4 million in 2020 to USD 554.76 million in 2025 (base year). Looking forward across the 2026–2032 forecast period, the market is projected to expand at a compound annual growth rate (CAGR) of 5.48%, reaching a materially larger installed-and-serviceable market by 2032. Market concentration is meaningful: the three largest suppliers account for a majority share (CR3 ≈ 54.3%), and the top five consolidate nearly seven in ten dollars of market value (CR5 ≈ 68.92%).
Worldwide Hemp Oil Market
These macro metrics signal two critical realities for 2026 decision-makers: incumbent manufacturers retain pricing power in core product lines, but the pace of fleet renewal, offshore project build-out and electric/hybrid adoption opens attractable niches for challengers and specialized aftermarket providers.
EtCO2 Sensor Market
Why 2026 is a strategic inflection year
- Offshore energy expansion (both hydrocarbons and offshore wind) is driving demand for higher-thrust, higher-reliability azimuth solutions that can operate under extreme duty cycles.
- Regulatory pressure — from emissions targets to noise and underwater radiated noise rules — is accelerating shipowner demand for propulsion systems that deliver better fuel efficiency and lower acoustic signatures.
- Fleet renewal and new-build programs for tugs, offshore support vessels and passenger ships are creating a steady replacement and retrofit runway for mechanical azimuth systems.
- Supply-chain realities for critical components (marine bearings, proprietary gearsets, seals) are influencing lead times and total cost of ownership; securing these inputs is now a competitive moat.
- Sensorization and condition monitoring are moving from optional add-ons to expected capabilities — suppliers that embed predictive diagnostics will capture higher aftermarket share.
What the report delivers — field-tested, executive-grade outputs
Our goal was not to produce another descriptive brochure, but to arm commercial and technical leaders with tools they can use in negotiations, portfolio planning and M&A screening. Key deliverables include:
- Proprietary market model (USD Million basis) with historical series and a scenario-enabled forecast (2026–2032) that allows users to stress-test demand drivers and price assumptions.
- Competitive scorecards for every active supplier, benchmarked on technology breadth, power range, in-house gearbox capability, global service footprint and aftermarket potential.
- Supply-chain heatmaps identifying concentration risks for bearings, gears and specialized metallurgy — plus mitigation playbooks for procurement teams.
- Retrofit and aftermarket opportunity maps by vessel archetype and installed base vintage, highlighting where service margins and lifetime revenue are highest.
- Technology roadmaps covering electrified/hybrid interfaces, retractable/retract-swing architectures, and sensor-integration paths that materially affect lifecycle economics.
- Commercial templates and negotiation checklists for OEMs, shipyards and owners approaching large-series procurements.
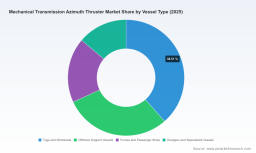
To maintain the “trailer” principle of this release, we present the strategic finding set and methodology here; detailed segment-level tables, regional breakdowns and vessel-type dollar splits are available exclusively through the full report and interactive model on our site.
Competitive landscape — capabilities, exposures and strategic moves
The competitive field combines experienced European and North American manufacturers with growing Asian capability. Leading manufacturers exhibit distinct strategic profiles:
- SCHOTTEL Group (Germany) remains a benchmark in Z-drive and rudderpropeller configurations, emphasizing maneuverability and integration with commercial and offshore designs.
- Thrustmaster of Texas brings a portfolio of heavy-duty mechanical and hydraulic thrusters across a broad power envelope, positioning itself for displacement-hull and offshore service markets.
- ZF Friedrichshafen leverages in-house gearbox production to deliver both L-drive and Z-drive options, competing strongly on integration and drivetrain assurance.
- Berg Propulsion and specialist European suppliers focus on customization and high-precision maneuverability, finding strength in complex retrofit and niche vessel segments.
- Twin Disc / Veth (Netherlands/USA) dominate retractable and swing-out specialties, an attractive play for operators seeking flexible docking and shallow-water capability.
- Asian manufacturers — notably NGC Marine — are building scale and engineering capability that makes them competitive on price-to-performance in regional builds.
- Other incumbents (Hydromaster, Brunvoll, Kawasaki, IHI, Pleuger and Cat-branded offerings) round out the field with positions ranging from retractable systems to very-high-power solutions for FPSOs and LNG-support vessels.
Recent sector developments underline shifting battlegrounds. Late-2025 product extensions from major propulsion groups (including larger propeller diameters and integrated condition monitoring) and contract awards for new tug series indicate that manufacturers are prioritizing higher-thrust platforms and digital health features. These moves will accelerate expectations across owners and yards in 2026.
Strategic implications and recommended actions for 2026
Decisions made in 2026 will determine competitiveness and margin capture across the next hardware refresh cycle. We recommend a focused set of actions for corporates and investors:
- Prioritize modular, scalable product platforms. Design investments that allow power and gearbox modules to be shared across L-drive and Z-drive variants to reduce time-to-market and simplify aftermarket spares management.
- Lock down critical inputs. Establish multi-year agreements for bearings and high-precision gearsets, or pursue vertical integration/strategic equity with key suppliers where defensible.
- Invest in sensorization and remote diagnostics. A minimal viable condition-monitoring suite is now a price-of-entry feature for large contracts; it also creates recurring aftermarket revenue.
- Build retrofit-as-a-service offers. Retrofit demand from fleet renewal and acoustic/regulatory upgrades is a high-margin channel; bundle installation, warranty and performance guarantees to shift owner CAPEX into predictable OPEX models.
- Screen M&A targets for gaps in power band, geography or digital capability. Consider tuck-ins that add retractable or very-high-power capabilities to broaden tender eligibility.
- Calibrate pricing and warranty exposure through scenario planning. Use the report’s model to stress-test price elasticity and failure-rate assumptions under alternative fuel and operational profiles.
Decision-support assets included with the report
- Interactive Excel market model and sensitivity dashboard (USD Million base)
- Top-20 supplier strategic scorecards with capability matrices
- Supplier risk heatmap and preferred-sourcing playbook
- Aftermarket revenue calculator and retrofit prioritization matrix
- Investor briefing slides and recommended M&A criterion checklist
Methodology and confidence
PW Consulting’s analysis synthesizes primary interviews with shipyards, owners, propulsion engineers and aftermarket service providers; detailed review of orderbooks and technical specifications; patent landscaping; and bottom-up installed-base modelling. We reconcile supply-side shipments with vessel-construction activity and service-cycle replacement rates to produce a market view grounded in both transactional and technical realities. While this release presents the high-confidence strategic findings and topline metrics, the full dataset (including regional and vessel-type allocations) is maintained in our interactive model to ensure clients can parameterize their own scenarios.
Conclusion — converting trend visibility into 2026 actions
For executives making 2026 decisions, the choice is straightforward: deferment of strategic investments risks ceding aftermarket and platform economics to better-prepared competitors; aggressive, but targeted, investments in modular product platforms, supply-chain security and digital health capabilities will pay back through higher tender win rates and recurring service revenues. The market is growing at a mid-single-digit CAGR and remains sufficiently concentrated that first-mover improvements in serviceability and diagnostics can materially change market positioning.
To review the detailed segment tables, regional allocations, vessel-type forecasts and the interactive financial model that underpin these recommendations, access the full report and data portal via the PW Consulting publication page. Our team is also available for tailored workshops to translate the findings into procurement strategies, R&D roadmaps or M&A diligence.
For detailed analysis of this topic, please visit the official page: Worldwide Mechanical Transmission Azimuth Thruster Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com