

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Gas‑Insulated Transformers Market to Grow from USD 2,140.5 Million in 2025 to USD 3,272.0 Million by 2032 at a 6.25% CAGR

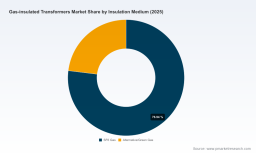
Worldwide Gas-Insulated Transformers Market: Strategic Imperatives for 2026
Executive snapshot
As utilities, equipment OEMs, investors and policymakers prepare multi-year capital and technology roadmaps, PW Consulting’s latest Worldwide Gas-Insulated Transformers (GIT) Market report delivers the market-level intelligence and executable playbooks required to convert uncertainty into a series of high-confidence decisions for 2026 and beyond. The sector is recovering from a period of accelerated investment and supply-chain adjustment: our base-year analysis (2025) and forward-looking model (2026–2032) embed a 6.25% compound annual growth rate (CAGR), reflecting steady demand as grids densify, urbanize and decarbonize. This release is designed as a strategic trailer—demonstrating the analytical depth and operational utility of the full study while intentionally reserving detailed segment tables and granular vendor metrics for the full report.
Hydropower Distributed Control Systems Market
What the macro numbers imply for strategy
Readers should treat the headline figures as directional guardrails. The GIT market in 2025 stands at an institutional scale that justifies strategic portfolio decisions—new capacity investments, supplier consolidation, and technology pivoting—rather than opportunistic one-off purchases. A mid-single-digit CAGR through the forecast horizon supports a cautious growth posture: expect robust upgrade cycles in mature grids, accelerated deployments in urban and constrained right-of-way environments, and pockets of above-average expansion where interconnection and renewables integration drive transmission upgrades.
Worldwide Blogger Outreach Software Market
-
Capital planning: the combination of steady market growth and concentrated vendor capacity means that multi-year procurement timelines (24–36 months) and early supplier engagement will materially reduce delivery and integration risk.
Mobile Emergency Power Systems Market -
Technology transition: the economic case for SF6 alternatives is maturing. Buyers will balance lifecycle cost against regulatory exposure and reputational risk—particularly in jurisdictions tightening GHG reporting.
-
M&A and partnerships: a market with clear leaders and meaningful mid-tier specialization creates fertile ground for bolt-on acquisitions, strategic alliances and capacity-sharing agreements focused on niche applications (e.g., ultra-compact urban GIS substations).
Report contents — actionable, not academic
This report was developed explicitly for practitioners who must convert insight into executable plans. Key deliverables include:
-
Methodology appendix and scenario models — deterministic base case plus two stress scenarios that isolate commodity shocks, accelerated regulatory tightening and rapid adoption of SF6 alternatives.
-
Comprehensive supply-chain map — from specialty gas sourcing and pressboard materials to high-volume winding facilities and test-lab bottlenecks; includes lead-time sensitivity matrices and alternative sourcing playbooks.
-
Procurement playbook — RFP templates, total-cost-of-ownership calculators, service-level benchmarks and contractual clauses to manage SF6 leakage liability and end-of-life obligations.
-
Technology and product roadmaps — maturity curves for compact GIS designs, SF6-free insulation media, digitization-enabled monitoring and predictive maintenance enablers.
-
Vendor scorecards and comparative heatmaps — qualitative and quantitative criteria across reliability, delivery footprint, service network, R&D pipeline and price-to-performance (reserved for the full report).
-
Regulatory impact analysis and compliance playbooks — practical steps to quantify the financial and operational implications of updated GHG reporting rules and likely next-wave restrictions.
-
Risk & opportunity matrix for investors — prioritizes segments, technologies and geographic exposure for 12–36 month hold horizons.
Competitive landscape — who matters and why
The market’s supply side exhibits mid-to-high concentration: the top three players account for a dominant share of industry revenues, and the top five intensify that concentration. That structure produces two strategic realities: scale players set technical and contractual standards, while specialist and regional players capture differentiation through customization, urban deployments and service excellence.
-
Hitachi Energy (Zurich) : Competes on integrated grid solutions and manufacturing scale. Their emphasis on compact design and transmission integration makes them a preferred partner for utilities seeking turnkey substation modernization.
-
Siemens Energy (Munich) : Positioned around high-efficiency, high-voltage equipment with deep utility relationships. Their strength is portfolio breadth and lifecycle service capabilities.
-
GE Vernova — Grid Solutions (Cambridge, MA) : Focuses on reliability and grid resilience for high-demand sectors. GE’s global service network and system-level competence are differentiators in mission-critical projects.
-
Mitsubishi Electric (Tokyo) : A leader in high-performance systems and in engineering SF6-free alternatives; appeals to customers prioritizing sustainability transitions.
-
Toshiba Energy Systems & Solutions (Tokyo) : Demonstrated capability in dense urban projects—recent commissioning of multiple GIT units in high-safety, non‑flammable configurations for large urban substations underscores their niche expertise.
-
Hyundai Electric, Hyosung, Fuji Electric, Arteche, Meidensha and others : These suppliers occupy critical roles in regional markets and specialized product segments (measurement transformers, modular compact units, or service-heavy local deployments).
For 2026 procurement cycles, buyers should use a two-track supplier strategy: engage a tier-one global OEM for system-critical equipment and a regional specialist for customization, installation, and lifecycle support. Investors should monitor consolidation signals among mid-tier suppliers—these are the most likely sources of value-accretive M&A.
Regulatory and raw-material dynamics that will shape 2026 choices
-
GHG reporting and regulatory risk: Recent updates to major GHG reporting regimes have shifted liability vectors. Where reporting thresholds moved from nameplate capacity to emissions volumes, asset-owning utilities must now model and disclose SF6 emissions exposure as part of capital approvals. This materially affects lifecycle-cost calculations and supplier selection criteria.
-
SF6 market economics: Industrial-grade SF6 exhibits price volatility influenced by supply tightness and regulatory scrutiny. Market data indicate a multi-dollar-per-kilogram band for industrial SF6, with power-sector averages often used in TCO models. Procurement teams must include commodity hedging and alternative-gas trials in supplier negotiations.
-
Emission footprints: The electrical transmission and distribution sector historically accounts for a significant share of SF6 emissions in large markets. This creates both regulatory pressure and reputational incentives for early adoption of low‑GWP alternatives and advanced leakage-detection systems.
Practical recommendations for 2026 decision-makers
-
For utilities and T&D asset owners: Incorporate SF6 emission scenarios into capital approvals. Prioritize purchases that reduce system-level lifecycle risk (including leakage, end-of-life disposal and regulatory compliance). Start pilot programs for SF6-free units in low-risk sites to build operational data ahead of large-scale replacement decisions.
-
For OEMs: Accelerate validation of SF6 alternatives and modularization strategies. Invest in factory automation and shared test facilities to shorten lead times. Consider strategic partnerships to fill regional service gaps and bid more competitively on turnkey urban projects.
-
For investors and private equity: Target mid-tier specialists with strong service footprints and differentiated product IP for buy-and-build strategies. Monitor regulatory timelines: accelerated rules create asset-stranding risk but also premium pricing opportunities for compliant suppliers.
-
For EPCs and integrators: Standardize interfaces and interoperability clauses with equipment vendors. Offer bundled performance guarantees that capture both installation quality and operational leakage mitigation to distinguish bids.
-
For policymakers and regulators: Provide clear multi-year transition guidance that aligns reporting, end-of-life disposal and product standards to avoid creating stranded inventories or supply shocks.
Where the tailwinds and headwinds will be most felt
Expect tailwinds from urbanization, grid reinforcement for renewables integration, and the need for compact substation solutions. Headwinds will be driven by commodity-price shocks, stricter GHG regulation and the time-lag for certification of SF6 alternatives at the highest voltage classes. The full report quantifies sensitivity of market growth to each of these factors and provides contingency matrices for capital planners.
Concluding note — why this matters for 2026
2026 will be a pivotal year in which organizations must convert strategic intent into tangible procurement, R&D and partnership commitments. With a mid-single-digit growth trajectory and a marketplace dominated by a handful of global leaders plus specialized regional incumbents, the strategic margin will accrue to those who integrate regulatory foresight, commodity risk management and supplier flexibility into their decisions now. PW Consulting’s Worldwide Gas‑Insulated Transformers Market report provides the scenario tools, supplier diagnostics and contractual playbooks needed to de‑risk those decisions—while the detailed segment tables, vendor scoring and project-level benchmarks are reserved for the full report to ensure clients can operationalize these insights immediately.
Next steps
To access the full dataset, regional and application breakdowns, detailed vendor scorecards and the downloadable procurement playbook, request the full report and supporting models from PW Consulting. The full package converts the strategic overview in this release into the tactical artifacts your procurement, engineering and investment teams need for 2026 readiness.
For detailed analysis of this topic, please visit the official page: Worldwide Gas-insulated Transformers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com