

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Worldwide Passenger Vehicle Window Regulator Mechanism Market to Expand at a 5.71% CAGR During 2026–2032

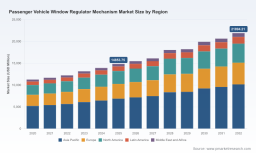
Worldwide Passenger Vehicle Window Regulator Mechanism Market — Strategic Insights for 2026
Executive preview from PW Consulting
As OEMs pursue lighter, safer and smarter vehicle interiors, the global passenger vehicle window regulator mechanism market is entering a phase of steady expansion and structural change. PW Consulting’s latest market study — built on a 2020–2025 historical base (base year 2025) and forward-looking to 2032 — quantifies that momentum: the global market size reached approximately USD 14,853.75 Million in 2025 and, under our central forecast, grows at a compound annual growth rate (CAGR) of 5.71% across the 2026–2032 horizon, reaching an expected USD 21,894.21 Million by 2032. For strategy teams preparing capital allocation, product roadmaps or supplier negotiations in 2026, these topline trajectories provide an essential starting point.
Educational Inverted Microscopes Market
Why this market will matter to your 2026 decisions
-
Regulatory inflection: Mandatory safety features such as anti-pinch and one-touch operation are now baseline requirements in major markets, changing feature portfolios and electronic control requirements for regulators.
Standalone Photovoltaic Water Pump System Market -
Weight and efficiency pressures: The drive to reduce vehicle curb weight is accelerating substitution of traditional steel with aluminum and engineering plastics in regulator designs — a factor that affects sourcing, production engineering and unit cost over time.
LV DB Board Market -
Systems integration: Increasing adoption of fully integrated door modules (regulators + motors + wiring + electronics) simplifies OEM assembly but shifts value-capture toward suppliers capable of modular delivery and cross-system engineering.
-
Aftermarket and low-volume channels: While OEM volumes remain the primary growth engine, aftermarket dynamics and low-volume bespoke suppliers create niche opportunities and pricing volatility that matter for inventory and service network planning.
What the PW Consulting report delivers (practical, decision-grade content)
-
Comprehensive market sizing and trend matrices — historical (2020–2025) and forecast (2026–2032) scenarios with sensitivity runs tied to material costs, regulatory timelines and EV penetration.
-
Mechanism-agnostic technology dossier — comparative assessment of dual-rail, single-rail, scissor and manual architectures with engineering trade-offs, weight profiles and cost drivers (note: full segmentation datasets and model-level tables are available in the full report).
-
Supplier heatmaps and capability scorecards — engineered to support make-versus-buy decisions, supplier consolidation plans and Tier-1/Tier-2 partner selection based on module integration capability, manufacturing footprint and product roadmap alignment.
-
Raw material and cost-sensitivity models — scenario tools that quantify the impact of steel, aluminum and engineering plastic price swings on supplier margins and OEM procurement budgets.
-
Regulation-to-product playbooks — implementation checklists for anti-pinch compliance, software calibration, EMC and functional safety validation to accelerate homologation timelines.
-
M&A and partnership frameworks — prioritized targets and valuation comparators for corporates seeking inorganic scale or new technology access, including playbooks for integrating mechatronic teams.
Strategic implications for 2026
-
Product strategy — Prioritize modularity and electrification-ready architectures. Window regulator product lines that are designed for rapid integration with body electronics and door modules will capture a growing share of OEM specification cycles.
-
Sourcing and procurement — Use the report’s raw-material sensitivity outputs to design hedging strategies and index-linked contracts. Suppliers with in-house molding or light-weighting expertise offer negotiation leverage when material prices trend upward.
-
Manufacturing footprint — Re-evaluate proximity to final-assembly locations and the feasibility of regional module production. The cost-benefit calculus for local content will shift as transport costs, tariffs and lead-time risk are re-priced post-pandemic.
-
Aftermarket and low-volume opportunities — Define separate product and pricing strategies for aftermarket SKUs and low-volume OEMs; specialized manufacturers and remanufacturers remain a flexible route to retain share where large Tier-1s deprioritize low-volume work.
-
M&A and partnerships — Target acquisitions or minority stakes in firms that offer complementary mechatronics, software or lightweight materials expertise to accelerate time-to-market for integrated door solutions.
Competitive landscape — high-level takeaways
The supplier base remains moderately concentrated: our concentration metrics indicate a CR3 of approximately 42.15% and a CR5 of approximately 58.4%, pointing to a market where global leaders coexist with numerous specialist and regional players. Key strategic archetypes observed across the competitive set include full-scope system integrators, high-volume cost-optimized producers, and nimble, engineering-focused specialists.
-
Full-scope integrators (e.g., Brose Fahrzeugteile, Magna Closures, Valeo): Compete on module-level integration, software-enabled comfort functions and the ability to supply complete door sub-systems. Recent product launches and trade show demonstrations underscore a race to embed intelligent features and modular architectures early in OEM programs.
-
High-volume specialists (e.g., HI-LEX, Aisin): Leverage scale manufacturing and in-house component molding to sustain cost leadership in core power-regulator lines for mainstream vehicle programs.
-
Electronics and motor system suppliers (e.g., Robert Bosch, Denso): Bring depth in motor design and electronic controls — critical as regulators move from purely mechanical systems to software-assisted safety and personalization functions.
-
Mid-tier and niche players (e.g., Grupo Antolin, Shiroki, MarchantCain, Politecnica 80, Han Yale): Serve differentiated needs such as lightweight interiors, low-volume bespoke programs and aftermarket coverage, often with high engineering agility or broad SKU portfolios.
Notable recent developments that shape competitive dynamics include Brose’s rollout of an intelligent window regulator in China (2024) and its showcase of modular door solutions at Auto Shanghai 2025 — both signal investment in feature-rich, software-capable product lines aimed at global OEMs.
Risk vectors and scenario planning
-
Raw material volatility — Steel, aluminum and plastics pricing remains the most immediate margin risk. Our scenario suite models upside and downside cases to help procurement teams quantify budgetary impact.
-
Regulatory tightening — Stricter safety or EMC requirements in key markets can accelerate redesign cycles and increase validation costs for legacy platforms.
-
Technology substitution — As vehicle architectures evolve (e.g., increased modularization, new door electronics architectures), incumbents that cannot embed software and diagnostics risk margin erosion.
-
Supply-chain concentration — Bottlenecks in specialized components (motors, precision cables, molded plastics) create single-point risks; diversification and second-source strategies should be stress-tested.
How to apply this study in 2026
-
Board and investment committees: Use the topline market trajectory and concentration metrics to stress-test capacity investments and to prioritize inorganic growth opportunities.
-
Product and engineering teams: Leverage the technology dossiers and trade-off matrices to define modular product roadmaps aligned with compliance windows and OEM platform schedules.
-
Procurement and supply-chain managers: Apply the cost-sensitivity and scenario outputs to renegotiate supplier contracts, design hedging instruments and set regional sourcing strategies.
-
Corporate development teams: Use the supplier heatmaps and capability scorecards for target screening and integration planning, focusing on complementary capabilities rather than incremental capacity.
Conclusion — what to do next
For teams making decisions in 2026, the window regulator market presents both steady growth and decisive inflection points driven by safety regulation, materials transition and modular integration. PW Consulting’s report delivers the empirical foundation and practical tools you need to convert market projections into executable plans — from prioritizing R&D features and securing resilient supply chains to identifying acquisition targets and structuring supplier alliances. To access the full suite of datasets, interactive models and supplier scorecards that underpin these insights, please consult the complete report on PW Consulting’s research portal.
For detailed analysis of this topic, please visit the official page: Worldwide Passenger Vehicle Window Regulator Mechanism Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com