

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Cilnidipine API Market Report — Asia Pacific Commands Nearly 49% Share, Driving Global Growth

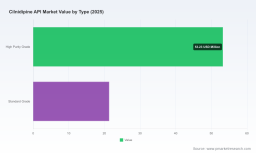
Worldwide Cilnidipine API Market — Strategic Insights for 2026 Decision-Makers
PW Consulting’s new market study on the Worldwide Cilnidipine API market provides a focused, decision-ready intelligence package for executives, investors, and procurement leaders planning for 2026 and beyond. The market has demonstrated steady expansion from 2020 through our 2025 base year, and our forecast shows continued growth through 2032 with a compound annual growth rate (CAGR) of 5.28% for the 2026–2032 horizon. Against this backdrop, the report transforms raw industry data into executable strategy: where to allocate capital, how to structure supplier relationships, and which regulatory and manufacturing levers matter most to preserve margin and guarantee supply.
Worldwide Accounts Payable & Accounts Receivable Software Market
Market Trajectory at a Glance
Measured from our historical coverage (2020–2025) and extended through a scenario-driven forecast to 2032, Cilnidipine API demand evolution underscores a resilient specialty API market. The 2025 market base provides the anchor for 2026 planning, and the forecast path to 2032 quantifies the investment envelope and expected returns for capacity, quality upgrades, and value-chain integration. PW Consulting’s modelling combines demand-side drivers (therapeutic adoption, formulary shifts, geographic demand patterns) with supply-side constraints (raw material availability, regulatory lead times, manufacturing scale) to produce a risk-adjusted view that executives can operationalize in budget cycles starting 2026.
Maintenance Platform for Wind Turbines Market
Why 2026 Is a Turning Point
-
Regulatory and IP context: Cilnidipine’s clinical lifecycle and generic entry dynamics continue to shape supplier economics. The substance has a long clinical history in several markets; composition-of-matter exclusivities that once constrained supply in key jurisdictions have lapsed, enabling broader generic API manufacturing and export activity. This creates room for new suppliers but increases the need for differentiation via quality certification and regulatory dossiers.
Double Beam UV-VIS Spectrophotometers Market -
Supply-chain topology: Synthesis pathways for Cilnidipine depend on 1,4-dihydropyridine intermediates that today are predominantly sourced from established chemical producers in Asia. That concentration of upstream inputs introduces volatility risk — both price and availability — that directly feed into API lead times and gross margins.
-
Trade and manufacturing flows: Recent export activity from major API hubs demonstrates existing global distribution channels and the feasibility of scaling exports, but also underscores exposure to regional regulatory and logistics shocks that procurement teams must hedge against.
What the Report Contains — Practical, Transaction-Ready Tools
PW Consulting’s report was designed as a toolkit, not a catalogue. It contains:
-
Market sizing and validated historical time series (2020–2025) and a granular, scenario-based forecast (2026–2032) including upside/downside cases tied to regulatory timelines and raw-material scenarios.
-
Supply-chain maps that identify critical intermediates, single-source nodes, and a supplier risk matrix with mitigation playbooks (dual-sourcing, toll-manufacturing, and carry-stock strategies).
-
Regulatory intelligence dossiers: dossier status trackers, jurisdictional filing templates, and timelines for common regulatory filings and certificates that buyers and developers must budget for.
-
An actionable supplier scorecard with due-diligence checklists covering certifications, DMF/EDMF/CEP status, capacity utilization, quality incident history, and financial health indicators.
-
Manufacturing economics and pricing model templates (cost-of-goods breakdowns, sensitivity to intermediate pricing, CAPEX payback profiles) that let teams stress-test investments and contract frameworks.
-
M&A and commercial playbooks: prioritization matrices for buy-versus-build decisions, integration checklists, and a shortlist of deal structures that accelerate market entry while capping downside.
-
Executive-ready briefing slides and scenario dashboards to support board-level decision-making and procurement negotiation strategy.
Key Strategic Themes from the Analysis
-
Steady growth, strategic selectivity: The market’s steady CAGR signals that incremental capacity can be absorbed, but returns vary sharply by quality tier and regulatory reach. High-purity production and vendors with established regulatory footprints capture differential pricing and long-term contracts.
-
Concentration creates opportunity: Market concentration metrics show a meaningful share controlled by a small group of suppliers. That concentration creates opportunities for new entrants via niche differentiation (higher purity, shorter lead times, or captive intermediates), and for incumbents to lock in revenues through long-term supply agreements.
-
Raw-material dependency is the principal margin lever: The availability and pricing of 1,4-dihydropyridine intermediates are leading indicators for margin compression or expansion. Securing intermediate supply or investing in upstream capability is often more value-accretive than marginal downstream capacity increases.
-
Regulatory-first strategies win: Suppliers that pair quality certifications with active dossier maintenance and multi-jurisdictional filings secure premium placement in procurement decisions for regulated markets.
Competitive Landscape — Profiles and Strategic Implications
Our competitive analysis profiles the principal suppliers whose activities shape global supply dynamics. For 2026 planning, procurement and BD teams should evaluate these participants against five pragmatic axes: certification coverage, filing depth (DMF/EDMF/CEP), scale and utilisation, geographic supply risk, and portfolio fit for downstream formulations.
-
MSN Laboratories (Hyderabad, India) — A vertically integrated manufacturer with multiple dossier certifications. MSN’s regulatory credentials and filings underpin its global supply role and make it a candidate for supply partnerships and contract manufacturing agreements. URL: https://www.msnlabs.com/
-
Bal Pharma Limited (Bengaluru, India) — Focused on cardiovascular APIs with export-oriented regulatory filings. Bal Pharma is positioned for markets that prioritize competitive pricing but require regulatory traceability. URL: https://balpharma.com/
-
Fujimoto Pharmaceutical Corporation (Toyama, Japan) — Developer/supplier originating from a market with a long clinical track record for Cilnidipine. Fujimoto’s position is important for partnerships targeting quality-sensitive, regulated markets and for leveraging legacy clinical relationships. URL: https://www.fujimoto-pharm.co.jp/
-
Hetero Drugs (Hyderabad, India) — Part of a broad cardiovascular API portfolio with multiple regulatory filings. Hetero’s scale and filing depth make it a credible strategic supplier for large-volume contracts and for companies looking to diversify supplier bases. URL: https://hetero.com/
Each of these players exhibits different strategic strengths: Indian suppliers generally offer scale and cost advantages, while Japanese incumbents bring reputational advantage and regulatory trust in certain developed markets. Our report provides comparative scorecards that enable buyers to prioritize suppliers against their own risk tolerance and commercial objectives.
Supply-Chain Resilience and Raw-Material Risk
One of the report’s core practical takeaways is a resilience framework for the Cilnidipine API value chain. The synthesis pathway leans heavily on specific intermediates primarily produced in select Asian chemical hubs. This structural reliance means that a short-term disruption or input-price spike can propagate rapidly through the supply chain. Our recommended mitigations for 2026 include dual-sourced contracts, selective upstream investment (strategic partnerships or minority equity stakes in intermediate producers), and staggered inventory models calibrated against lead-time variability.
Investment and M&A Playbook for 2026
Given the market’s growth profile and concentration, PW Consulting recommends a staged approach to capital deployment:
-
Short-term (0–12 months): secure supply through long-term offtake agreements with suppliers that have robust regulatory coverage; incorporate price-indexed clauses tied to key intermediate inputs.
-
Medium-term (12–36 months): pursue bolt-on acquisitions that add high-purity manufacturing capability or strategic intermediate supply, or execute JVs that underwrite feedstock security.
-
Long-term (36+ months): consider greenfield investments in flexible multi-purpose capacity where a company’s portfolio exposure justifies vertical integration to capture margin and quality controls.
Each pathway is accompanied in the report by a quantified decision gate framework, CAPEX sensitivity analyses, and sample term-sheets that reflect market realities derived from our forecast modelling.
How to Use This Report in 2026 Planning Cycles
-
Procurement teams: use the supplier scorecards and cost models to renegotiate pricing and to design resilient S&OP plans that reflect raw-material sensitivities.
-
Business development: prioritize market entries and licensing deals where regulatory dossiers and distribution reach produce an immediate competitive advantage.
-
R&D and formulation leads: align API quality-tier investment with downstream formulation strategies (e.g., high-purity APIs for fixed-dose combinations or premium markets).
-
Corporate strategy and M&A: apply the M&A prioritization grid and valuation multipliers in the report to identify accretive targets and avoid common integration pitfalls.
Closing — Where to Find the Full Dataset and Models
PW Consulting’s Worldwide Cilnidipine API Market report is deliberately designed as a “trailer”: we provide clear strategic direction, validated macro sizing, scenario models, and practical playbooks while reserving the full segmented datasets, supplier-level revenue splits, and downloadable financial models for the full report package. Executives and teams preparing 2026 budgets and go-to-market plans should review the complete dataset to access the granular regional, grade, and application breakdowns that drive procurement and investment decisions. For the comprehensive datasets, interactive dashboards, and downloadable models, please visit the PW Consulting report page to access the full publication.
Prepared by PW Consulting — Senior Strategic Advisory Group and Chief Industry Analysis. For media, investor, or client access to executive briefings and the full model pack, contact PW Consulting’s research desk.
For detailed analysis of this topic, please visit the official page: Worldwide Cilnidipine API Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com