

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
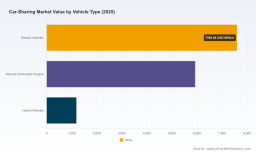
PW Consulting: Worldwide Car-Sharing Market to More Than Double from USD 14.72B in 2025 to USD 35.61B by 2032 at a 13.45% CAGR — EV Segment Tops USD 7.60B

Worldwide Car‑Sharing Market 2026: Strategic Imperatives from PW Consulting
PW Consulting's new Worldwide Car‑Sharing Market report (base year 2025; forecast 2026–2032) synthesizes five years of historical performance with a proprietary forecasting engine to deliver an actionable playbook for 2026 decision‑makers. The global car‑sharing industry has matured into a multi‑billion dollar marketplace—expanding from roughly USD 7,520 million in 2020 to USD 14,721 million in 2025—and our model projects continued rapid expansion through the forecast window at a compound annual growth rate of 13.45%, reaching north of USD 35,600 million by 2032. This press release outlines the report’s strategic value while preserving the deeper, segment‑level intelligence that subscribers will find in the full study.
New Energy Box-type Substation Transformer Market
What the report delivers: practical, board‑level intelligence
- Proven forecasting framework: a scenario‑based model calibrated to observed demand elasticities, fleet economics and telematics-driven utilization metrics for 2026–2032.
- Operator playbooks: step‑by‑step guides for station‑based, free‑floating and peer‑to‑peer (P2P) models—covering fleet deployment, pricing architectures, membership funnels and KPIs that move the needle on utilization and yield.
- Connectivity & technology stack analysis: vendor shortlists, integration checklists and upgrade roadmaps to address critical network and telematics risks emerging in 2026.
- Regulatory scenario planning: three regulatory shockcases (accelerated emissions mandates, rollback of green standards, and connectivity compliance) with quantified impacts on unit economics and fleet replacement schedules.
- M&A & partnership playbook: commercial and technical due diligence templates, valuation sensitivities tied to utilization uplifts, and a prioritized list of inorganic targets by strategic rationale.
- Investor & corporate procurement guidance: capex/opex budgeting templates, break‑even curves for electrified fleets, and a procurement scorecard to evaluate OEM mobility offers and fleet‑as‑a‑service propositions.
Macro trends shaping strategic choices in 2026
- Rapid revenue expansion and investor interest. The global market more than doubled over 2020–2025; the trajectory through 2032 implies continued capital inflows and strategic competition across price, convenience and fleet composition.
- Electrification is an operational and financial inflection point. Operators are balancing higher upfront vehicle costs and charging infrastructure against lower fueling/maintenance spend and regulatory incentives. The report presents a modular TCO tool to evaluate electrification timelines under varying electricity price and dwell‑time assumptions.
- Connectivity is now core infrastructure. With many markets shutting down 2G/3G during 2026, telematics and keyless‑access systems have become single points of failure or differentiation. Our vendor assessments and retrofit cost curves quantify the investment required to secure uninterrupted operations.
- Regulation has bifurcated the competitive battlefield. Recent policy moves—ranging from regulatory easing in some jurisdictions to abrupt reversals in emissions frameworks in others—introduce asymmetric market risk. We provide playbooks for rapid redeployment and compliance hedging.
- Fleet scale and utilization dynamics. Industry projections indicate substantial growth in shared fleet size and membership over the coming five years; operators that crack utilization optimization will capture outsized margin expansion.
Competitive landscape: how today’s leaders are positioning for 2026
The market exhibits moderate concentration: the top three players account for a meaningful share of revenue and capacity, and the top five hold an even larger footprint—conditions that favor both scale advantages and targeted niche plays. PW Consulting’s competitive matrix evaluates incumbents on five axes: network density, model mix (station vs free‑floating vs P2P), fleet electrification commitments, integration with broader mobility ecosystems, and technology capability.
Worldwide Nutrition Analysis Software Market
- Legacy fleet and network operators (Zipcar, Enterprise CarShare, Times Car): These players leverage established customer bases and rental networks. Their strategic risk is legacy cost structure and the need to pivot rapidly towards electrification and keyless, connected workflows. Operational playbooks in the report address retrofit economics and member‑retention levers.
- P2P platforms (Turo, Getaround): P2P models continue to expand by harnessing underutilized private assets. Our analysis highlights insurance product evolution and technology‑assisted onboarding as the determinants of sustainable unit economics for P2P operators.
- OEM and captive mobility brands (Free2Move, Kinto Share): OEM‑affiliated platforms are using balance‑sheet advantages and manufacturing synergies to pilot subscription hybrids and OEM‑backed leasing models; the report’s procurement scorecard helps buyers compare OEM propositions versus third‑party fleet offers.
- Regional champions and cooperatives (MILES Mobility, Mobility Carsharing, Communauto, SOCAR, Zoomcar, GoGet): Regional leaders exploit local regulatory relationships and modal integration. The research explores replication risks and the cost of scaling across heterogeneous regulatory and connectivity environments.
- Platform and tech enablers: specialized telematics/software companies have become indispensable partners for operations, from keyless entry to utilization analytics. Our vendor scoring and integration cost curves identify which suppliers reduce operational risk most efficiently under 2026 constraints.
Recent developments that change the playbook
- Strategic tie‑ups and new mobility vectors: The reported 2026 alliances between large rental companies and ride‑hailing/autonomous projects signal a diversification of fleet services beyond traditional hourly/daily sharing—creating options for hybrid robotaxi and driver‑led revenues.
- Operational contraction and market re‑balancing: High cost environments and hyperlocal charges have forced some established services to withdraw from select markets, revising the competitive map and opening localized arbitrage opportunities for agile entrants.
- Connectivity and telematics mandates: Network upgrades driven by cellular shutdowns are creating a non‑negotiable capital requirement for many operators; our capital planning templates illustrate how to amortize these retrofits without disrupting utilization targets.
Five strategic actions for 2026 decision‑makers
- Prioritize connectivity resilience. Treat telematics and keyless systems as mission‑critical infrastructure—implement staged upgrades, diversified SIM/MCU strategies and redundant authentication paths to mitigate 2G/3G decommissions.
- Run electrification pilots with a modular rollout. Use our TCO and break‑even dashboards to sequence charging infrastructure investment in high‑utilization corridors first, then expand as utilization and energy procurement improve.
- Reconcile model mix to local economics. Maintain flexibility between station‑based, free‑floating and P2P offers. The full report includes a decision tree to select the optimal mix given urban density, parking economics and regulatory constraints.
- Hedge regulatory shock risk. Build contingency plans for abrupt policy swings—especially those affecting emissions and vehicle standards—by retaining a portion of the fleet with flexible exit options and aligning supplier contracts to short‑term fleet adjustments.
- Use M&A and partnerships to accelerate capability. Prioritize targets that add technology stack control, high‑utilization fleets, or strategic city footprints. Our due diligence templates quantify synergies tied to utilization improvements and cross‑sell potential.
Why PW Consulting’s report matters for investment and corporate strategy in 2026
Our report combines rigorous macro modelling (showing a sustained high‑teens to mid‑teens CAGR at the revenue level through 2032 under central scenarios) with operational playbooks and vendor analyses designed for immediate execution. It is not a directory of vanity metrics; it is a working guide for CFOs allocating fleet capex, CPOs choosing telematics partners, and corporate strategists evaluating M&A or partnership routes.
Thyristor Power Supply Market
We intentionally present this release as a strategic trailer: enough depth to validate our methodology and directional findings, but withholding the granular segment and regional tables that underpin site‑level deployment and transaction valuations. Subscribers to the full report receive detailed matrices, city‑level demand heatmaps, supplier TCO curves, and downloadable scenario models ready for boardroom stress‑testing.
Next steps
- Executive download: PW Consulting’s full Worldwide Car‑Sharing Market report includes the model files, playbooks and vendor shortlists referenced here.
- Custom advisory: For bespoke analysis—city rollouts, M&A screening, or procurement optimization—our consulting practice offers tailored workshops that translate the report’s insights into executable 90‑day plans.
In a rapidly evolving mobility landscape, 2026 will be a year where decisions about connectivity investment, electrification timing, and partnership structures determine who captures the next wave of growth. PW Consulting’s Worldwide Car‑Sharing Market report equips leaders with the foresight and operational detail to act decisively—without having to reinvent the model on their own.
For detailed analysis of this topic, please visit the official page: Worldwide Car-Sharing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com