

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Worldwide Meat Membrane Skinner Market to Expand at a 4.85% CAGR Through 2032

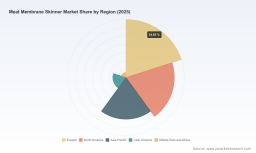
PW Consulting Releases Strategic Preview: Worldwide Meat Membrane Skinner Market Report (Base Year 2025) — Essential Insights for 2026 Decision-Makers
PW Consulting today publishes a strategic preview of our forthcoming Worldwide Meat Membrane Skinner Market report, designed to equip senior executives, procurement leads, and plant operations managers with the contextual intelligence required to make high-confidence capital and operational decisions in 2026. Drawing on a consistent historical series (2020–2025) and a rigorous forecast through 2032, this analysis synthesizes market-sizing, competitive dynamics, technology trajectories, and actionable playbooks — while intentionally withholding proprietary segment-level tables to encourage direct access to the full report for transaction-critical data.
Solar Panel Recycling Management Market
Why this report matters in 2026
Meat membrane skinners are a compact yet strategically important node in high-yield meat processing lines. Our model traces an industry that moved from USD 418.4 Million in 2020 to USD 532.5 Million in 2025, and we project continued expansion into the forecast window. The report’s forecast period (2026–2032) is built around a compound annual growth rate (CAGR) of 4.85%, reflecting steady demand driven by automation, yield optimization, and regulatory hygiene requirements.
Drone Inspection System Market
For executives planning 2026 capex cycles, the immediate value of this report is threefold:
Acoustic Magnetic Electronic Article Surveillance (EAS) System Market
- Benchmarking: independent, consistently modeled topline market sizing and concentration metrics that validate supplier selection and investment scale;
- Readiness: scenario-driven guidance on timing equipment replacement, retrofits, and line integrations to minimize downtime and capture margin uplift from yield gains; and
- Risk control: vendor assessment tools and supplier scorecards that translate product claims (e.g., “high-yield” or “easy-clean”) into measurable operational KPIs for procurement contracts.
What the preview reveals — and what is intentionally reserved
We present high-level market movement and structural dynamics so decision-makers understand direction and urgency. The topline progression above and the report’s market concentration indicators (CR3: 42.15%; CR5: 58.4%) are disclosed to signal that the industry is moderately consolidated: a handful of specialist OEMs maintain leading shares while a competitive long tail of regional and OEM players remains active.
However, to support our “trailer” principle — demonstrating analytical depth while preserving the proprietary granularity that underpins procurement and M&A decisions — the publication does not reproduce detailed regional splits, application-by-application revenue lines, or the full numeric breakdown by product type. Those segment-level tables, supplier scorecards, and bottom-up unit economics are made available exclusively through the complete report and data package.
Practical contents of the full report (operational focus)
Clients purchasing the comprehensive report can expect tools and frameworks oriented to execution, not just description. Highlights include:
- Market model: a transparent, auditable model covering historical demand drivers (2020–2025), unit shipments, ASP trends, and a 2026–2032 forecast consistent with a 4.85% CAGR;
- Procurement playbook: an RFP template, CAPEX vs. OPEX comparison matrices, lifecycle cost calculators and spare-parts planning templates to reduce downtime exposure;
- Technology ROI workbooks: fast-payback scenarios for automatic membrane skinners versus manual/semi-automatic approaches, sensitivity to labour cost inflation, and yield improvement thresholds;
- Site-integration guidance: engineering checklists for integrating skinners into existing processing lines, sanitation validation plans, and CIP (clean-in-place) design considerations;
- Vendor due diligence kit: supplier scorecards, warranty benchmarking, service-level KPIs, and contract negotiation guidance for spare parts and training;
- Case studies and pilot frameworks: verified before/after yield analyses and a step-by-step pilot protocol for cold-line testing;
- Regulatory and materials guidance: interpretation of food-safety standards and material requirements — especially stainless-steel hygiene and cleanability metrics — with supplier-compliance checklists.
Competitive landscape: capability profiles and strategic implications
The market comprises established European engineering specialists, North American OEMs with a focus on integration and sanitation, and a spectrum of regional manufacturers offering cost-competitive machines. Our qualitative assessment of core competitors identifies distinct go-to-market positioning and procurement implications:
- MAJA Maschinenfabrik (Kehl, Germany) — Known for precision open-top EVM series and EASY models, MAJA’s offerings are particularly suitable where integration into automated lines is prioritized. Strategic implication: select MAJA when tight integration with existing automated carcass or cut-up lines is a priority and when procurement values long-term yield optimization over minimal upfront cost.
- NOCK Maschinenbau (Friesenheim, Germany) — NOCK emphasizes high-precision and robust industrial construction. Strategic implication: NOCK is a fit for processors that require continuous-duty robustness and minimal yield variance on challenging cuts, making them attractive for larger plants with demanding throughput.
- Ross Industries (Midland, Virginia, USA) — With a recent rollout of compact models such as the AMS 400 and exhibit activity on the AMS 533, Ross targets smaller-to-medium processors who require high yields in modular footprints. Strategic implication: consider Ross for decentralized processing sites or where sanitation-first, compact footprints are required.
- Grasselli (Albinea, Italy) — Offers high-yield derinders and skinners, often chosen for delicate cuts. Strategic implication: premium solution for processors handling high-value cuts or volatile product mixes that demand gentleness and precision.
- Townsend (Marel/JBT) — Integrated into larger processing ecosystems; emphasis on yield and system-level optimization. Strategic implication: best for processors pursuing deep automation and full-line supplier single-source strategies.
- Bettcher Industries (Ohio, USA) — Focus on handheld and modular platform partnerships; demonstrates strong channel activity in trade shows. Strategic implication: attractive for processors who want flexible, hybrid manual/automatic workflows and rapid retraining capability.
- Regional OEMs (e.g., Cretel, Chinese manufacturers) — Cost-competitive models and flexible customization; useful for capex-constrained projects or where rapid equipment replacement cycles are common. Strategic implication: factor in total cost of ownership, parts availability, and compliance documentation when choosing lower-cost OEMs.
Macro supply and regulatory pressures shaping 2026 choices
Two structural forces accelerate decision-making in 2026. First, the stainless-steel supply chain and associated material cost dynamics: food-grade stainless steel remains the mandated substrate for hygienic design, and broader stainless-steel markets continue to show growth — a consideration for procurement timing and inventorying of long-lead components. For context, the broader stainless-steel market has been forecast to expand materially over the coming decade, influencing OEM lead times and spare-parts pricing.
Second, labor availability and hygiene regulations are pressing processors toward automation that reduces manual handling and improves repeatable yields. Our field interviews indicate that processors valuing predictable yield improvement and reduced rework are prioritizing investments in automatic membrane skinners or hybrid lines with targeted automation islands. Regulatory expectations around cleanability and easy-disassembly also push designs that favor stainless-steel hygienic finishes and validated CIP procedures.
Five tactical recommendations for 2026 procurement cycles
- Run yield-first pilots: prioritize pilot protocols that measure net yield uplift and rework reduction in site-specific conditions before committing to line-wide rollouts.
- Time the market for lead-time risk: place strategic long-lead orders for stainless-steel-intensive equipment in Q2–Q3 2026 if your TCO analysis is sensitive to material-sourced price swings.
- Prioritize service economics: include multi-year service and spare-parts commitments in RFPs to avoid post-installation margin erosion from downtime.
- Adopt modularity: choose equipment architectures that support incremental automation, allowing phased CAPEX while capturing early yield improvements.
- Standardize hygiene validation: require supplier-supplied CIP test results and documentation as part of technical acceptance criteria.
How to use this preview
This preview is intended to orient senior teams and procurement committees to the directional market facts and the strategic choices they will face in 2026. It signals where value can be captured — yield, downtime reduction, and integration benefits — and where risks lie — supply-chain exposure and service costs. For actionable segment-level inputs, unit-cost benchmarking, and our supplier scorecards, access to the full report and dataset is required; those deliverables convert strategy into executable procurement and engineering plans.
Contact PW Consulting to obtain the full Worldwide Meat Membrane Skinner Market report, or request a tailored briefing for your capital planning cycle. Our analysts can support bespoke vendor selection, pilot design, and ROI validation to accelerate confident decisions in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Meat Membrane Skinner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com