

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Class 2 E‑Bikes Market Poised for Rapid Growth — 11.58% CAGR Forecast Through 2032

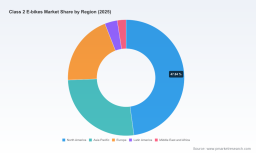
Worldwide Class 2 E-bikes Market: Strategic Briefing for 2026 Decision-Makers
PW Consulting today releases a strategic briefing drawn from our forthcoming market research report, Worldwide Class 2 E-bikes Market (base year 2025, forecast 2026–2032). As electric mobility accelerates beyond commuter niches into mainstream urban logistics and lifestyle mobility, Class 2 e-bikes—throttle-assisted machines with motor support up to 20 mph—are emerging as a decisive battleground for OEMs, component suppliers, fleet operators and regulators. This briefing highlights the macro trajectory, key competitive dynamics, regulatory inflection points, and the practical actions executives should prioritize in 2026. For full granular tables and segmented forecasts, consult the full report.
Badge Customization Service Market
Market snapshot — the big picture that should shape strategy
- Momentum and scale: The Class 2 market has moved from a nascent specialty segment in 2020 to a broad commercial and consumer market by 2025. Our market-sizing shows a multi-fold expansion from 2020 through 2025, with the market reaching a substantial USD-level size in 2025 and projected to continue rapid growth across the 2026–2032 horizon.
- Growth rate: We model a robust compound annual growth rate (CAGR) of 11.58% across the 2026–2032 forecast window—reflecting accelerating adoption driven by urbanization, last-mile logistics demand, product diversification, and supportive local policies.
- Concentration and competitive texture: The market remains fragmented, with the leading manufacturers holding a modest combined share relative to overall market volume—an open field for scale advantages, channel innovation, and consolidation plays.
Why this matters for 2026 corporate planning
2026 is a pivot year for Class 2 strategy. Buyers are moving beyond price-first purchase criteria to expect integrated safety systems, dependable battery performance, and after-sales support. At the same time, regulatory and procurement requirements—especially in major U.S. states—are raising the bar for product qualification. The combined effect reshuffles the matrix of competitive advantage: design differentiation and regulatory compliance increasingly matter as much as unit economics.
Worldwide Flexible Concrete Vibrator Market
- Product roadmaps: Firms that treat throttle-capable e-bikes as a single SKUset risk missing adjacent growth pockets (cargo, folding, fat-tire/adventure) now validated by fleet trials and consumer demand. Firms must decide in 2026 whether to specialize, broaden, or platformize offerings.
- Supply-chain and battery strategy: With lithium-ion battery packs remaining the default energy source, battery chemistry, testing certification, and supplier diversification are top-rank risk areas. Regulatory certification requirements introduced in key markets mean procurement teams must qualify suppliers to accredited safety standards early in 2026.
- Channel and aftermarket: The interplay between direct-to-consumer (DTC) digital channels and traditional dealer networks is evolving. After-sales service becomes a central differentiator for fleet buyers and premium consumers, shifting cost structures to include service logistics and telemetry-enabled maintenance.
Regulatory and technology inflection points—what to model into 2026 budgets
- Battery safety standards: New regulatory requirements for battery certification and accredited lab testing that take effect in certain jurisdictions from January 1, 2026 raise entry costs and approval timelines for new models. Firms must budget for certification cycles and incorporate compliant battery pack designs or certified supplier contracts.
- Harmonized definitions: The Class 2 definition—throttle assistance up to 20 mph without pedaling—remains broadly adopted across jurisdictions. This provides an operational standard, but local implementation and safety testing regimes are diverging; scenario planning should assume increasing country- and state-level variability through 2028.
- Technology trends: Battery pack capacities in 2025/26 generally cluster in higher-capacity ranges to support throttle usage. Simultaneously, integration of telematics, remote diagnostics, and OTA firmware update capability is becoming a non-negotiable for fleet customers.
Competitive landscape — pragmatic implications for market positioning
The competitive set spans DTC disruptors, legacy bicycle OEMs, and specialist performance brands. Each archetype has a distinct set of strategic advantages and execution risks.
Worldwide Plating Bath Analysis Services Market
- Value DTC players (examples include several U.S.-based brands): These firms leverage online distribution, cost-focused BOMs, and modular product lines to win price-sensitive consumers and small fleets. Their scaling playbook centers on volume, rapid model iteration, and efficient logistics—but they must now integrate higher-cost battery certification and enhance service footprints to retain competitiveness.
- Traditional OEMs with dealer networks (global bicycle leaders and premium brands): These incumbents compete on brand, distribution depth, and dealer-enabled after-sales. They can absorb certification costs and emphasize quality and warranty, positioning themselves for urban commuters and premium fleet contracts.
- Performance and adventure specialists: Firms targeting off-road and high-mobility use cases can cross-sell into adventure and cargo niches. Their engineering expertise in ruggedization and motor performance allows optional throttle configurations that meet Class 2 requirements without sacrificing capability.
Recent product activity underlines the tactical diversity in 2026: several manufacturers launched or updated models with enhanced throttle and pedal-assist functionality and higher integration of battery and electronics—an indicator that product refinement, not just new entrants, will drive competitive churn in 2026.
What PW Consulting’s report delivers — actionable intelligence, not just numbers
Our full report is built for executable decision-making. Key deliverables include:
- Market sizing and seven-year forecasting (2026–2032) in constant USD, modeling multiple adoption scenarios and sensitivity to battery cost, urban policy, and fleet procurement rates.
- Go-to-market playbooks for OEMs, component suppliers and fleet operators: DTC vs. dealer strategies, pricing levers, and bundle/service monetization blueprints.
- Regulatory impact assessment and compliance roadmap: stepwise actions for battery certification, documentation templates, and expected approval timelines in priority markets.
- Supply-chain risk matrix and supplier qualification checklist: battery cell selection, pack assembly options, test-house partnerships, and inventory hedging approaches to maintain production continuity while meeting safety standards.
- Competitive profiles and scenario-based attacking/defending strategies for leading brands by capability set—product engineering, channel footprint, and after-sales networks.
- Case studies and pilot templates for fleet trials (last-mile, rental, municipal programs) with KPIs and contracting terms that accelerate procurement decisions.
Practical 90–180 day moves for executive teams
- Immediate: Initiate battery supplier audits and register models with accredited testing partners. Start certification queues where required—early submission reduces time-to-market friction.
- Near-term: Segment your 2026 product roadmap into “compliance-first” and “growth-first” cohorts. Allocate R&D spend to integration efforts (battery/BMS, telematics) that unlock recurring revenue through service contracts.
- Commercial: Pilot hybrid channel models—test dealer-assisted delivery for premium models while scaling DTC for entry-level SKUs. For fleet opportunities, bundle service+telemetry to convert trials into multi-year contracts.
- M&A and partnerships: Prioritize bolt-on acquisitions or long-term supply agreements in battery pack assembly, telematics platforms, or depot servicing networks to secure differentiated capabilities quickly.
How PW Consulting can support 2026 execution
Our consultancy offers rapid-cadence advisory engagements tailored to the unique challenges of Class 2 e-bike commercialization: from supplier due diligence and certification program management to go-to-market pilots and tender support for fleet bids. We couple market-facing insights with practical tools—procurement scorecards, RFP templates, and dealer transition playbooks—to accelerate implementation.
Closing—why the full report matters for board-level decisions
Class 2 e-bikes are no longer an experimental product vertical; they sit at the intersection of consumer mobility, urban logistics, and regulatory safety mandates. 2026 will be the year when companies either lock in advantage through disciplined investments in battery safety, service infrastructure and channel design—or face margin and access erosion as compliance costs and customer expectations rise.
PW Consulting’s Worldwide Class 2 E-bikes Market report synthesizes the data, competitive intelligence, and commercial playbooks boards and CEO teams need to align capital allocation, product development, and commercial execution for the next growth phase. The report contains the full regional and application-level breakouts, model-level forecasts and supplier maps that underpin the strategic recommendations summarized above.
For access to the full dataset, scenario models, and tailored advisory options, visit the PW Consulting report page or contact our advisory team to schedule a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Class 2 E-bikes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com