

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Three‑Phase Recloser Market to Reach USD 3.71 Billion by 2032, Growing at a 6.1% CAGR

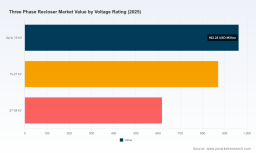
Worldwide Three Phase Recloser Market — Strategic Briefing for 2026 Decision-Makers
As utilities, OEMs, investors and system integrators reassess distribution grid priorities for 2026, PW Consulting’s latest Worldwide Three Phase Recloser Market report delivers the kind of decision-grade intelligence that separates reactive procurement from proactive strategy. Our analysis shows the market continuing its steady expansion, with the global three phase recloser market valued at approximately USD 2,450 million in 2025 and projected to grow to roughly USD 3,708 million by 2032 — a compound annual growth rate of 6.1% across the forecast window. This briefing summarizes the report’s strategic value for 2026 planning while intentionally holding back granular segment allocations to encourage direct access to the full study.
Worldwide Lithium-Ion Battery ICs Market
Executive snapshot: why this matters now
- Grid modernization programs and resilience mandates are accelerating demand for medium-voltage protection devices that support automation and self-healing functionality.
- Standards and compliance updates (notably recent amendments to recloser performance standards and transmission protection coordination rules) are reshaping technical specifications and supplier qualification criteria.
- Supply-chain volatility, driven by commodity and component pressures, is increasing procurement risk and elevating the value of inventory and contract strategies.
For 2026, these dynamics converge into a narrow window of strategic opportunity: prudently timed investments in smart reclosers can deliver reliability and operational savings, but only if organizations align technical specifications, sourcing approaches, and total-cost-of-ownership (TCO) models with near-term market realities.
Worldwide Acid and Alkali Etching Resistant Ink Market
What PW Consulting’s report gives you — practical, transaction-ready analysis
The report is structured for fast operational impact. Rather than an academic survey, it is a playbook for procurement, engineering, and corporate strategy teams entering 2026 procurement cycles. Key deliverables include:
Intelligent Driver Testing and Training System Market
- Robust market sizing and trend analysis — baseline market values, a seven-year forecast and scenario runs tuned to policy and commodity shocks.
- Vendor benchmarking and capability matrices — comparative assessments across product architecture, integration capabilities, aftermarket support, and roadmap maturity.
- Regulatory and standards nexus — a mapped view of how recent standards updates affect technical requirements, test protocols and certification timelines.
- Deployment playbooks — step-by-step guidance for pilots, scale rollouts, and interoperability testing with distribution automation platforms.
- Procurement and sourcing levers — forward-looking contracting templates, hedging approaches for critical components, and CAPEX vs OPEX trade-off analyses including TCO modeling.
- Supply-chain risk register — prioritized vulnerabilities and mitigation measures for components, production capacity and logistics bottlenecks.
- M&A and partnership screening — a shortlist framework for bolt-on acquisitions, strategic alliances and technology licensing aligned to three-phase recloser horizons.
How to use this intelligence in 2026
Executives should treat the report as a tactical toolkit to support three classes of decisions this year:
- Specification tightening: adopt interoperability and cybersecurity clauses in recloser specifications to ensure compatibility with grid management platforms and to future-proof investments.
- Sourcing strategy: differentiate between risk-tolerant pilots and risk-averse fleet replacements — lock volume for mature suppliers while reserving experimental scope for innovative entrants.
- Capital planning: use the report’s TCO models to compare lifecycle cost scenarios (purchase + installation + maintenance + outage mitigation) under multiple forecasted commodity and labor environments.
Concrete examples: a utility planning a feeder modernization in Q3–Q4 2026 can use our scenario outputs to optimize order timing and spare-parts strategy; an OEM can align its product roadmap to prioritize digital controllers and communications stacks; private equity and strategic acquirers can rapidly shortlist targets whose technology and footprint align with a partially consolidated market.
Competitive landscape — structure, motion and what it means for buyers
The three phase recloser market exhibits moderate concentration. The top three firms account for a meaningful share of industry revenue, and the top five capture a majority of market value — a structure that creates both stability and competitive pressure. From a buyer’s perspective, this yields distinct advantages (available capacity, warranty infrastructure, and certification depth) but also constraints (price stickiness for certain configurations and longer lead times during upgrades).
Key players covered in the report and their strategic postures include:
- ABB (Zurich, Switzerland) — strong in integrated automation and grid protection platforms; positions products for utility digitalization efforts and system-wide coordination.
- Eaton (Dublin, Ireland) — brings broad portfolio strength and legacy product families suited to overhead and substation applications; noteworthy for service networks and proven form-factor options.
- Schneider Electric (Rueil-Malmaison, France) — emphasizes smart-grid integration through its ecosystem offerings; competitive where EcoStruxure-led deployments are prioritized.
- Siemens (Munich, Germany) — offers deep protection relay expertise and integration into transmission-to-distribution workflows; attractive to utilities seeking vendor consolidation across protection equipment.
- S&C Electric Company (Chicago, IL, USA) — differentiated by specialized recloser product lines with a focus on self-healing feeder applications and recent compliance milestones that speak to reliability.
- G&W Electric (Bolingbrook, IL, USA) — notable for field wins and execution on grid modernization projects; reliable supply for large-scale deployment programs.
- NOJA Power (Brisbane, Australia) — innovator in pole-mounted automation with recent model launches that target higher-voltage segments and arc-quenching performance.
- Tavrida Electric (Brooklyn, NY, USA) — supplier of automatic circuit reclosers with vacuum interrupter technology, relevant in markets prioritizing compactness and modular servicing.
Recent discrete moves — product launches, major orders and standards certifications — illustrate the competitive dynamics: incumbents reinforce reliability advantages through certification and large deployments, while focused challengers push the feature frontier (faster arc interruption, tighter control loops, and lower lifecycle maintenance). For buyers, the practical implication is that technical evaluation criteria must capture not only hardware performance but also software maturity, integration APIs and aftermarket service economics.
Supply-chain and regulatory dynamics shaping procurement in 2026
- Standards evolution: utilities must account for updates that affect protection coordination and smart-grid compatibility when finalizing spec language and acceptance test plans.
- Component concentration: critical modules and proprietary interrupter technologies imply single-source risks for some product families; contract language should require lead-time commitments and vendor contingency plans.
- Cost pressure vectors: producers and buyers alike are negotiating around raw-material and labor inflation. Procurement teams should be prepared to incorporate indexation clauses or adopt staged purchasing to manage exposure.
In short, 2026 procurement must be multi-dimensional: balancing immediate operational needs, regulatory compliance, and mid-term resilience against evolving commodity and labor trends.
Five strategic recommendations for 2026
- Adopt modular procurement frameworks — separate core hardware from communications and control modules to enable technology refresh without full replacement.
- Negotiate multi-year supply agreements with performance-based clauses that link deliverables to integration, certification and warranty milestones.
- Prioritize pilot-to-scale pathways — validate interoperability and lifecycle assumptions in small-scale pilots before committing to system-wide retrofit programs.
- Institutionalize TCO decision rules — move beyond unit price to include outage-cost avoidance, maintenance savings, and software-driven operational benefits in investment cases.
- Monitor and map standards timelines — maintain a regulatory watch function to adapt procurement windows and testing programs to pending standard releases and certification lead times.
PW Consulting’s unique value — what you get beyond numbers
Our report couples quantitative forecasts with applied tools: vendor scorecards tailored to your procurement priorities, scenario-ready TCO calculators, and a risk register you can operationalize with suppliers. It is designed to be used in negotiation rooms, board briefings, and engineering planning cycles — not filed away as desk research.
Next steps — accessing the full intelligence
This briefing is a strategic primer. The full Worldwide Three Phase Recloser Market report contains the granular segmentation, regional demand analysis, and vendor-level financial estimates necessary for transaction execution and capital planning. To preserve the advisory value of our work while ensuring reader access to verified primary data, we have intentionally withheld detailed segmentation tables and region-by-region allocations in this release. For procurement teams, investor due-diligence groups and OEM strategy units preparing for 2026 activity, the full report provides the calibrated inputs required to execute with confidence.
Contact PW Consulting to request the comprehensive report, bespoke briefings, or an executive workshop to translate findings into an actionable 90–180 day plan.
For detailed analysis of this topic, please visit the official page: Worldwide Three Phase Recloser Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com