

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Telepharmacy Market Poised to Expand at a Robust 18% CAGR in 2026–2032 Forecast

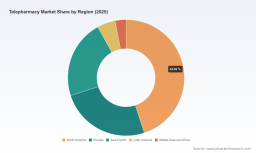
PW Consulting: Strategic Preview — Worldwide Telepharmacy Market Report (2026 Outlook)
Executive summary
PW Consulting’s latest industry briefing delivers the actionable intelligence senior executives and boards need to make high‑confidence decisions in 2026. Our Worldwide Telepharmacy Market report (base year 2025; historical scope 2020–2025; forecast 2026–2032) distils rigorous primary research, transaction-level commercial data, and regulatory scenario modelling into practical strategic guidance. The market has moved from niche adoption to mainstream integration: at the 2025 baseline the global telepharmacy market measured approximately USD 52,480 Million, and under our central forecast it expands at an 18.0% CAGR through 2032 to a multi‑billion USD opportunity that materially reshapes pharmacy economics, care delivery models, and vendor landscape.
Worldwide RGB Filters Market
Why 2026 is the inflection year
Two converging trends make 2026 a decision point for healthcare payers, health systems, retail pharmacy chains, PBMs, and technology vendors. First, regulatory and reimbursement shifts enacted or affirmed approaching 2026 materially reduce historical uncertainty around remote supervision and telehealth billing. Second, scaling technologies — cloud verification platforms, remote dispensing automation and integrated patient engagement — have reached an operational maturity that enables predictable ROI on multi‑site deployments.
Wind Turbine Blade Maintenance Market
- Regulatory clarity: Recent federal actions have extended and normalized telemedicine flexibilities and redefined supervision constructs, reducing compliance risk for remote pharmacist models.
- Reimbursement alignment: Finalized updates to telehealth payment policy create durable reimbursement pathways for remote clinical services and support new commercial contracting approaches.
- Market scale: A strong mid‑to‑high double‑digit CAGR implies material addressable market expansion — a factor that will shift capital allocation for incumbents and new entrants in 2026.
How policy changes alter strategic calculus
Regulation and reimbursement developments recorded through late‑2025 and early‑2026 constitute the most immediate drivers of commercial opportunity. Noteworthy actions include extensions of telemedicine prescribing flexibilities for controlled substances and a permanent clarification of direct supervision standards for telehealth modalities. Simultaneously, state‑level PBM reforms and federal pricing mechanisms are changing the pharmacy revenue and margin profile.
Worldwide Image Processing Unit Market
- Operational impact: With telepharmacy supervision rules clarified, health systems can scale centralized verification and clinical review workflows without local pharmacist duplication, delivering labor arbitrage and 24/7 coverage economics.
- Commercial impact: Reforms to PBM contracting and Medicare Part D pricing create near‑term pressure on margins for some dispensing models while opening value‑based contract design for medication management and adherence programs linked to telepharmacy services.
- Access impact: State authorizations and regulatory experimentations accelerate solutions for rural and underserved communities, changing patient access metrics and population health KPIs used by providers and payers.
Competitive landscape — what incumbents and challengers are doing
The competitive map combines broadscale pharmacies, distribution integrators, specialist telepharmacy platforms, and automation vendors. Market concentration remains moderate: the top three firms account for roughly one‑third of industry revenue, while the top five capture just over two‑fifths — a structure that both preserves room for specialist entrants and favours consolidators seeking scale.
- Cardinal Health — A large healthcare services player integrating remote pharmacy services into hospital and system offerings to ensure continuous clinical coverage and compliance. Their strength is in deployment scale and integration with acute‑care workflows.
- PipelineRx — A cloud‑native telepharmacy platform provider focused on order verification and clinical connectivity. PipelineRx illustrates the platform play: high data throughput, API‑first design, and partnerships that enable rapid hospital rollouts.
- TelePharm (Health Carousel) — Specialist in retail and outpatient telepharmacy enabling community pharmacies to expand service coverage and capture incremental revenue through remote pharmacist oversight.
- McKesson Corporation — Distribution and services giant embedding telepharmacy within broader supply‑chain and specialty pharmacy solutions to preserve margin and extend services to health systems and retail partners.
- CVS Health and Walgreens Boots Alliance — Retail incumbents combining digital front doors with distributed pharmacy networks; their strategic advantage is patient reach, existing care programs, and broad channel integration.
- Express Scripts (Cigna) — PBM and specialty pharmacy capabilities allow for integrated medication therapy management and remote consultation offerings aimed at influencing adherence and total cost of care.
- Omnicell, ScriptPro, North West Telepharmacy Solutions — Automation and service specialists enabling remote dispensing, inventory control and rural/critical access pharmacy coverage.
Each archetype — platform providers, distribution incumbents, retail integrators, and automation specialists — must choose between cooperating, competing, or acquiring. In 2026, we expect intensified partnership activity (platforms + retail networks), targeted tuck‑ins by distributors, and selective rollups of regional telepharmacy service providers.
Strategic imperatives for executives in 2026
Based on our scenario analyses and commercial diligence, we recommend five parallel lines of action for boards and executive teams preparing budgets and capital plans in 2026:
- Define clear value anchors. Prioritize applications where telepharmacy demonstrably reduces total cost of care (e.g., medication reconciliation for high‑risk discharges, centralized overnight verification) and design KPIs that capture both clinical and commercial value.
- Lock in regulatory and reimbursement pathways. Engage proactively with payers and regulators to secure contract language and billing constructs that match intended service models. Where policy is transitional, build contingency triggers into roll‑out plans.
- Choose the modular technology stack. Separate core verification/clinical decision support from dispensing hardware and patient engagement layers to allow flexible vendor swaps and to preserve upgrade paths as standards evolve.
- Structure go‑to‑market as partnerships. For retail chains and health systems, telepharmacy is often not a standalone revenue generator; it is a facilitator for expanding service lines, improving adherence, and reducing labor costs. Look for co‑investment models with platform vendors and PBMs.
- Prepare for operational scale. Successful programs in 2026 will be those that standardize SOPs, invest in workforce training for remote collaboration, and implement continuous monitoring to ensure quality and compliance across jurisdictions.
What our report delivers (practical contents)
The full PW Consulting report is designed as an implementation playbook, not an academic exercise. It contains:
- Proprietary market model and 2026–2032 forecast with scenario variants and sensitivity analysis to test price, reimbursement and adoption inflection points.
- Regulatory impact matrix and playbooks for compliance across major jurisdictions, including templates for supervision policy alignment and DEA/CMS contingencies.
- Commercial diligence toolkits for M&A and partnership screening, including tailored valuation adjustments for software vs services vs automation assets.
- Vendor heatmaps and comparative profiles for strategic sourcing — technical architecture, integration posture, deployment timelines, and proven ROI use cases.
- Operational checklists and KPI libraries for 24/7 centralized verification centres, outpatient telepharmacy rollouts, and rural pharmacy enablement programs.
- Financial templates: unit economics models, reimbursement scenario planners, and break‑even analyses for pilot to enterprise scale.
We intentionally designed these elements so that leadership teams can move from boardroom hypothesis to operational pilot within 90–180 days, with measurable milestones and governance artifacts ready for investor or payer review.
Near‑term signals to monitor
To manage downside risk and capture upside, leadership should track a short list of leading indicators through 2026:
- Final rule clarifications or new guidance from federal agencies on supervision and controlled substance prescribing via telemedicine.
- Payer contract language and reimbursement codes for remote pharmacy services and medication management.
- State‑level telepharmacy authorizations and any restrictions or novel licensure pathways that affect cross‑jurisdictional staffing models.
- PBM contracting practices and pricing reforms that may alter dispensing economics for low‑margin drugs.
- Field performance metrics from early‑adopter deployments: verification throughput, clinical intervention rates, medication error rates, and patient satisfaction.
Conclusion — the strategic value of our analysis for 2026
The telepharmacy landscape entering 2026 rewards decisive action. Our research shows a rapidly expanding market underpinned by supportive policy moves and accelerating technology maturity. That combination turns telepharmacy from an operational experiment into a strategic lever for cost, access and clinical quality. However, the path to value is implementation‑intensive: choices about platform architecture, partnership models, regulatory positioning and payer negotiation will determine winners and losers.
PW Consulting’s report is purpose‑built to guide those choices. We present the evidence base, the commercial playbooks and the risk maps that senior teams need to translate market growth into durable competitive advantage — while withholding proprietary segmentation tables and granular revenue splits from this preview. For full data tables, regional and end‑use breakdowns, vendor scorecards, and downloadable financial models, visit our report page and download the complete Worldwide Telepharmacy Market report.
For detailed analysis of this topic, please visit the official page: Worldwide Telepharmacy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com