

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Worldwide Monoclinic Grain Zirconia Market Poised for a 5.4% CAGR Through 2032

Worldwide Monoclinic Grain Zirconia Market: Strategic Outlook and Actionable Intelligence for 2026 Decision-Makers
Executive summary
PW Consulting’s new industry brief on the Worldwide Monoclinic Grain Zirconia Market synthesizes five years of historical dynamics and a seven-year forecast horizon into an actionable playbook for executive teams planning for 2026. Our analysis shows that the market has recovered and expanded since 2020, rising materially by the 2025 base year, and is projected to grow at a steady compound annual growth rate of 5.4% across the 2026–2032 forecast window. By 2032, the market is expected to reach a markedly higher scale compared with the 2020 baseline, reflecting both volume-driven demand and ongoing value capture from higher‑specification grades and service models.
Food Ingredients Sterilization Market
Why this matters for 2026 strategic plans
-
Timing: 2026 is a strategic inflection point. After the recovery phase through 2024–2025, the medium-term outlook points to supply-side stresses and policy-driven reshoring incentives that will materially affect sourcing, pricing, and risk management for producers and consumers alike.
Full-Stack Microsystem Solution Market -
Portfolio prioritization: Demand drivers are increasingly differentiated by end-use technical requirements—high‑purity powders and tailored particle-size distributions command margin premiums. Companies that can align product roadmaps and pricing models to these technical corridors will secure disproportionate returns.
Wafer Cutting Machines Market -
Supply resilience: Raw‑material dynamics and processing concentration mean that buyers and integrated suppliers must move from commodity buying to strategic sourcing: multi-sourcing, long‑term offtake arrangements, and inventory engineering will be non‑negotiable capabilities for 2026.
-
Competitive playbooks: Market concentration indicates room for both consolidation and niche incumbency. The top three players account for a meaningful share of global supply, while the top five together represent a clear oligopolistic tier—creating distinct paths for mid‑sized challengers and global integrators.
What PW Consulting’s report delivers (operationally focused)
We designed the report as a hands‑on tool for strategy, procurement, and commercial teams. It does not merely describe the market—it equips teams with decision-ready modules, including:
-
Scenario-based demand modelling calibrated to industry cycles and key end-use adoption curves.
-
Supply‑chain heatmaps that highlight processing choke points, feedstock flows, and concentrated nodes where policy or disruption risk is highest.
-
Supplier scorecards and capability matrices that benchmark producers on purity grades, particle control, production technologies, and service attributes.
-
Commercial playbooks: go‑to‑market strategies, premium‑grade pricing frameworks, and tender templates for secure long‑term sourcing.
-
Cost‑curve benchmarking and sensitivity analysis to test margin exposure under different feedstock and energy cost scenarios.
-
Regulatory & policy risk matrices, including mitigation options for firms operating across friend‑shoring and critical‑materials policy regimes.
-
M&A and partnership target shortlist with diligence checklists focused on integration risk and technology fit.
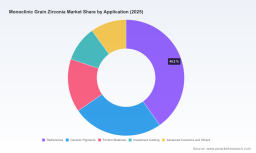
Note: In the spirit of this release being a strategic “trailer,” granular regional and application split tables have been deliberately withheld. The full report contains the detailed tables, downloadable assets, and Excel modelling templates required for programmatic decision-making.
Market dynamics and near‑term drivers
Several structural forces will shape 2026 trajectories:
-
Feedstock and processing concentration: The upstream supply chain is anchored by limited zircon feedstock sources and a concentrated processing footprint for intermediate zirconium compounds. Policymakers in multiple jurisdictions now treat zirconium‑related value chains as strategically sensitive; this is prompting a wave of supply‑chain reconfiguration and friend‑shoring initiatives.
-
Elevated feedstock realism: Across 2024–2025 the industry has operated under elevated but stabilizing raw‑material cost conditions. Producers and buyers have adapted via pricing contracts, formula‑based escalators, and closer inventory collaboration.
-
Potential structural shortfall: Our cross‑checked supply modelling indicates a non‑trivial risk of tightening beyond 2026 if current mine maturities and capacity expansion plans do not materialize. This potential deficit elevates the value of secured feedstock and vertical integration in strategic planning.
-
Demand heterogeneity: While traditional refractory and ceramic pigment demand remains important, higher-growth pockets are emerging in advanced ceramics, thermal‑barrier systems, and specialty casting applications where higher‑purity and tailored grain architectures are required.
Competitive landscape — who matters and why
The market is served by a mix of global leaders and specialized regional players. The report profiles each firm with actionable intelligence on manufacturing footprint, technical differentiation, and commercial posture. Highlights include:
-
Saint‑Gobain ZirPro (France) — A leading global supplier known for high‑purity powders and a broad portfolio of grades for PZT manufacture, refractories, and advanced ceramics. Their capability to deliver customizable particle‑size distributions and application engineering services positions them strongly in premium segments. ( https://www.zirpro.com)
-
Washington Mills (United States) — A major fused monoclinic grain producer with product lines tailored to refractory, abrasive, and ceramic markets. Their emphasis on production scale and product consistency is a competitive anchor for volume contracts. ( https://www.washingtonmills.com)
-
Zircoa (United States) — Specializes in high‑purity powders and granular products for extreme high‑temperature refractories and aerospace applications. Their long track record and niche technical focus make them a preferred partner where performance margins outweigh commodity cost competition. ( https://zircoa.com)
-
TAM Ceramics (United States) — Known for electrically fused monoclinic zirconia grains across multiple particle-size distributions, serving markets that require tight spec conformance such as setter sands and thermal coatings. ( http://tamceramics.com)
-
Imerys (France) — Offers a suite of zirconia powders targeting structural and functional advanced ceramics, leveraging industrial minerals integration to serve global customers. ( https://www.imerys.com)
-
GNPGraystar (United States) — Supplies fused powders with unique micro‑coral microstructures for kiln furniture and high‑temperature structural ceramics.
-
Foskor Zirconia (South Africa) and Daiichi Kigenso Kagaku Kogyo (Japan) — Regional producers with strong performance in refractory and specialty ceramics markets, important for regional sourcing and diversification strategies.
Market concentration metrics underscore the competitive dynamics: the three largest suppliers account for a sizable single‑digit share of the market, and the top five collectively control a clear majority position—conditions that favor both selective consolidation and premium differentiation strategies.
Strategic recommendations for 2026
-
Secure feedstock through layered contracts and strategic equity stakes: Firms should prioritize multi‑year offtakes, capacity reservation, and minority stakes in upstream sources where feasible.
-
Invest in application engineering: Upgrading laboratory and technical service capabilities will translate to higher ASPs (average selling prices) and longer customer tenures in advanced segments.
-
Design flexible manufacturing footprints: Modular capacity that can switch between fused and chemically synthesized monoclinic products will provide resilience against feedstock and policy shocks.
-
Pursue targeted M&A and alliances: Focus on bolt‑on acquisitions that bring particle‑control IP, application engineering teams, or regional footprints in high‑growth markets.
-
Embed regulatory scenario planning: Build playbooks for friend‑shoring, critical‑materials compliance, and export‑control contingencies to avoid disruptive responses post‑factum.
Risks, mitigations, and monitoring signals
Key risks include upstream supply contraction, policy-driven trade restrictions, and sudden shifts in demand composition toward advanced ceramics. PW Consulting recommends a monitoring dashboard that tracks feedstock capacity announcements, regional processing investments, and policy statements from strategic governments. Leading indicators we monitor include sustained narrowing of supplier options for high‑purity intermediates and any escalation of import‑control measures affecting zirconium compounds.
How the report helps you act
For teams preparing 2026 budgets, capital plans, or M&A pipelines, this report is designed as an executable intelligence asset. It combines market-size trajectories (historic and forecast), policy and supply‑chain diagnostics, supplier benchmarking, and transaction readiness templates. If your objectives include securing feedstock, upgrading product portfolios, or evaluating consolidation targets, the report translates market insight into tasks, timelines, and financial sensitivities that map directly to corporate decision processes.
Next steps
To preserve the strategic value of our analysis and to support robust, proprietary decision‑making, we have intentionally withheld granular regional and application split tables from this release. Corporate clients and executive subscribers may access the comprehensive dataset—including downloadable models, supplier scorecards, and the full workbook—on PW Consulting’s report portal. For bespoke briefings, scenario workshops, or to license the underlying spreadsheets for internal use, contact our subscription team to schedule a tailored strategy session.
For detailed analysis of this topic, please visit the official page: Worldwide Monoclinic Grain Zirconia Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com