

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Unbleached Kraft Pulp (UKP) Market Poised to Expand at a 4.15% CAGR, New Insights Reveal

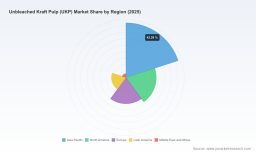
Worldwide Unbleached Kraft Pulp (UKP) Market — 2026 Strategic Outlook
PW Consulting’s latest Worldwide Unbleached Kraft Pulp Market brief, anchored on a 2025 base year and projecting through 2032, delivers the forward-looking intelligence senior executives and investment committees need to set course for 2026 and beyond. The market, which has expanded meaningfully since 2020, reached approximately USD 17.45 billion in 2025 and is projected to grow at a compound annual growth rate (CAGR) of roughly 4.15% over the 2026–2032 forecast window. Underlying this headline growth are structural shifts in packaging demand, feedstock dynamics, and a tightening regulatory environment that together reframe value and risk across the value chain.
Worldwide Ocarina Market
Why 2026 Is a Strategic Inflection Point
-
Visibility into 2026 is essential because capital decisions (mill debottlenecks, low-carbon retrofits, and select greenfield options) made this year will begin to influence global supply balances by the latter half of the decade.
Worldwide Dry Cleaning Solvent Market -
Corporate procurement cycles and long-term off-take agreements signed in 2026 will lock buyers and sellers into exposures to feedstock and compliance risks that are already evolving today.
Worldwide Parcel Audit Software Market -
Regulatory deadlines and tariff regimes that come into force around 2024–2026 mean that 2026 will be the first full year where these rules materially affect trade flows and certification costs.
Market Trajectory at a Glance
Since 2020 the UKP market has experienced a steady expansion, interrupted by cyclical distortions in pulpwood costs and export conditions. After recovering to an estimated USD 17.45 billion in 2025, our baseline forecast points to growth into 2026 and a steady climb through 2032, reaching an aggregated market size consistent with a mid-single-digit CAGR (4.15%) over the forecast horizon. This trajectory combines steady demand from packaging and industrial applications with incremental capacity investments and re-purposing of existing kraft assets toward unbleached grades.
Key Market Dynamics Shaping 2026 Decisions
-
Demand-side pull: Recycled-fiber substitution limits and the premium placed on unbleached high-strength grades for sacks, linerboard, and industrial packaging are sustaining structural demand growth. Packaging customers increasingly prize mechanical performance, traceability and low-chemical footprints—attributes that favor certain UKP producers.
-
Supply-side adjustment: Select producers are expanding unbleached capacity and launching high-strength grades, altering competitive positioning within a market that remains moderately concentrated (top three producers account for roughly 42% of supply; top five roughly 58%). These investments will influence regional availability and price-setting over the medium term.
-
Feedstock and cost pressure: Logging constraints and seasonally higher harvesting costs have pushed softwood and hardwood chip prices higher. Industry reporting indicates material increases in chip prices late in 2024, and pulpwood price averages rose into H2 2024—both of which compress mill margins unless offsets are found.
-
Regulatory and trade drivers: Evolving due-diligence requirements and tariff actions are changing risk premia for exporters and importers. The EU’s deforestation regulation and targeted tariffs by key importers are already affecting sourcing strategies and will be a constant factor in contract negotiations in 2026.
Notable Industry Developments — What They Mean
-
Suzano’s announced expansion of capacity at its Cerrado Project signals a meaningful volume increase from a low-cost, eucalyptus-based platform. For buyers, this can unlock competitively priced long-term volumes but also raises strategic questions about how to manage concentration of feedstock exposure.
-
West Fraser’s launch of a high-strength unbleached grade highlights product differentiation as a core competitive lever. Producers that move up the strength curve are better positioned to serve premium packaging niches and to defend margins against rising feedstock costs.
-
Metsä Fibre’s certification renewal is a reminder that chain-of-custody and forest certification will be prerequisites for many institutional buyers. Certification continuity reduces trade friction, especially into markets with stringent due diligence rules.
Competitive Landscape — Practical Implications
The UKP sector combines large, diversified pulp producers with regional specialists. Incumbent majors maintain vertically integrated platforms—ranging from plantation or forest ownership to pulp manufacturing and downstream paper converting—which creates differentiated cost and service positions. For corporates evaluating supply security or acquisition targets in 2026, the following competitive characteristics matter most:
-
Feedstock flexibility: Firms that can switch between hardwood and softwood inputs, or that benefit from integrated timber supplies, have a defensible advantage when chip prices spike.
-
Geographic diversification: Export hubs and supplier footprints affect delivery risk and exposure to tariffs or regional regulatory changes. New capacity in Brazil, for example, materially alters Atlantic basin trade dynamics.
-
Product and quality differentiation: High-strength grades and specialty unbleached fibers command premium positions in sack and heavy-duty packaging markets.
-
Compliance and certification: Producers with robust FSC/PEFC/traceability systems (and alignment with food-contact rules where relevant) will be preferred by multinational buyers constrained by procurement policies and auditability requirements.
Key players we profile in detail include International Paper, West Fraser, Suzano, UPM, Stora Enso, Metsä Fibre, Eldorado, and Ilim. PW Consulting’s company dossiers synthesize mill-level economics, recent capital activity, strategic intent, and likely medium-term moves—essential inputs for M&A screens, strategic procurement, and competitor response planning.
What PW Consulting’s Report Delivers — The Practically Actionable Elements
Our report is built to support tactical 12–18 month decisions and longer-term strategic positioning. Among the operational and board-level deliverables included are:
-
Market sizing and a transparent forecasting model that links demand drivers to scenario outputs (base, upside and downside) for 2026–2032, including sensitivity levers for feedstock costs, energy, and trade barriers.
-
Supply-demand balance and a mill-level cost curve that highlights likely marginal producers and regional shortfalls that could create price volatility.
-
Regulatory risk maps (EUDR, national sanitary and food-contact standards, and tariff exposure) with mitigation playbooks for procurement and compliance teams.
-
Trade flow analysis and logistics overlays identifying potential chokepoints, storage arbitrage opportunities, and transit-risk differentials.
-
Commercial playbooks for buyers and sellers: negotiation strategies, contract clause templates addressing force majeure and certification requirements, and pricing index recommendations.
-
Investment and M&A screening tools: target filters, integration risk checklists, and post-acquisition synergy realizations tailored to UKP dynamics.
-
ESG and certification trackers enabling firms to align sourcing to buyer expectations and regulatory compliance deadlines, including practical steps to meet zero-chlorine mandates for food-contact grades.
How to Use This Analysis to Shape 2026 Decisions
-
CapEx sequencing: Use the PW Consulting marginal-cost and supply-balance outputs to prioritize brownfield reliability projects over greenfield expansion when short-term feedstock volatility dominates.
-
Sourcing strategy: Hedge through diversified supplier panels and include certification and trade-compliance clauses to minimize tariff and EUDR exposure. Consider long-term offtake with staggered indexation to raw material baskets.
-
Product development: Accelerate development of high-strength, low-chemical unbleached grades if serving premium sack and industrial packaging markets—where willingness-to-pay is strongest.
-
Commercial terms: Update contracts to allocate certification cost increments and to provide transparent mechanisms for feedstock-driven cost pass-throughs.
-
M&A and partnerships: Target assets that fill strategic feedstock or geographic gaps, but use our due-diligence templates to stress-test trade and regulatory risk scenarios before close.
Methodology and Confidence
PW Consulting’s model combines proprietary trade-flow modeling, mill-level operating cost benchmarking, primary interviews with producers and major buyers, and public disclosures. The analysis is anchored on a 2025 base and projects through 2032 with scenario sensitivity to feedstock cost shocks, regulatory tightening and demand elasticity for packaging substitutes. Our confidence intervals widen by 2032 to reflect the range of plausible outcomes, which is why scenario-based planning is integral to our recommendations.
Conclusion — A Practical Call to Action
For C-suite teams, procurement leaders, and investors, 2026 is not merely another planning year—it is the definitive window to lock in supply strategies, align compliance capabilities, and position portfolios for a market that is growing modestly but shifting structurally. PW Consulting’s Worldwide Unbleached Kraft Pulp Market report supplies the market-level context, company-level intelligence, and tactical tools required to convert insight into action.
To access the full dataset, mill-level assessments, and customizable decision-support tools, please visit PW Consulting’s report page or contact our industry team to request a tailored briefing. The public summary flags the trends; the full report equips you to act.
For detailed analysis of this topic, please visit the official page: Worldwide Unbleached Kraft Pulp (UKP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com