

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Cellulose Derivative Market Forecast to Top USD 10.68 Billion by 2032

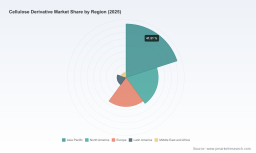
Worldwide Cellulose Derivative Market: Strategic Intelligence for 2026 — A PW Consulting Preview
PW Consulting’s latest market research, Worldwide Cellulose Derivative Market (base year 2025), synthesizes multi-year trend analysis, commercial intelligence and forward-looking scenario work to equip executives with decision-grade insight ahead of 2026. Our proprietary modelling shows the sector expanding from roughly USD 7.1 billion in 2025 to a materially larger global pool by 2032, with a compound annual growth rate of 6.01% across the 2026–2032 forecast window. The market’s recovery and re-acceleration since 2020 — when we tracked a substantially smaller base — reflect structural demand tailwinds in regulated consumer segments, construction rebound dynamics, and a rapid cadence of product innovation aimed at sustainability-led substitution.
Sterile Goods Transport Cart Market
Why 2026 Is a Pivotal Year for Players Across the Value Chain
-
Macro inflection: Manufacturers and end-users are navigating a phase where stable, mid-single-digit growth masks important structural shifts — from a commodity-like supply posture to differentiated, sustainability-driven premiumization in several end markets.
Diamond Roller Dresser Market -
Supply-side repricing and trade dynamics: Changes in trade policy and upstream raw-material availability are remapping procurement strategies and route-to-market economics, encouraging greater vertical coordination and risk mitigation by key producers and major buyers.
Worldwide Blast Furnace Market -
Regulatory acceleration: Stricter environmental rules in mature markets are fast-tracking demand for bio-based and readily biodegradable cellulose derivatives as practical alternatives to traditional synthetics in coatings, personal care, and food-contact applications.
-
Innovation and capacity moves: A steady flow of specialty launches and capacity announcements — from biodegradable esters for cosmetics to large-scale cellulose ether output plans — is changing the competitive calculus between incumbents, regional suppliers, and new entrants.
What the Report Delivers — Actionable, Execution-Focused Content
-
Transparent market-sizing and replicable methodology: We provide historic series and a rigorous forecast model (2026–2032) that supports sensitivity testing across demand, pricing and cost inputs.
-
Commercial playbooks: Detailed go-to-market and pricing strategies for upstream producers, midstream formulators and downstream brand owners, including best-practice contractual language, indexation templates and margin management approaches.
-
Raw-material and cost-sensitivity toolkit: Scenario matrices that quantify the impact of dissolving-pulp feedstock swings and regional logistics shocks on EBITDA across typical product lines.
-
Supplier and buyer mapping: A practical supplier short-list, counterparty risk heatmaps and procurement scorecards to support strategic sourcing and supplier consolidation programs.
-
Regulatory and product-compliance matrix: Cross-jurisdictional requirements, timelines for phase-ins, and certification pathways for bio-based and biodegradable claims.
-
Technology and innovation pipeline review: Comparative assessment of emerging cellulose ester and ether chemistries, their application windows, and co-development propositions for formulators and brands.
-
M&A and partnership playbook: Identification of logical bolt-on targets, valuation bearings and due-diligence checklists shaped by product, geography and sustainability attributes.
-
Early-warning and opportunity signals: Quantified triggers — from raw material index shifts to regulatory milestones — designed to inform watchlists and capital-allocation gates.
Competitive Landscape: How Established Players and Specialists Are Positioning
The top-tier and specialist suppliers continue to set the strategic tempo. Dow, Ashland and Shin-Etsu remain pre-eminent in cellulose ethers and high-purity pharmaceutical grades, leveraging global production footprints and long-standing formulation expertise. Eastman and Daicel are pushing the high-value end of the market with biodegradable cellulose esters and spherical particles that target cosmetics and personal care formulations seeking microplastic replacements. Specialty producers — including CP Kelco, Nouryon and Celanese — focus on differentiated chemistries and application-specific services that support paints, coatings and industrial uses.
Regional and niche players such as Lenzing, Borregaard, Rayonier Advanced Materials, LOTTE Fine Chemical and DKS bring capabilities in sustainable sourcing, unique feedstock pathways and proximity advantages to local markets. Recent developments recorded in our coverage — new biodegradable micropowder launches, eco-friendly spherical cosmetic particles, exclusive partnerships for pharmaceutical ethyl cellulose, and announced capacity additions — underline a bifurcating market: volume-driven commodity competes on scale, while specialty pockets compete on product performance and sustainability credentials.
Strategic Implications for Competitors and Customers
-
Incumbent majors should prioritize scalable sustainability: incumbents with broad R&D and commercialization platforms are best positioned to monetize biodegradable grades at scale, but must sequence capex intelligently against the pace of downstream adoption.
-
Mid-sized players can win in niches: focused portfolios (e.g., pharma HPMC grades, high-purity CMC for food) and fast co-development cycles create defensible premium positions without competing on bulk commodity pricing.
-
Downstream formulators and brands must de-risk supply while accelerating differentiation: multi-year supply agreements, dual-sourcing strategies and collaborative product development with suppliers will be table stakes for 2026.
-
Private equity and strategic acquirers will find asymmetric value in bolt-on specialty cellulose platforms that combine customer intimacy with sustainable feedstock claims.
Raw Materials and Supply-Chain Strategy
Dissolving-grade wood pulp remains the primary upstream feedstock. Volatility in pulp availability, shipping dynamics and regional policy shifts can materially change cost curves. Our report equips procurement and strategy teams with hedging templates, inventory optimization algorithms and a decision framework for nearshoring vs. global sourcing. We also model trade-policy scenarios and their pass-through effects to downstream selling prices — supporting more confident contract structuring and capex timing decisions.
Regulation, Sustainability and New Product Trajectories
Regulatory pressure in Europe and North America continues to favor bio-based, readily biodegradable solutions across coatings, personal care and food-contact contexts. This regulatory tailwind is already shaping R&D pipelines and commercialization priorities: product launches focused on biodegradable esters for cosmetics and microplastic-free cosmetics ingredients are competing for first-mover advantage. Certifications, chain-of-custody transparency and verifiable life-cycle analyses are now commercial differentiators — not just compliance checkboxes.
2026 Playbook — Concrete Moves PW Consulting Recommends
-
Prioritize capital and R&D into product classes where biodegradability and feedstock traceability unlock meaningful price premia.
-
Secure feedstock through a mix of long-term offtakes, strategic equity stakes in pulp-supply nodes, and option agreements to manage cost exposure.
-
De-risk supply by diversifying processing footprints across trade blocs to reduce single-point-of-failure exposure to tariff or logistics shifts.
-
Accelerate joint development agreements with downstream brand owners to lock demand and co-create formulatory solutions that lower adoption friction.
-
Use our scenario models to time capacity investments: avoid committing to large brownfield expansions in segments where adoption lags regulatory certainty.
-
Develop a sustainability certification roadmap and an evidence-based marketing plan to capture the premium in regulated markets.
How PW Consulting Supports Executive Action
Our report is designed as a decision-support engine — not a static PDF. Beyond the published intelligence, PW Consulting offers embedded advisory: bespoke re-forecasting for specific product lines, supplier negotiation support, M&A diligence tailored to cellulose chemistries, and hands-on commercialization sprints with internal R&D and sales teams.
To access the full dataset, segmented forecasts and granular scenario outputs (including region-, type- and application-level projections and our proprietary supplier scorecards), visit the report landing page. The public preview you’ve read is deliberately selective: it demonstrates the analytical depth and practical applicability of our work while reserving the detailed segment-level figures and contract-ready tools for licensed subscribers and clients engaged in advisory projects.
For C-suite leaders preparing 2026 budgets, capital plans or M&A pipelines, this is the moment to combine market-sizing discipline with tactical moves that lock in feedstock security, accelerate sustainable innovation, and protect margin. PW Consulting’s Worldwide Cellulose Derivative Market delivers the playbook and the data you need to act with conviction.
For detailed analysis of this topic, please visit the official page: Worldwide Cellulose Derivative Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com