

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Thermoset Molding Compounds Market to Reach USD 15,995 Million by 2032 at 5.14% CAGR — Asia Pacific Leads with USD 5,167.8 Million in 2025

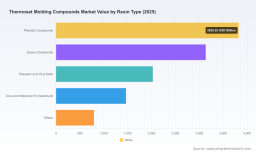
Worldwide Thermoset Molding Compounds Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As global manufacturing recalibrates for electrification, sustainability mandates, and supply‑chain resilience, thermoset molding compounds are reclaiming attention as engineering materials that straddle cost, performance and compliance imperatives. Our new Worldwide Thermoset Molding Compounds Market report — building on a 2020–2025 historical baseline with 2025 as the base year and a 2026–2032 forecast horizon — shows an industry at an inflection point. The market reached USD 11,250.5 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 5.14% over the forecast period, reaching roughly USD 15,995 Million by 2032. This briefing explains why the study is a practical decision‑support tool for corporate leaders planning capital allocation, product strategy, regulatory compliance and M&A in 2026.
Worldwide Intelligent Customer Engagement Market
Why this report matters to 2026 strategic cycles
-
Actionable foresight for investment timing — We translate multi‑scenario topline projections into pragmatic timing guidance for capacity expansion, tooling investments and supply agreements so firms avoid the twin risks of overcapacity and missed uptake windows tied to EV, aerospace and renewable energy programs.
Worldwide Well Completion Equipment and Services Market -
Procurement and raw material stress testing — The report integrates upstream price and margin sensitivity analyses to quantify how feedstock volatility (phenol, formaldehyde, fillers) and regional pricing disparities can erode compounder margins and shift supplier economics across realistic procurement scenarios.
Worldwide Gram Flour Market -
Regulatory compliance and product design trade‑offs — With new formaldehyde limits and emissions testing regimes in multiple jurisdictions, our guidance helps R&D and product management teams prioritize low‑emission chemistries and validate lifecycle claims without jeopardizing manufacturability.
-
Competition and partner selection playbook — We provide a concise diagnostic of incumbent and challenger strategies, capability maps, and supplier archetypes to fast‑track sourcing, co‑development and white‑labeling decisions.
Executive snapshot: market structure and competitive intensity
The thermoset molding compounds market exhibits moderate concentration: the top three suppliers account for a meaningful share of industry revenue, and the five largest players control a nearly half share of the market. That structure creates predictable advantages for large formulators — scale in R&D, global distribution and custom compounding — while leaving material opportunity for agile specialists to capture niche premium segments through innovation or service differentiation. For 2026 planning, this suggests a two‑track strategic posture: defend core portfolios via operational excellence and scale partnerships, while selectively investing in proprietary chemistries or adjacent value chain moves that unlock margin or regulatory advantage.
Key trends reshaping vendor and buyer strategies in 2026
-
Sustainability and circularity are no longer optional. Breakthroughs in recyclable thermoset technologies and bio‑based resins have moved from labs into commercial launches. Companies that can demonstrate credible end‑of‑life solutions and lower embodied carbon will command premium positioning in OEM RFQs, especially for electrified transport and aerospace components.
-
Low‑emission formulations are accelerating adoption. Regulators have tightened thresholds for formaldehyde emissions in both workplace and consumer contexts, prompting green reformulation and third‑party emissions validation as standard procurement requirements for many OEMs.
-
Raw material volatility continues to drive margin compression for resin‑dependent producers. Price swings in phenol and formaldehyde supply chains materially affect compounder margins and necessitate dynamic pricing clauses, hedging strategies and supplier diversification programs.
-
Customer requirements are more application‑specific. Demand is migrating toward bespoke formulations (thermal management, flame retardance, electrical insulation) rather than commodity blends — favoring producers with strong compounding expertise and collaborative development models with OEMs and Tier‑1s.
Recent industry moves worth watching
-
Leading global chemical manufacturers have launched next‑generation formulations that emphasize recyclability, reduced VOCs and bio‑based constituents. These launches represent not only technological progress but also a reframing of value propositions from 'material cost' to 'systems cost' — including end‑of‑life processing and compliance burden.
-
Compounders and converters are responding with investment in analytical testing, low‑emission processing lines and closer downstream integration to capture higher value in electrical and transportation applications. Expect to see a wave of co‑development agreements, targeted plant upgrades and selective joint ventures in 2026.
-
Upstream pricing trajectories and regional supply constraints remain a tactical concern for Q1–Q3 2026 sourcing strategies; our scenario models quantify the profitability impacts across common contract structures and recommended mitigation levers.
Competitive landscape: capabilities that win
Across the supplier universe, three capability clusters are decisive for market success in 2026:
-
Formulation leadership — Proven track records in high‑performance phenolic, epoxy and unsaturated polyester systems, combined with rapid prototyping and qualification pipelines for OEMs, remain a primary differentiator. Companies with specialized brands and proprietary chemistries are better placed to command technical premiums.
-
Manufacturing footprint and custom compounding — Global presence and flexible compounding capacities enable shorter lead times and local compliance support for multinational customers. Firms offering on‑site technical service and localized inventory strategies reduce total cost of ownership for buyers.
-
Application focus — Sellers that combine core thermoset competencies with deep applications know‑how in automotive electrification, electrical insulation, and aerospace-grade performance capture outsized share in high‑value segments.
Major players occupy complementary positions across these clusters — from global formulators with diversified product portfolios to regional specialists with tight application focus. For decision‑makers, the actionable insight is to map supplier selection to strategic priorities (price, sustainability credentials, technical support) rather than defaulting to legacy sourcing relationships.
What the report delivers — practical content for 2026 execution
-
Topline and scenario forecasts (2026–2032) with demand drivers by end‑use and resin architecture — presented as actionable investment and supply‑chain scenarios rather than raw tables.
-
Supplier diagnostic dossiers — capability maps, strategic risk profiles, and partnership fit assessments for established and emerging players.
-
Raw material pricing analytics and margin sensitivity models — enabling procurement teams to test contract structures and hedging approaches under alternative price paths.
-
Regulatory impact matrices — side‑by‑side comparison of major market jurisdictions and recommended compliance pathways for formulation and plant operations.
-
Commercial playbooks — tailored for OEMs, Tier‑1 suppliers and compounders on pricing mechanics, specification negotiations and value‑capture tactics via product differentiation or integrated services.
-
M&A and partnership screening framework — prioritize targets and partnership types that accelerate route‑to‑market for sustainable and functional resin platforms.
Recommended strategic moves for 2026
-
For compounders: prioritize fast‑follower investment in recyclable and low‑VOC chemistries while securing multi‑tier supply agreements to buffer phenol/formaldehyde volatility. Pilot commercial collaborations with OEMs to embed new materials into specification roadmaps.
-
For OEMs and Tier‑1s: re‑evaluate total lifecycle costs and procurement scorecards to favor suppliers that provide validated emissions performance and end‑of‑life solutions. Use staged qualification programs to accelerate adoption of bio‑based and recyclable thermosets.
-
For investors and acquirers: target specialty formulators and converters with strong margin profiles and differentiated R&D assets, particularly those that can be scaled geographically to meet electrification and insulation demands.
-
For regulators and standards bodies: adopt harmonized emissions testing and reporting frameworks to reduce market fragmentation and enable verifiable sustainability claims.
How PW Consulting’s analysis de‑risks 2026 decisions
Our approach combines granular commercial intelligence with macro forecasts and practical playbooks. The report translates volatility and regulation into quantified scenarios and prescriptive actions: which investments to accelerate, which supplier relationships to renegotiate, and which product bets to defer. By integrating supplier capability maps with demand elasticities and regulatory thresholds, we give clients a prioritized roadmap to protect margins, meet compliance, and capture growth in higher‑value applications.
Next steps — where to get the full intelligence
This preview highlights the strategic capabilities and directional market metrics central to 2026 planning. To access the complete dataset, including the full suite of subsegment forecasts, regional dynamics, and the supplier benchmarking model that underpins our recommendations, please visit the official report page. The full report contains the proprietary subsegment detail and primary‑source interviews necessary for precise contract negotiation, plant justification and M&A valuation in 2026.
PW Consulting analysts are available for tailored briefings and scenario workshops to convert these insights into executable 12–36 month plans aligned with your organization’s risk‑return profile.
For detailed analysis of this topic, please visit the official page: Worldwide Thermoset Molding Compounds Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com