

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Soil Fumigant Market at USD 842.5 Million in 2025; Set to Grow at 4.62% CAGR to USD 1,154.2 Million by 2032

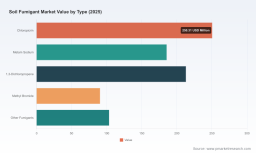
PW Consulting Releases Strategic Brief: Worldwide Soil Fumigant Market — A 2026 Playbook for Leaders
PW Consulting’s new market research brief on the Worldwide Soil Fumigant Market synthesizes five years of historical performance and a multi‑scenario forecast to 2032, delivering the actionable intelligence required by agribusiness leaders, investors, and policy makers as they set strategy for 2026. Built on a 2025 base year and a comprehensive 2026–2032 outlook, the study quantifies an industry evolving under regulatory pressure, supply‑chain shifts, and changing on‑farm application economics. The global market is projected to grow at a 4.62% CAGR through the forecast period — a trajectory that takes aggregate industry revenue from the mid‑hundreds of millions in 2020, into the high hundreds by 2025, and toward a substantially larger market by the early 2030s.
Disposable Wearable Thermometer Market
Why this brief matters for 2026 decisions
- Timing of strategic moves. 2026 will be an inflection year for companies that need to balance near‑term compliance costs with medium‑term growth investments. The brief maps regulatory milestones and provides decision windows for product reformulation, application‑method investment, and regional go‑to‑market prioritization.
- Risk‑adjusted portfolio planning. Using scenario modeling, the report quantifies upside and downside outcomes across alternative regulatory and raw‑material price paths, enabling CFOs and business unit leaders to stress‑test portfolios and capital plans.
- M&A and partnership playbook. Consolidation activity and distributor‑specialist deals are reshaping access to application capability and channel reach. The brief offers an M&A screening framework specific to soil fumigants — value drivers, integration risks, and a short list of tactical deal archetypes appropriate for 2026.
- Operational compliance and adoption economics. Grower economics are changing as new application restrictions and buffer requirements are enforced. The study includes practical on‑farm cost models and an ROI matrix for alternative application technologies and service‑based business models.
What’s in the report — practical, execution‑oriented modules
- Executive summary with an independent market-size trajectory and a clear statement of the report’s assumptions (base year 2025; historical 2020–2025; forecast 2026–2032; currency USD, revenue unit: Million).
- Regulatory risk matrix that translates evolving federal and state rules — including reregistration requirements, application time‑windows, and buffer‑zone regimes — into probability‑weighted impact scenarios for product demand and application methods.
- Raw‑material and input cost sensitivity analysis mapping specialty chemical upstream dynamics (notably intermediates used in DMDS and chloropicrin supply chains) to finished product margins.
- Competitive and channel playbooks: distributor economics, applicator capability maps, and brand positioning approaches for market entrants and incumbents alike.
- Commercial due‑diligence toolkit and valuation levers for M&A, including synergy estimates, integration checklists, and red‑flag watchlists specific to fumigant assets.
- Field‑level adoption models and mechanization scenarios illustrating the economics of shank versus drip application, pre‑plant timing constraints, and the business case for service‑based application offerings.
- Strategic recommendations for growers, from integrated pest management (IPM) integration to alternative chemistries and non‑chemical rotations designed to preserve long‑term field productivity.
Competition and market structure — what leaders must know
The market exhibits meaningful concentration: the top three firms control a significant portion of the market, and the top five account for well over half. This structure creates both competitive pressure and opportunity: large global players can scale compliance investments and R&D, while specialty manufacturers and regional distributors can differentiate through service, local registration agility, and formulation niches.
Worldwide 4K Cinema Projectors Market
Key corporate profiles and strategic implications analyzed in the brief include:
Air Cables Market
- Corteva Agriscience (Indianapolis, USA) — Leverages a broad crop‑protection platform and retains technical expertise in legacy product lines and alternatives. Strategy considerations include repositioning legacy soil fumigant IP into integrated solutions and accelerating delivery of lower‑risk application packages.
- UPL Ltd. (Mumbai, India) — A high‑velocity supplier across multiple regions; competitive advantage lies in channel reach across Asia‑Pacific and in cost discipline. The brief evaluates UPL’s potential to consolidate regional niche offers into scale advantages.
- BASF SE (Ludwigshafen, Germany) — Offers breadth in crop protection; its strength is product bundling and formulation know‑how, which can be leveraged to provide differentiated mitigation packages for nematode and pathogen control.
- Arkema S.A. (Colombes, France) — A leader in DMDS‑based solutions; upstream specialty chemistry exposure makes Arkema sensitive to feedstock dynamics but also positions it to innovate on application modes for horticulture and high‑value crops.
- TriEst Ag Group / TriCal Group (USA) — The 2025 acquisition of a legacy 1,3‑D line illustrates the growing strategic role of distributors/applicators that combine application capability with product ownership. This transaction underscores a shift toward vertically integrated service models.
- AMVAC Chemical Corporation (USA) — Focused product portfolio with strengths in specific chemistries and a strong position in metam sodium formulations.
- ADAMA, Syngenta, FMC, Gowan/Isagro, Tessenderlo, LANXESS, Detia Degesch, Trinity, Draslovka — Each of these players brings either formulation capability, channel access, or geographic strengths. The brief contrasts their strategic options: invest in lower‑risk chemistries, expand applicator partnerships, or pursue bolt‑on acquisitions to secure distribution paths.
Regulatory and operational headwinds
Regulatory developments remain the dominant near‑term driver of demand mix and application economics. The study synthesizes publicly reported policy movements — including ongoing reregistration decisions and state‑level mitigations — to create a forward map of compliance costs and likely adoption pathways. Practical takeaways include the operational impact of time‑of‑day and application‑method restrictions, the narrowing of methyl bromide uses under international phase‑out frameworks, and the incremental costs of buffer and monitoring requirements that affect grower willingness to pay for professional application services.
Supply chain and raw materials — volatility risk and opportunity
Upstream specialty chemical availability and pricing, especially for intermediates used in DMDS and chloropicrin production, create both margin risk and strategic entry points. The report quantifies how shifts in specialty chemical production capacity can affect finished‑good economics and highlights sourcing strategies — dual‑sourcing, toll production, and backward integration — that materially change risk exposure.
Strategic playbook for 2026
- Short‑term (next 12 months): Prioritize regulatory gap assessments and update commercial contracts to reflect likely application windows and buffer constraints. Reallocate capex to ensure compliance and continuity of supply.
- Medium‑term (12–36 months): Invest in service models that bundle product supply with certified application; pursue targeted M&A to secure applicator networks; accelerate development or licensing of lower‑exposure formulations.
- Long‑term (36+ months): Build resilience through formulation diversity, integrate digital agronomy tools that reduce reliance on high‑risk chemistries, and create pathways to non‑chemical crop protection where commercial yields and margins permit.
Market concentration and M&A outlook
Consolidation dynamics are already visible: significant asset transactions and exits by legacy chemical companies are creating openings for specialist operators and distributors that can deliver application capability at scale. The brief’s M&A framework provides valuation multiple adjustments that reflect regulatory risk, channel ownership, and applicator footprint — essential inputs for any 2026 transaction plan.
Concluding recommendation and next steps
For executives making 2026 strategic choices, the critical question is not whether the market will change — it will — but how to position capital, capabilities, and partnerships to capture resilient value amid regulatory and supply variability. PW Consulting’s Worldwide Soil Fumigant Market brief supplies the decision‑grade analysis and executable playbooks needed to set a confident path forward.
To preserve competitive advantage and comply with the “trailer” principle of this release, detailed segment tables, region‑and‑application breakout figures, and the full suite of proprietary scenario outputs are available in the full report. Access to the complete dataset, company scorecards, and the M&A target list is available via the PW Consulting report page.
For detailed analysis of this topic, please visit the official page: Worldwide Soil Fumigant Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com