

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Mining Truck Unmanned Driving System Market Poised to Grow at a 17.55% CAGR Through 2032

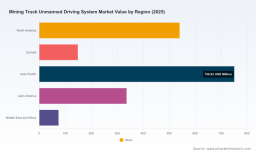
Mining Truck Unmanned Driving System Market: Strategic Imperatives for 2026 – PW Consulting Report Preview
PW Consulting’s latest market study on Mining Truck Unmanned Driving Systems (base year 2025) arrives at a pivotal moment for mining operators, OEMs, technology suppliers and infrastructure investors. The global market, estimated at approximately USD 1.85 billion in 2025, is forecast to expand at a compound annual growth rate (CAGR) of 17.55% across the 2026–2032 horizon, reaching roughly USD 5.72 billion by 2032. This preview highlights the report’s strategic value for decisions in 2026, outlines the practical modules inside the full study, and summarizes competitive and regulatory dynamics that will shape early-mover advantage in unmanned haulage.
Aerial Target Services Market
Why this report matters for 2026 strategic decisions
-
Acceleration window: With near-term growth at double‑digit rates, 2026 is the inflection year for converting pilot projects into commercially scaled unmanned fleets. Operators weighing capital allocations need a clear, data-driven deployment sequencing and payback analysis — which is a core deliverable of the full report.
Mini Power Bank Market -
Oligopolistic concentration: Market concentration remains material, with top vendors dominating the installed base. For vendors and buyers alike, this implies concentrated negotiation power, but also opportunities for niche suppliers and retrofit service providers to capture share through partnerships and differentiated technical value propositions.
Soil Conductivity Meters Market -
Electrification and labor economics: Commercial deployments of pure-electric unmanned haul trucks have demonstrated dramatic reductions in on-site labor costs — reported in excess of 88% in some operational cases. The convergence of autonomy and electrification materially reshapes TCO modeling and total mine system design.
-
Regulatory and standards gating: Adoption trajectories will be constrained or accelerated by safety and interoperability frameworks. ISO 17757 still governs safety requirements for autonomous earth‑moving systems while ISO 23725 (2024) is increasingly referenced for interoperability between autonomous systems and fleet management layers. Regional codes of practice (for example, jurisdictions with dedicated autonomous mining guidance) further shape deployment timelines and compliance costs.
-
Environment and component engineering: Extreme environment requirements — such as reliable operation down to −40°C — impose special sensor heating, battery adaptation, and materials selection. These engineering constraints create supplier specialization opportunities that can materially affect reliability and lifecycle costs.
What the full PW Consulting report delivers (executive tools and templates)
-
Actionable market model: A transparent top‑down and bottoms‑up revenue model spanning 2020–2032, with scenario analysis (base, accelerated, constrained) and sensitivity levers to test commodity price, CAPEX availability, and regulatory timelines.
-
Deployment playbooks: Step‑by‑step implementation guides for pilot, scale-up and full‑fleet conversion, covering retrofit kits versus OEM autonomous trucks, procurement contract templates, and phased CapEx/Opex scheduling.
-
TCO and ROI calculators: Configurable templates that allow finance teams to compare lifecycle costs for retrofit and OEM pathways, incorporating electrification, energy pricing, maintenance differentials and labor substitution effects.
-
Risk & compliance matrix: A mapped matrix of safety standards, regional codes of practice, and practical mitigation plans to de‑risk regulatory approval and insurer engagement.
-
Technology readiness assessment: Comparative evaluation of sensor architectures (camera-only, LiDAR, radar, fusion), fleet orchestration platforms, and 5G/edge connectivity strategies for high-throughput open‑pit versus constrained underground use cases.
-
Procurement and partner scorecards: Vendor evaluation frameworks and negotiation playbooks tailored for mining OEMs, systems integrators and retrofit kit suppliers. These include KPIs, milestone‑based payment structures and SLA templates focused on safety, availability and maintainability.
-
Operational case studies: Deep dives into commercial deployments that document realized benefits, unexpected operational issues, maintenance regimes, and lessons learned on human‑machine transition strategies.
Competitive landscape — capabilities and strategic moves to monitor
-
Caterpillar Inc. — A global incumbent with a mature autonomous hauling platform (Cat MineStar Command). Caterpillar’s value rests on integrated OEM systems, established safety records and a sizable installed base that reduces adoption risk for large operators seeking turnkey offerings.
-
Komatsu Ltd. — A long‑standing player in autonomous haulage with its FrontRunner AHS and extensive field experience since commercial introductions in the 2000s. Komatsu combines OEM vehicle engineering with fleet orchestration, appealing to customers seeking end‑to‑end solutions.
-
CiDi Inc. (Changsha Intelligent Driving Research Institute) — A rapidly scaling provider specializing in Level 4 mining truck autonomy with pure-electric and hybrid offerings. The company has demonstrated aggressive commercialization, including recent large contract awards and fleet deliveries that underscore China’s fast‑moving adoption curve.
-
Pronto.ai — An OEM‑agnostic AHS supplier focusing on flexible sensor suites (camera-only and multi‑sensor) and software that can retrofit existing fleets. Strategic acquisitions have expanded its sensor and perception capabilities, positioning it as a high‑agility partner for quarries and smaller mines.
-
Hitachi Construction Machinery , Liebherr Group , XCMG , and Zoomlion — Each brings differentiated strengths in OEM truck manufacturing, electrified platforms and localized fleet partnerships. These firms are strengthening product roadmaps and collaborating with systems integrators to deliver full‑stack solutions.
Recent industry developments to factor into 2026 planning
-
Commercial 5G‑enabled deployments: The launch of large 5G-autonomous electric truck fleets demonstrates connectivity‑first approaches at scale and signals new expectations for on‑site network infrastructure planning.
-
Large-volume contracts and fleet deliveries: Multiple recent announcements indicate a maturing pipeline of procurement activity, from multi‑hundred‑unit contracts to aggregated fleet orders, which will affect supplier capacity and lead times.
-
M&A and consolidation among autonomy software suppliers: Strategic acquisitions are accelerating capability aggregation (perception stacks, fleet orchestration, and safety validation), raising the bar for independent software vendors to remain competitive without partner strategies.
-
IP and retrofit innovation: Patent activity around conversion kits and autonomy‑as‑a‑service models suggests new go‑to‑market options for converting legacy fleets, lowering the entry barrier for mines not ready to invest in new OEM vehicles.
Practical guidance — how executives should use this study in 2026
-
Prioritize pilot economics, not just capability. Use the report’s ROI models to select pilots that validate the full value stack (autonomy + electrification + smart maintenance), not just single technology milestones.
-
Lock in component supply chains for critical subsystems (sensors, thermal solutions for batteries, ruggedized communications). Lead times and specialization for cold‑weather adaptations can make or break winter‑season rollouts.
-
Define a retrofit vs OEM decision rule-set. The PW Consulting playbooks show when retrofit kits are financially preferable and when integrated OEM vehicles are necessary to achieve performance and safety targets.
-
Embed standards compliance early. Map program milestones to ISO 17757 and ISO 23725 considerations and secure early engagement with local regulatory authorities to compress approval cycles.
-
Consider strategic partnerships with software and telecom providers for edge/5G solutions. Connectivity strategy is a strategic capability that affects uptime, data ownership and operating margins.
Next steps — where to find the full intelligence
This preview outlines the decision‑centric insights and tangible tools included in PW Consulting’s full Mining Truck Unmanned Driving System Market report. The complete study contains the granular segmentation, regional and application-level forecasts, supplier benchmarking matrices, downloadable financial models, and procurement templates that senior teams will need to finalize 2026 budgets and procurement roadmaps. To preserve the commercial integrity of our benchmarking and avoid reproducing sensitive segmentation tables in advance, those datasets are available only within the full report and companion data pack.
Contact PW Consulting to arrange a briefing with our mining autonomy practice and to secure access to the complete report, interactive models, and a tailored strategy session that aligns our findings to your 2026 investment priorities.
For detailed analysis of this topic, please visit the official page: Mining Truck Unmanned Driving System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com