

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Military Helmet-Mounted Displays Market Set to Hit USD 4.88 Billion by 2032, Growing at an 8.15% CAGR

Strategic Briefing — Worldwide Military Helmet Mounted Displays Market: A 2026 Playbook for Defense Executives
Executive summary
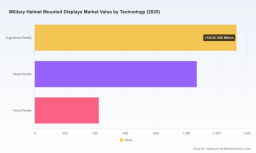
As nations and prime contractors accelerate investment in cockpit and helmet-integrated situational awareness, the military Helmet Mounted Displays (HMD/HMDS) market is entering a phase of durable growth and technological consolidation. PW Consulting’s latest market study (base year 2025, forecast 2026–2032) projects continued expansion at a compound annual growth rate of 8.15%. The market’s total reported size reached roughly USD 2.82 billion in 2025 and, under our central case, is expected to approach USD 4.88 billion by 2032.
Worldwide Workplace Innovation Platforms Market
This briefing synthesizes the report’s most consequential insights for 2026 strategic decision-making—identifying where procurement officers, systems engineers, OEMs, and equity investors should allocate scarce capital and management attention over the next 12–18 months. It deliberately signals high‑value levers and risk vectors while preserving the granular segmentation and supplier-level data contained in the full report—designed to lead teams straight to the source for purchase and implementation-ready intelligence.
Worldwide Multi-Country Payroll Software Market
Market trajectory and what it means for 2026 plans
After a steady recovery and expansion in the early 2020s driven by fighter, rotary, and dismounted soldier modernization, the HMD market is now maturing into a technology-infused procurement market. Growth is supported by intensifying demand for augmented- and mixed-reality capabilities, avionics modernization programs, and modular helmet platforms that can accommodate multiple display ecosystems.
Vertical Centrifuge Tube Market
For 2026, the strategic takeaway is clear: organizations must plan for multi-year acquisition cycles and integration programs that outlast individual platform upgrade contracts. Short-term contracting opportunities will be plentiful, but strategic advantage will accrue to actors that align product roadmaps, supply chain resilience, and regulatory compliance in a single programmatic plan.
High‑value strategic implications (actionable for 2026)
- Prioritize modularity and interoperability: Require helmet and HMD designs that support plug-and-play microdisplays, standardized sensor interfaces, and common data buses to reduce lifecycle costs and obsolescence risk.
- Accelerate supply chain localization where practical: Tariff pressures and component concentration on specialized microdisplays and optics increase program risk. By 2026, buyers who secure secondary sourcing and localized assembly options will reduce schedule and cost exposure.
- Embed export-control planning in program design: Export restrictions and defense procurement policies materially affect release schedules for allied customers—design contracts and delivery timelines to accommodate ITAR/EAR and partner-country certification processes.
- Invest in software ecosystems and sustainment: Integrated software—sensor fusion, AR symbology, and health monitoring—drives differentiation. Allocating budget to software sustainment and certified integration testing yields outsized operational returns.
- Use staged procurement and risk-sharing contract structures: Consider IDIQ/LOT frameworks and option lines keyed to maturity gates (e.g., airworthiness milestones) to preserve flexibility without sacrificing scale economics.
Competitive landscape: capabilities and implications
The vendor field is anchored by a mix of large aerospace primes, specialized optics and display suppliers, and integrators focused on avionics and soldier systems. Key players include established avionics and defense primes with in‑house helmet integration capabilities, specialist helmet manufacturers selected for next-generation fixed-wing programs, and microdisplay component suppliers whose roadmaps determine the performance ceiling for future HMDS iterations.
- Collins Aerospace (via a strategic joint venture) and Elbit Systems: Their partnered solutions remain central to advanced fighter HMDS programs, offering integrated sensor fusion and high‑resolution bi‑ocular designs. Recent program awards and continued airworthiness activity confirm their role as program anchors for advanced jet platforms.
- BAE Systems and Thales: Both provide digital helmet systems targeted at wide-field-of-view color displays with integrated NV capabilities. Their roadmaps and retrofit offerings are influential in multi‑platform modernization programs and interoperability efforts with allied air forces.
- Gentex Corporation: Selected for next‑generation fixed‑wing helmet efforts, Gentex’s helmet shells and fitment systems are becoming a procurement bottleneck—helmet hardware selection increasingly determines system integration paths.
- Kopin Corporation and other microdisplay specialists: Suppliers of AMLCD and OLED microdisplays remain a critical node. Contract awards for microdisplay supply and avionics integration underscore how component-level innovation enables whole-system capability uplifts.
- L3Harris and Honeywell: They focus on night-vision fusion and aircraft avionics integration; their offerings appeal where degraded-visibility and multi-sensor fused symbology are mission-critical.
Taken together, the market is concentrated toward a handful of integrators with close OEM and prime relationships. Competitive advantage in 2026 will flow to organizations that can tie hardware platforms to validated software ecosystems and secure resilient component supply lines.
Supply chain, regulation and raw‑material dynamics
Manufacturing of helmet-mounted displays depends on a narrow set of specialized components—microdisplays, precision optics, inertial and optical trackers, and advanced sensors. The sector faces three interlocking structural risks:
- Component concentration: A limited pool of microdisplay and optics suppliers creates single-source risk for many programs.
- Policy friction: Increases in tariffs and shifting export-control regimes have prompted visible production relocation and supplier qualification programs, increasing near-term costs but reducing medium-term geopolitical risk.
- Procurement complexity: Defense acquisition cycles and partner-country certification processes introduce schedule variability that buyers must account for in contracting and acceptance testing.
Mitigation strategies we detail in the report include dual-sourcing templates, supplier development programs, component stockpiling models calibrated to obsolescence curves, and program-level provisions for export compliance and partner training.
What PW Consulting’s report delivers to practitioners
The report is structured to be operational from day one. It contains market-sizing and forecast models, but more importantly it offers the tools decision-makers need to act:
- Executive playbooks for procurement officers and primes, showing contracting architectures, milestone checklists, and acceptance-test regimes tied to airworthiness and soldier-suit integration.
- Supply-chain resilience blueprints that prioritize which components to insource or dual-source, and how to stage inventory investments across program phases.
- Technology roadmaps that map microdisplay roadmap inflection points to program upgrade windows and software release cadences.
- Vendor evaluation frameworks and a decision matrix for helmet vs. HMD integration trade-offs, including TCO models and sustainment cost projections.
- Scenario analyses and stress tests (supply disruption, regulatory tightening, accelerated platform lifecycles) to stress procurement plans and budget contingencies.
To respect our 'prequel' principle, the public summary demonstrates methodology and strategic insights while withholding vendor-level market share tables and region/application breakdowns. These detailed matrices are included in the full report and are essential for final bid/no‑bid decisions and competitive benchmarking.
How buyers, primes, and investors should use this intelligence in 2026
- Procurement & program offices: Use the report’s contracting playbooks to convert intent into executable multi-year contracts that include options for technology refresh and allied support.
- Systems integrators and OEMs: Re-evaluate platform roadmaps against the microdisplay and sensor roadmaps included in the report; re-prioritize engineering sprints to deliver validated integration of AR/MR capabilities within existing certification gates.
- Supply-chain managers: Implement the supply resilience templates and supplier qualification timelines to minimize schedule slippage from component scarcity and regulatory friction.
- Investors & strategy teams: Apply the scenario analyses to assess acquisition targets, identify attractive vertical-integration opportunities, and size the addressable aftermarket for sustainment and software upgrades.
Recent market signals to watch in 2026
Program awards and test milestones announced in late 2025 and early 2026 confirm where demand and integration effort will concentrate in the near term. Key signals include continued Navy and Air Force helmet integration programs entering production qualification, microdisplay contracts for rotary- and fixed‑wing platforms, and selection of next‑generation helmet shells for fleet modernization. Each of these moves shortens delivery timelines and tightens supply chains—underscoring the practical need for the risk and procurement playbooks contained in the full study.
Next steps
For teams preparing 2026 budgets and program plans, PW Consulting’s Worldwide Military Helmet Mounted Displays Market report is designed as both a strategic compass and an operational manual. To unlock the vendor-level matrices, scenario models, and the procurement playbooks referenced here, visit PW Consulting’s report page and request the full dataset and briefings tailored to your organization’s role (buyer, prime, supplier, or investor).
Any team that needs to make procurement, investment, or integration decisions in 2026 should treat this report as an immediate priority: it translates megatrends into executable steps, highlights where program schedules are brittle, and prescribes concrete mitigations that preserve capability while reducing schedule and cost risk.
For detailed analysis of this topic, please visit the official page: Worldwide Military Helmet Mounted Displays Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com