

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: OLED Vapor Deposition Materials Market to Grow at 17.02% CAGR, Driving Next-Gen Display Innovation

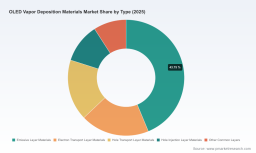
OLED Vapor Deposition Materials Market: Strategic Roadmap for 2026 Decision-Making
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a focused executive briefing drawn from our new market intelligence release: the OLED Vapor Deposition Materials Market report. Built for boards, corporate strategy teams, and lead investors, this briefing highlights the strategic implications of our findings for decisions you will face in 2026 — from capital allocation and supply‑chain hedging to R&D prioritization and partner selection.
Superhard Materials for Cutting Tools Market
Market trajectory: a high‑growth, consolidating landscape
Our modelling — based on historical data (2020–2025) and a seven‑year forecast (2026–2032) — shows a market that has shifted from niche to scale. The global revenue base rose steadily through 2025 and is projected to expand at a compound annual growth rate (CAGR) of approximately 17.0% across the 2026–2032 forecast horizon. In concrete terms, the overall market moves into a multi‑billion dollar phase by the end of the decade, underscoring both volume growth and increasing value capture across material formulations and deposition technologies.
Halogen-Free Modified Polyolefin (HF-MPO) Market
Two structural dynamics are driving this expansion: (1) continued penetration of OLEDs into higher‑end smartphones, televisions, and automotive/IT displays and (2) technology shifts in deposition methods, materials chemistry, and manufacturing scale that favor specialized suppliers and materials IP. The market is simultaneously maturing — with a meaningful share held by leading suppliers — and fragmenting in pockets, particularly where regional vertical integration and domestic champions are emerging.
Lanthanum Hexaboride Disc Market
Why 2026 is an inflection year
- Capacity and capital cycles: Several new AMOLED fabs are coming online or scaling in 2025–2026. That creates discrete windows for long‑term supply contracts and for firms to secure preferred supplier positions.
- Technology divergence: Traditional vacuum thermal evaporation remains the dominant route for high‑performance small‑molecule stacks, while alternatives (high‑throughput dry printing and other high‑deposition‑rate methods) are approaching commercial readiness. Strategic R&D and piloting decisions made in 2026 will determine who captures the next wave of incremental margin.
- Regulatory and sustainability pressure: Energy‑intensive vacuum processes and supply‑chain concentration around certain raw materials are inviting regulation and corporate sustainability programs. Firms that can present credible decarbonization and recycling strategies for OLED materials will gain buying preference and reduce regulatory risk.
Practical value of the full PW Consulting report for 2026 choices
- Actionable demand scenarios: Our report includes demand‑cascade models that translate panel fab plans into material tonnages and spend trajectories under multiple adoption curves and technology share assumptions. These scenarios let procurement teams test contract tenors and price escalator clauses against realistic upside and downside cases.
- Commercial supplier maps and risk scoring: We provide a validated supplier map, manufacturing footprints, capacity delta analysis, and a proprietary supplier risk index that quantifies concentration, geopolitical exposure, and substitution risk — enabling negotiation teams to prioritize counterparties and mitigation levers.
- Techno‑economic profiles of deposition routes: A side‑by‑side evaluation of vacuum thermal evaporation, advanced evaporators, and emerging dry‑printing alternatives (including capital intensity, throughput, materials compatibility, and relative energy footprint) enables capex committees to compare ROI across factory architectures.
- IP and materials roadmaps: The report synthesizes emitter, host, and transport‑layer innovation trajectories and maps them against patent landscapes and licensing models — crucial when weighing in‑house development vs. long‑term supply relationships with IP holders.
- Negotiation playbooks and commercial templates: For commercial leaders, we include term sheet templates, price‑indexation approaches tailored to volatile raw inputs, and contract clauses that protect buyers and sellers in capacity ramp scenarios.
Competitive landscape: leaders, challengers, and the new entrants to watch
The market exhibits a concentrated core of technology and materials specialists, supported by vertically integrated conglomerates and an expanding set of regional players. Market concentration metrics indicate a high level of aggregation among the top few suppliers, but the boundary between “leader” and “challenger” is fluid — driven by IP portfolios, equipment partnerships, and targeted R&D investments.
- Universal Display Corporation (UDC): With established phosphorescent emitter IP and a mature commercialization model, UDC remains central for companies optimizing vacuum vapor deposition stacks. Its strategic pivot to scale alternative high‑deposition printing capabilities — and recent R&D realignment into Singapore — signals a dual approach: defend core licensing revenues while seeding next‑generation deposition channels.
- Merck KGaA: A materials and formulation powerhouse, Merck’s portfolio spans host, emitter, and transport chemistries designed for vacuum processes. Their strength lies in integrated material systems and supply reliability for large fabs that demand consistent, high‑purity inputs.
- LG Chem and Samsung SDI: These Korean suppliers combine materials expertise with downstream panel and device experience. Their vertical scope permits co‑development with panel manufacturers, influencing adoption curves in key OEM accounts.
- Idemitsu Kosan, Sumitomo Chemical, Hodogaya, JNC, Tokuyama, and others: These Japanese firms are differentiated by specialty chemistries — notably blue emitters and high‑purity intermediates — and have deep technical relationships with manufacturers that prioritize performance and lifetime.
- Materion and select Chinese suppliers: Suppliers in North America and China are expanding capacity and advancing materials purity or cost advantages. Chinese evaporation material producers are increasingly competitive on price and are challenging incumbents on selected account wins — a trend our report profiles with supplier‑level case studies.
Recent strategic and technology signals
- Equipment innovation: The introduction of advanced evaporators and angle‑controlled deposition solutions by key equipment vendors is improving pixel uniformity, efficiency, and material utilization rates. These equipment developments materially change the unit economics of material consumption and factory throughput.
- Alternative deposition methods: Movement of R&D vectors — such as Universal Display’s relocation of certain research into high‑deposition‑rate printing modalities — suggests that commercially viable alternatives to vacuum evaporation are being prioritized. Firms should consider staged pilot investments, co‑funded demos, or licensing deals to maintain optionality.
- Sustainability and supply stability: The industry’s energy profile and critical raw material dependencies (including specialty gases and electronic‑grade precursors) are driving both regulatory attention and corporate programs aimed at recycled and eco‑friendly material formulations. Expect procurement mandates and ESG scoring to increasingly influence supplier selection.
Key strategic implications for 2026 decision-makers
- Secure supply via layered contracts: Combine short‑term spot positions with medium‑term volume commitments and strategic partnerships. Use our scenario models to set contract tenors that balance upside participation with capacity guarantees.
- Invest in optionality, not all‑in bets: Rather than committing exclusively to one deposition technology, structure staged investments and conditional scaling clauses. Maintain pilot capacity across vacuum and emergent printing approaches until performance, yield, and lifetime parity are proven at scale.
- Position on sustainability: Integrate materials recycling pilots and energy‑efficiency KPIs into fab planning. Leadership on sustainability will be a differentiator with large OEMs and procurement committees that increasingly weight ESG criteria.
- Protect and leverage IP: For OEMs and materials firms, the strategic question is whether to acquire, license, or co‑develop. Our patent and licensing maps show where exclusive technologies are concentrated and where cross‑licensing could unlock differentiation without prohibitive cost.
- Hedge critical raw inputs: Identify and secure strategic sources for upstream precursors (including specialty silanes and evaporation‑grade compounds). Our supplier risk index helps prioritize suppliers for strategic stockpiling, dual‑sourcing, or equity partnerships.
- Monitor regional shifts: New entrant activity and domestic champions in certain regions may reshape competitive pricing and access. Maintain a watchlist and be prepared to adapt sourcing strategies as regional fabs scale.
What the report intentionally withholds here — and why you should read it
In line with our “prequel” approach, this briefing summarizes strategic takeaways but does not disclose granular regional or application splits and sub‑segment values that are core to operational procurement strategies. The full PW Consulting report contains the proprietary segment‑level forecasts, supplier revenue shares, unit‑consumption matrices, and deal‑level benchmarks that materially change negotiation posture and capital planning. If your 2026 supply strategy or capex approval depends on hitting specific cost or volume thresholds, those granular tables and models are essential.
Next steps for executive teams
- Request the full report and the underlying model: Use our interactive spreadsheets to stress‑test scenarios against your fabs’ ramp schedules and material usage profiles.
- Schedule a PW Consulting advisory workshop: We offer a condensed 2‑day strategic immersion for procurement, R&D and corporate development teams to convert the report’s findings into an execution roadmap.
- Initiate targeted supplier audits and pilot agreements: Use the buyer’s playbook and supplier risk scoring in our annex to prioritize counterparties for 2026 tenders and pilot co‑development programs.
OLED vapor deposition materials are at the intersection of chemistry, equipment, and manufacturing scale. In 2026, decisions made by C‑suite teams — concerning which technologies to pilot, which suppliers to lock in, and how to align sustainability with cost — will determine competitive positioning for the remainder of the decade. PW Consulting’s full market report equips leaders with the quantitative foundation and practical tools to make those calls with confidence.
Access the full OLED Vapor Deposition Materials Market report to obtain the segment‑level forecasts, supplier scorecards, and scenario models required to finalize your 2026 strategy.
For detailed analysis of this topic, please visit the official page: OLED Vapor Deposition Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com