

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Unbleached Wood Pulp Market Set to Expand at a 3.33% CAGR During 2026–2032, Report Finds

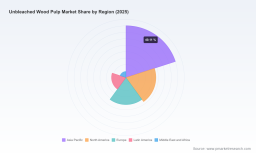
Worldwide Unbleached Wood Pulp Market — A Strategic Preview for 2026 Decision‑Makers
PW Consulting’s new market brief on the Worldwide Unbleached Wood Pulp (UKP) market is designed as a strategic “trailer” for senior executives, procurement leads, and M&A teams planning for 2026. The market reached roughly USD 10.45 billion in our 2025 base year and—assuming the central outlook—tracks to a compound annual growth rate (CAGR) of about 3.33% over the 2026–2032 forecast window, taking the market above the USD 13 billion mark by 2032. Those headline figures frame what follows: a market that is mature, structurally predictable in many demand vectors, but increasingly shaped by episodic raw‑material shocks, regulatory moves, and product differentiation among incumbents.
GNSS Location Chip Market
Why this report matters for 2026 strategy
- Actionable foresight: We translate demand and supply trajectories into discrete decision triggers for procurement, manufacturing, commercial and corporate development teams.
- Risk‑to‑reward mapping: A focused set of scenario templates demonstrates how raw‑material and regulatory shocks can shift margins and utilization within 6–18 months.
- Competitive playbook: We analyze strategic responses from leading players—product innovation, fiber partnerships, and integration—that materially alter supplier bargaining dynamics.
- Executable toolset: The study includes templates and models that can be dropped into operating and investment approval processes without re‑engineering.
Macro trajectory and demand drivers
The unbleached pulp market is anchored to the global packaging and industrial paper value chain—containerboard, kraft paper, bag and sack applications, plus a rising share of specialty end‑uses such as fiber cement and electrical insulation. After steady recovery in the early 2020s, the market’s base year position in 2025 reflects both structural demand for fibre‑based packaging and the continued substitution away from mixed recovered furnish in regions with tightened recycling standards.
Worldwide Harbour Dredging Market
Over the forecast horizon, the roughly 3.33% CAGR we model reflects a balance of moderating end‑market growth in developed regions and faster uptake in parts of Asia and Latin America where corrugated demand and construction activity remain supportive. Importantly, growth is not uniform: premium low‑kappa and high‑purity grades are gaining price and share versus commodity unbleached fibers, creating margin dispersion that matters for capital allocation and product strategy.
Smart Power Plant Controller (SPPC) Market
Supply‑side dynamics: raw materials, logistics and outages
Three supply themes dominate short‑term volatility and strategic positioning:
- Woodchip and pulp price oscillation. In 2025 China saw hardwood chip prices rise—lifting some integrated BHK (bleached hardwood kraft) production costs by about USD 50 per tonne between July and October 2025—and imported unbleached pulp prices in China strengthened through year‑end (SunSirs reported a daily average near CNY 5,075/ton as of Dec 31, 2025). These movements increase the value of stable, long‑term fibre arrangements and favour integrated or near‑integrated supply chains.
- Regulatory and trade policy tightening. Recent tightening of China Customs requirements for certain recycled pulp processes has pushed some containerboard producers to increase procurement of domestic wood pulps, including unbleached kraft lines—an operational pivot with immediate procurement and logistics implications.
- Geopolitical and licensing disruptions. License suspensions in Indonesia led to notable shortfalls early in 2026 (market reports quantify producer removals on the order of ~150,000 tonnes of BHK in Q1 2026), showing how regional regulatory actions can ripple through chip markets and re‑price imported market pulp flows.
For procurement and operations teams, those dynamics mean that 2026 will be defined by two complementary priorities: (1) active hedging of fibre exposure through diversified long‑term and spot strategies, and (2) investment in product differentiation—e.g., low‑kappa, high‑purity grades—that command resilience in tight markets.
Competitive landscape — what to watch
Concentration metrics show that the top three and top five suppliers capture meaningful, but not overwhelming, market share—indicating room for regional champions and specialised mill portfolios to exert pricing power in niche segments. In our analysis the three‑firm concentration hits the low‑to‑mid 30s percentage and the five‑firm concentration approaches the high 40s—an important datapoint when assessing the scope for consolidation or for vertically integrated players to adjust transfer pricing and internal allocation.
Several strategic behaviours stand out among the industry’s prominent players:
- Product portfolio segmentation. Firms such as Stora Enso are actively differentiating with low‑kappa “Nova” family grades targeted at higher‑value applications; Stora Enso’s February 2026 launch of Nova F for fiber cement and filtration underscores R&D translating quickly into commercial SKUs.
- Asset and fibre security. Recent transactions—Mondi’s 2024 acquisition of the Hinton Pulp mill with its long‑term local fibre partnership—illustrate the premium placed on mills with assured chip supply and favourable feedstock economics.
- Integration and market positioning. Large integrated producers (e.g., multinational containerboard groups and integrated pulp majors) are using their scale to capture more of the value chain, shifting how they allocate internal pulp to captive versus external markets.
- Regional champions and specialty suppliers. Companies with legacy strengths in softwood grades, or with mills capable of producing low‑kappa/high‑purity pulps, are selectively winning specialty channels—creating a bifurcated market between commodity supply and premium speciality grades.
What the report delivers — practical content for near‑term action
This is not a catalogue of numbers alone. PW Consulting’s report is structured as a toolkit for immediate operationalization:
- Executive dashboard: one‑page KPIs and stress indicators that update your procurement playbook under three price‑shock scenarios.
- Supply‑risk heatmap: regional supplier risk rankings that combine licence, weather, and logistics exposure into an actionable procurement score.
- Price sensitivity and margin model: a spreadsheet that shows operating margin impact across product mixes when chip or imported pulp moves by defined bands.
- CapEx and retrofit ROI calculator: model to evaluate converting a bleached line to low‑kappa unbleached grades or to add specialty finishing capacity.
- Commercial playbook: recommended contractual clauses, indexation approaches, and short‑term commercial levers for sellers and buyers of UKP.
- M&A and partnership playbook: target filters, due‑diligence checklists, and valuation overlays that reflect current concentration and fibre‑security premiums.
How to use these insights in 2026 decision‑making
Different corporate functions should extract distinct, immediate actions from the study:
- Procurement: re‑price and re‑negotiate long‑term fibre contracts using our scenario outputs; consider strategic forward purchasing where logistics friction and regulatory risk create premium on immediate availability.
- Supply chain: build contingency plans for regional outages (e.g., Indonesia licence impacts, typhoon seasons) and qualify alternative chip suppliers or spot pulp partners for rapid substitution.
- Manufacturing: prioritize upgrades that allow production of low‑kappa/high‑purity grades if you sell into fibre cement, filtration, or electrical insulation markets—these grades are accruing a structural premium.
- Commercial & Pricing: implement tiered pricing by grade purity and develop value‑capture mechanisms (minimum commitment terms, premium adders for short lead times, or bundled logistics services).
- M&A / Corporate Development: focus on assets with secure fibre supply or mills that can be repurposed to specialty grades; use our concentration analysis to calibrate consolidation synergies and regulatory risk.
- Finance: stress‑test forecasts to include realistic PPI shocks and import price moves—we document US Producer Price Index trends and China spot movements that should be embedded in 2026 budgets.
Risk watchlist — what could derail the base case
- Regulatory tightening in major exporting or importing jurisdictions (customs, environmental licensing) that re‑routes flows or effectively removes capacity.
- Raw‑material shocks, including hardwood chip price spikes, persistent shortages caused by weather or trade embargoes, and sudden changes to recycled furnish acceptance.
- Demand shocks associated with a deeper slowdown in durable goods or packaging if macro growth dips in key export markets.
- Rapid technological or process changes (e.g., disruptive recycling technologies) that alter the relative economics for unbleached vs alternative fiber sources.
- ESG and certification pressures that create stranded assets for mills unable to meet buyer‑imposed sourcing criteria.
Conclusion — the signal, not the full map
PW Consulting’s Worldwide Unbleached Wood Pulp Market brief gives 2026 decision‑makers the signals and executable templates to respond quickly to market movements. We provide the strategic framing—headline market size (base year ~USD 10.45 billion), a 3.33% CAGR through our forecast horizon, concentration context, and the operational playbooks required to move from insight to action. The report intentionally omits granular public disclosure of every regional and application split in this preview; detailed segment and regional forecasts, full supplier scorecards, and downloadable models are available in the full report.
To access the complete dataset, scenario files, and implementation templates that support the recommendations summarized here, please visit PW Consulting’s report page or contact our market team for a briefing and tailored extract aligned to your firm’s exposure and strategic objectives.
For detailed analysis of this topic, please visit the official page: Worldwide Unbleached Wood Pulp Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com