

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Medical Gas Manifold Market to Expand at a 5.45% CAGR in 2026–2032 Forecast

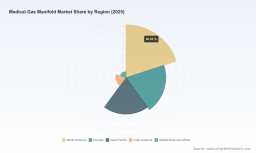
Worldwide Medical Gas Manifold Market — Strategic Outlook for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide Medical Gas Manifold Market provides a practical, decision-ready brief designed for executives who must translate technical standards, regulatory change, and capital planning into competitive advantage in 2026. Anchored to 2025 as the base year and projecting through 2032, the research combines financial forecasts, regulatory impact mapping, supplier benchmarking, and implementation playbooks — all tuned to the distinctive procurement cycles and risk profiles of hospitals, clinics and surgical centers.
Worldwide Back Office Automation Market
Executive snapshot: growth trajectory and structural profile
The market for medical gas manifolds has matured into a stable but strategically important niche within hospital infrastructure. After expanding steadily between 2020 and 2025, the global market stood at approximately USD 570 million in our base year. Our forecast through 2032 implies a compound annual growth rate of about 5.45%, reaching roughly USD 826 million by the end of the horizon. That trajectory reflects ongoing replacement and retrofit demand, the gradual modernisation of piped gas systems, and rising adoption of automated and smart manifold solutions.
Die Sinking Electrical Discharge Machine Market
Market concentration is meaningful but not prohibitive: the three largest suppliers capture a material share of installed revenues, and the top five consolidate over half of the market — a dynamic that shapes pricing power, certification strategies, and routes-to-market.
Micropipettor Market
Why this matters for 2026 corporate strategy
- Regulatory inflection: the introduction and enforcement of tailored cGMP requirements for medical gases (21 CFR part 213) and associated draft guidance have elevated quality expectations for manufacturing, cleaning, and qualification of manifolds. Compliance timelines and audit-readiness must be integrated into product and manufacturing roadmaps.
- Standards-driven procurement: ISO 7396-1, NFPA 99 and national HTMs remain the non-negotiable baseline for product acceptance in institutional tenders. Early certification reduces procurement friction and shortens sales cycles in regulated health systems.
- Capital intensity of installations: manifold supply is tightly coupled to larger piped gas projects. Decision makers evaluating product strategy or investment must factor multi-year CapEx cycles and the procurement realities of large hospital projects, which often involve bundled infrastructure contracts.
- Technology & service premium: automation, smart diagnostics and remote monitoring are emerging as high-value differentiators. Providers able to combine hardware with predictable service revenues will command premium valuations and stickier client relationships.
What the report delivers — practical content for immediate use
PW Consulting’s report is structured as an operational toolkit for strategy teams, commercial leaders, and M&A investors. It avoids abstract generalities and focuses on executable outputs:
- Market sizing and validated forecasts (base year 2025; forecast 2026–2032) with underlying assumptions and sensitivity scenarios.
- TAM/SAM maps with buyer personas, decision drivers and procurement cadences for hospitals, clinics and ambulatory surgical centers.
- Regulatory and standards matrix (global and jurisdictional) outlining compliance requirements, certification timelines and typical audit checkpoints for manifolds and associated equipment.
- Competitive benchmarking and supplier scorecards that assess product breadth, certification status, manufacturing footprint, and aftermarket capabilities — presented without disclosing proprietary client data.
- Commercial playbooks for market entry, retrofit selling, and tender-to-contract acceleration, including pricing templates and contract clause libraries for uptime and contamination liabilities.
- CapEx/Opex models and scenario-based ROI calculators for decision-makers sizing investments in new installations or system upgrades.
- M&A and partnership targets: shortlist and rationale, integration risk checklists, and post-close 100/180/365-day value-capture plans.
- Implementation checklists and project timelines for 90-, 180-, and 360-day horizons to convert strategy into measurable milestones.
Competitive landscape — actionable insights on leading suppliers
The market’s competitive texture combines established international suppliers, specialised regional manufacturers, and a cohort of engineered-system providers that bundle manifolds into full-source-to-patient solutions. Key players profiled in depth include:
- BeaconMedaes (Atlas Copco): a systems player with a global channel and integrated pipeline solutions — strengths lie in turnkey hospital projects and deep engineering resources.
- Amico Corporation: cost-competitive, reliability-focused offerings suited to a broad hospital portfolio; strong in North American procurement environments.
- Silbermann Technologies: innovation-led automatic manifolds with options for high-availability configurations — attractive to health systems seeking compact, automated changeover solutions.
- Tri-Tech Medical: US-made, standards-compliant manifolds with credentials on NFPA and ISO quality frameworks — a preferred vendor for compliance-conscious institutional buyers.
- GCE Group (ESAB): recent product showcases emphasize high-flow automated changeover units tailored to demanding throughput scenarios.
- Regional specialists (Medicop, Pattons Medical, Precise Equipment, NOVAIR Medical, AMCAREMED): these firms maintain tight customer relationships, regional certification footprints and service density that matters for retrofits and emergency response.
Our supplier scorecards identify which vendors are best positioned for new-build hospital projects, which excel at retrofit and lifecycle services, and which have the engineering depth to meet evolving cGMP and ISO expectations.
Regulatory & product-readiness implications
The recently published regulatory guidance (including the FDA’s draft and final rules on medical gases) and the continuing primacy of ISO 7396-1 and NFPA 99 mean manufacturers must demonstrate process controls, contamination prevention and robust qualification protocols for manifolds and filling systems. For product teams, this translates into a short list of mandatory actions for 2026:
- Embed cGMP-relevant controls into manufacturing and cleaning SOPs, with traceability built into digital records.
- Prioritise third-party certifications and pre-audit remediation to shorten acceptance timelines in regulated markets.
- Design for maintainability and remote diagnostics to reduce on-site service visits and improve uptime guarantees.
Strategic plays by player type
- Incumbent manufacturers: defend through certification leadership, expand service contracts, and offer retrofit conversion kits for legacy manifolds.
- New entrants and challengers: target underserved retrofit segments, develop partnerships with EPCs on hospital builds, and focus on software-enabled value propositions.
- Private equity and investors: prioritise assets with service annuity potential and clear upgrade paths to automation; use bolt-on acquisitions to increase geographic coverage and standards credentials.
- Hospital procurement teams: centralise technical evaluation criteria around contamination risk, lifecycle cost, and interoperability with clinical gas management systems.
Risks, opportunities and concentration dynamics
With the market exhibiting moderate concentration — where the top three and top five suppliers account for a substantive portion of revenues — entrants face both barriers and opportunities. Barriers include certification lead times, established service networks, and bundled procurement practices. Opportunities reside in automation, predictive maintenance, retrofit conversions of legacy systems, and aftermarket service contracts that extend lifetime value.
Our scenario analysis stresses that while the headline forecast shows a steady multi-year expansion, short-term volatility can arise from large hospital project timing, regulatory enforcement waves, and supply-chain shocks. Sensitivity modelling in the report quantifies those effects, helping commercial leaders prepare flexible go-to-market plans.
Immediate actions for 2026 — a 90- to 180-day checklist
- Conduct a compliance gap assessment against 21 CFR part 213 and ISO 7396-1; prioritise certification workstreams that unblock key tenders.
- Review product roadmaps to accelerate digital monitoring and remote diagnostics deployments that generate service annuities.
- Identify retrofit wins in geographically concentrated markets and prepare a targeted sales & installation package with standardized pricing.
- For investors: request supplier scorecards and CapEx/Opex models to validate revenue visibility and integration synergies before committing capital.
Next steps — where to get the full intelligence
This briefing is intended as a strategic preview. PW Consulting’s full report contains the detailed segment economics, downloadable financial models, supplier scorecards, tender evaluation templates and transaction-ready M&A shortlists that underpin the insights summarised here. To access the granular segmentation tables, region-by-region demand drivers, and individual vendor scorecards that are withheld from this public summary, please consult the full report on our website or contact your PW Consulting account representative.
In an environment where standards and regulation are reshaping supplier economics, the managers who integrate compliance, product strategy and service design will win the most durable positions. This report equips you with the scenario-tested frameworks and executable playbooks to make those 2026 decisions with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Medical Gas Manifold Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com