

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Spray Scrubbers Market Set to Reach USD 1,725.4 Million in 2025 — Asia Pacific Leads with USD 729.02 Million as 4.12% CAGR Forecasted (2026–2032)

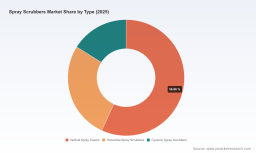
Worldwide Spray Scrubbers Market 2026: Strategic Imperatives from PW Consulting’s New Market Report
PW Consulting’s latest Worldwide Spray Scrubbers Market report (base year 2025) translates industry complexity into a clear set of strategic options for equipment manufacturers, EPC contractors, utilities, and industrial end-users preparing for 2026 and beyond. The market reached approximately USD 1,725.4 Million in 2025 and, under PW Consulting’s baseline scenario, is projected to grow to roughly USD 2,288.9 Million by 2032 — a compound annual growth rate (CAGR) of 4.12% across the 2026–2032 forecast horizon. These macro trajectories hide important variation at the segment, regional and application levels; our report exposes those variations for subscribers while preserving the big-picture guidance executives need to act now.
Worldwide Digital Governance Software Market
Why this report matters for 2026 decision-makers
-
Timely market sizing and forward-looking scenarios: With a thoroughly validated 2020–2025 historical base and multiple 2026–2032 forecast scenarios, the analysis lets leaders stress-test investment cases for greenfield supply, retrofit programs, and aftermarket services against regulatory and commodity shocks.
Extracorporeal Circulation Blood Circuit Market -
Regulation-driven upside: Recent regulatory actions — notably proposed tightening of MATS in December 2023 and EU waste-incineration BAT updates requiring >95% HCl removal — create a retrofit bias toward wet scrubber technologies. Our quantified scenarios show how compliance waves can materially accelerate demand in discrete windows, creating project pipelines that materially alter capacity planning.
Packed GC Columns Market -
Fragmented supply structure: The market exhibits moderate concentration (CR3 ≈ 28.5%; CR5 ≈ 39.2%), meaning incumbents hold meaningful footprints but national and specialist players remain influential. That structure favors differentiated technology offerings, local partnerships, and service-led monetization strategies.
-
Margin sensitivity to inputs and trade policy: Material cost dynamics and trade measures—such as elevated scrubber-grade stainless prices and Section 232 steel duties—can reshape landed cost equations and influence sourcing, localization, and vertical-integration decisions.
What PW Consulting’s report contains (practical, executable content)
-
Demand and revenue model: Full, auditable market model spanning 2020–2032 that produces addressable-market maps by region, product family, and application. (Detailed splits and proprietary figures are retained for subscribers to preserve competitive value.)
-
Technology and product evaluation: Comparative technical assessment of vertical towers, horizontal spray chambers, cyclonic spray systems and hybrid designs, including typical removal efficiencies, footprint trade-offs, CAPEX and OPEX drivers, and retrofit suitability by plant profile.
-
Unit-level cost and pricing models: Build-up sheets reflecting material inputs, fabrication labor, coatings/linings, and transport, with scenario toggles for tariffs and commodity swings (e.g., stainless steel and FRP resin). These allow rapid recalibration of tender economics for different geographies.
-
Supplier scorecards and procurement playbook: Objective benchmarking of vendors across performance, lead times, after-sales, local presence and compliance track record — designed to support RFP design, supplier rationalization, and negotiation levers.
-
Service and aftermarket strategies: Playbooks to convert project revenue into annuity income via maintenance contracts, spare parts, digital-monitoring upgrades and lifecycle-chemistry management.
-
Regulatory scenario planning: Mapped compliance triggers and probable retrofit timing under alternative policy scenarios — crucial for utilities and industrial operators managing compliance budgets over five- to seven-year cycles.
Key market dynamics shaping 2026 strategy
-
Regulatory accelerants: The December 2023 EPA MATS revisions and the EU’s updated BAT conclusions impose stricter emission thresholds. For many operators, wet spray scrubbers become the most technically and economically viable pathway to compliance — especially where >95% removal of acid gases is mandated. Companies that align sales, warranty and lifecycle support around these compliance windows will capture disproportionate share of retrofit budgets.
-
Raw material and fabrication risk: Stainless-steel prices for scrubber-grade 316L averaged about USD 2,450/ton in Q3 2023, up roughly 8% year-on-year due to energy costs; meanwhile, FRP resin costs rose into the USD 1,800–2,100/ton range in 2023. These input-cost swings, compounded by the 25% Section 232 duties on imported steel current as of 2024, mean suppliers that cannot localize fabrication or hedge commodity exposure will face margin compression.
-
Non-linear project pacing: The overall market trajectory shows periods of accelerated demand where regulatory-driven retrofits and clustered industrial megaprojects converge. Executives should not assume steady-state growth; instead, position to scale up or down quickly via modular manufacturing, partner networks, and flexible supplier contracts.
-
Customer economics: Total cost of ownership (TCO) increasingly dominates procurement decisions. Buyers weigh capital expenditure against OPEX drivers — water/chemical consumption, maintenance downtime and disposal — and are open to alternative contracting models, including performance guarantees and O&M outsourcing.
Competitive landscape — actionable takeaways
The market is populated by global engineering firms, specialist fabricators and regional champions. Understanding the comparative strengths of these players is essential when deciding to compete, partner, or acquire:
-
CECO Environmental Corp. — Positioning: Broad portfolio across Venturi wet scrubbers and spray solutions, with strength in power, cement and metal industries. Strategic implication: CECO’s scale and cross-industry experience make it an attractive partner for EPC houses seeking turnkey emission-control packages; it also sets a benchmark for integrated service offers.
-
Dürr AG — Positioning: Technology-led OEM with a proven Ecopure wet-scrubber product set for VOC and acid-gas control in automotive and chemical sectors. Strategic implication: Dürr’s engineering pedigree and system-integration capabilities place it well for contracts demanding tight performance envelopes and automated control systems.
-
Beltran Technologies — Positioning: Specialist in high-temperature, rotary-atomizer systems for submicron particulate capture. Strategic implication: Niche suppliers like Beltran are acquisition targets for larger incumbents seeking to expand into high-temperature or hazardous-ash applications that require premium designs.
-
Tri-Mer Corporation — Positioning: Trusted supplier of horizontal and vertical spray chambers for corrosive gases in semiconductor and pharma niches. Strategic implication: High-spec industries with stringent purification demands reward suppliers with proven corrosion-resistance and materials know-how.
-
Verantis Environmental & ERG (Air Pollution Control) Ltd. — Positioning: Mid-market engineers with strong FRP and venturi capabilities for HCl, SO3 and odor control across waste-to-energy, fiberglass and wastewater sectors. Strategic implication: Their regional market access and specialization in corrosion-resistant linings make them natural partners for international firms needing local manufacturing footprints.
-
Macrotek Inc. & KCH Engineered Systems — Positioning: Modular and custom FRP fabricators serving mining, steel, pulp/paper and petrochemical segments. Strategic implication: The rise of modularization and site-convenient quenchers aligns with these players’ strengths; OEMs should evaluate JV or licensing models to accelerate modular capacity.
Playbook for 2026 — recommended strategic moves
-
Hedge and localize critical supply chains: Lock in steel and FRP resin supply through multi-year contracts, strategic stockpiles, and nearshore fabrication. Where tariffs materially change landed costs, consider contract manufacturing or licensing to local fabricators to preserve margin.
-
Design for modularity and rapid deployment: Develop standardized module families for common retrofit classes to reduce lead times and field labor. Modular offerings enable price certainty and faster time-to-revenue when compliance windows open.
-
Shift from transactional sales to service contracts: Bundle aftermarket maintenance, spare parts, and consumables into multi-year contracts. Digital monitoring for early corrosion or performance drift can be monetized and reduces customer total cost of ownership.
-
Pursue focused M&A and tech investments: For mid-sized players, acquiring niche technology providers (e.g., high-temperature or submicron spray systems) can be a faster route to differentiation than organic R&D. For incumbents, consider minority investments in modular-fabrication specialists to expand regional market access.
-
Embed compliance advisory in sales: Sales teams should be equipped with regulatory impact tools that map specific plant profiles to compliant equipment and O&M scenarios. This moves conversations from product-specs to compliance economics — where larger wallet-share decisions are made.
How PW Consulting’s report supports execution
The report is expressly practical. For commercial teams it supplies supplier-sourcing templates and tender language that incorporate input-cost clauses and performance guarantees. For engineering and operations functions it offers technology selection matrices, CAPEX/OPEX trade-off dashboards and lifecycle-chemistry management guidelines. For corporate strategists it includes M&A screens, partner-compatibility checklists, and regulatory scenario maps that quantify project timing and scale. Detailed regional and application-level data, vendor scorecards and downloadable financial models are available to subscribers to the full report.
Conclusion — what to do now
Executives preparing budgets and investment plans for 2026 should act on three near-term imperatives: secure raw-material exposure and fabrication flexibility, roll out modular product platforms and service packages, and align go-to-market strategies with imminent regulatory compliance cycles. The overall market momentum — from approximately USD 1,725.4 Million in 2025 to an estimated USD 2,288.9 Million by 2032 at a 4.12% CAGR — creates a window of opportunity for firms that combine technology differentiation with supply-chain resilience and service-led commercial models.
For organizations seeking the granular analysis and executable templates that will determine winners in 2026, PW Consulting’s full Worldwide Spray Scrubbers Market report provides the audited models, supplier evaluations and scenario tools required to convert insight into competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Spray Scrubbers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com