

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Medical Facility Lighting Systems Market Poised for 5.82% CAGR, New Report Reveals

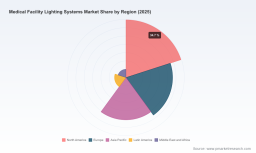
Worldwide Medical Facility Lighting Systems Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
As hospitals and outpatient surgical providers reset capital priorities for 2026, lighting systems for medical facilities have moved from an operational afterthought to a strategic investment that touches clinical outcomes, building sustainability goals, and total cost of ownership. PW Consulting’s new market study positions the Worldwide Medical Facility Lighting Systems Market as a steady-growth sector: the market reached approximately USD 5.28 billion (USD Million) in our base year (2025) and is projected to expand at a compound annual growth rate (CAGR) of 5.82% through our forecast window (2026–2032), reaching an upper-market near-term forecast in the high single-digit billions by 2032.
Orthopedic External Fixation Brace Market
Why lighting matters to 2026 strategy
-
Clinical performance: Modern surgical and diagnostic luminaires directly influence visualization, clinician ergonomics, and procedural precision. Compliance with IEC standards for surgical luminaires and the IES recommended practices is increasingly enforced by health systems and accrediting bodies.
Worldwide Operation and Maintenance Training Market -
Capital intensity and replacement cycles: With hospital capital spending climbing to address aging facilities and ambulatory expansion, lighting is part of a broader facilities modernization wave. Health systems looking to optimize CapEx are evaluating lighting not only for upfront cost but for lifecycle savings, energy performance, and maintenance burdens.
LV Breaker Panels Market -
Regulatory and payment environment: Changes in facility reimbursement and outpatient payment policy influence procurement cadence for procedure rooms and imaging centers. Buyers are balancing compliance-driven upgrades with reimbursement headwinds and revenue cycle pressures.
-
Sustainability and energy costs: LED technology and integrated lighting controls are core contributors to facility decarbonization pathways and operating expense reduction—an increasingly measurable KPI in health system boardrooms.
Market dynamics shaping vendor and buyer behavior
Our analysis synthesizes macroeconomic and sector-specific signals that will determine winners and losers in 2026. Key dynamics include: persistent LED migration across clinical settings; tightening technical standards (e.g., IEC 60601-2-41 and ANSI/IES RP-29-22) that raise the bar for color rendering, temperature control and clinical suitability; and capital-strained buyers who demand financing, performance guarantees, and integrated service models.
Notably, industry-level CapEx indicators show health systems increasing investment intensity to address deferred facility maintenance and new ambulatory capacity—creating opportunities for suppliers who can align financing and retrofit programs with hospital planning cycles. Meanwhile, procurement is being influenced by tenders and public-sector solicitations in 2026 that favor demonstrable lifecycle savings and interoperability with clinical workflows.
What PW Consulting’s report delivers (practical, decision-ready tools)
This market brief is a preview of a comprehensive toolkit designed for C-suite, procurement leaders, product strategy teams, and private investors. The full report includes:
-
A financial model calibrated to 2020–2025 history and extended through 2032, with market sizing in USD Million and scenario toggles for demand, price, and replacement rates.
-
Segment playbooks that translate technical standards and clinical requirements into procurement specifications and vendor scorecards.
-
Total cost of ownership (TCO) calculators that factor in energy, maintenance, spare-part logistics, and clinical downtime for retrofit versus new-build decisions.
-
A regulatory and standards compliance matrix mapping IEC and IES guidance to product development and procurement checklists.
-
Vendor benchmarking tools and an interactive competitive landscape dashboard that supports supplier selection and M&A screening.
-
Practical recommendations for structuring RFx language, service-level agreements (SLAs), and pilot program KPIs to de-risk large-scale rollouts.
Competitive landscape — what incumbents and challengers are doing
The supplier landscape blends large global lighting and medical equipment OEMs with specialized medical lighting manufacturers and regional firms. Market concentration is moderate: our firm-level concentration metrics indicate that the top three players account for roughly two-fifths of the market while the top five capture just over half, signaling room for differentiation and consolidation.
Leading multi-national players are pursuing platform strategies that bundle luminaires with controls, analytics, and field services. Examples of strategic moves observed in the market include:
-
Product platform refreshes to capture OR and critical-care upgrade cycles, illustrated by recent next-generation surgical light launches aimed at improving color consistency and ergonomics.
-
Partnerships to access advanced materials and manufacturing techniques that improve durability and allow for lighter, more modular luminaires.
-
Emphasis on aftermarket services—warranty extensions, preventative maintenance programs, and spare-parts logistics—that convert equipment sales into stable annuity streams.
Key names we assessed include global lighting majors and medical-device incumbents with complementary portfolios: multinational lighting and healthcare brands, leading surgical-system manufacturers, specialist LED medical-light producers, and diversified electrical groups with healthcare segments. Across this mix, competitive differentiation is being driven by: clinical performance validation, integration with operating-room architectures, energy and sustainability credentials, and the quality of service delivery.
Recent market signals to watch in 2026
-
Product refreshes from major surgical-light manufacturers, illustrating accelerated product development cycles and renewed emphasis on clinician-centric features.
-
Strategic partnerships focused on materials and manufacturing innovations for primary components—an indicator of margin and manufacturing resilience strategy among more nimble suppliers.
-
Public tender and contract notices for LED retrofits in public health facilities—early indicators of procurement programs that can scale.
-
Updates to hospital outpatient payment policy and continued focus on capital planning metrics that will influence the timing and scale of lighting investments.
Strategic playbook for 2026 — recommended actions
For executive teams at suppliers, health system procurement leads, and financial sponsors, our primary recommendations are tactical and immediately actionable:
-
Reposition offerings around outcome-based value: Move beyond lumen-per-watt selling points to demonstrable outcomes—reduced procedure times, improved clinician satisfaction, lower energy spend, and reduced downtime during maintenance.
-
Modularize product and service bundles: Offer scalable upgrade paths (retrofit kits, modular head units, control add-ons) and financing models that align with hospitals’ CapEx cycles.
-
Embed compliance and documentation into sales cycles: Pre-built compliance packages that reference IEC and IES guidance accelerate procurement approvals and reduce tender friction.
-
Invest in after-sales infrastructure: Rapid response service networks and predictable spare-parts availability are decisive factors for health systems concerned about OR throughput and patient safety.
-
Design pilots for measurable adoption: Structure 6–12 month pilots with clear KPIs (energy, uptime, clinician feedback) to build evidence for system-wide rollouts.
-
Monitor tender pipelines and public-sector solicitations: Early engagement with health authorities and system integrators positions suppliers to participate in multi-hospital retrofit waves.
-
Prepare for consolidation and partnerships: Expect M&A activity among mid-market participants and consider strategic alliances to fill capability gaps in services, controls, or global distribution.
What’s intentionally withheld — why you need the full report
Consistent with the “trailer” approach, this release provides a high-resolution view of market dynamics, competitive positioning, and the strategic implications for 2026. To preserve the commercial value of our primary research, detailed segment-level tables, unit price curves, regional revenue splits, and proprietary company scorecards are not reproduced here. Those datasets—built from primary interviews, contract databases, and vendor financials—are included in the full PW Consulting report and the interactive spreadsheet models referenced above.
Next steps for decision-makers
Organizations that treat lighting as a strategic lever will capture operational, clinical, and financial upside throughout 2026. PW Consulting’s full market study arms you with the granular data, models, and procurement templates necessary to convert opportunity into measurable outcomes. Contact our analyst team to access the complete dataset, run a tailored scenario for your portfolio, or schedule a briefing on supplier strategy and RFP design.
For detailed analysis of this topic, please visit the official page: Worldwide Medical Facility Lighting Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com