

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide KVM Devices Market Poised to Grow at 4.8% CAGR and Reach USD 4,554.8 Million by 2032

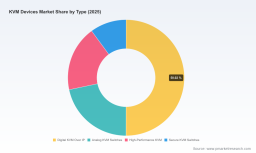
Worldwide KVM Devices Market: Strategic Imperatives for 2026 — PW Consulting Industry Brief
PW Consulting’s latest Worldwide KVM Devices Market report (base year 2025; historical 2020–2025; forecast 2026–2032) is issued at a decisive moment for infrastructure buyers, security teams, and systems integrators. The global KVM devices market is entering a phase of steady expansion—supported by digitalization of console access, stricter security regimes, and the continuing modernization of data centers and control-room environments. Our analysis shows the market at approximately USD 3.28 billion in 2025, advancing at a compound annual growth rate (CAGR) of 4.8% through the 2026–2032 forecast window and approaching just over USD 4.5 billion by 2032. This brief highlights how the report turns those headline numbers into practical guidance that should shape vendor strategy, procurement schedules, and secure operations planning in 2026.
Worldwide Virtual Machine and Hardware Virtualization Service Market
Why this report matters for 2026 decision-making
Several converging forces are re-shaping demand and risk profiles for KVM solutions. First, regulation and energy policy are influencing data center siting, load planning, and cost allocations—factors that ripple into how enterprises and hyperscalers think about remote management, console consolidation, and edge deployments. In 2026 alone, U.S. states accelerated legislative activity affecting large-load customers and interconnection costs, while the EU tightened operational reporting requirements for data centers under energy-efficiency directives. Second, cybersecurity frameworks and procurement standards—illustrated by recent NIAP-compliant product rollouts—are creating a bifurcated market where secure KVM offerings command strategic premium and compliance-driven selection. Third, video and latency expectations (4K/8K, low-latency IP transport) are driving technical differentiation between commodity desktop switches and high-performance matrix/over-IP architectures.
Surgical Microscope Protective Cover Market
For buyers and CTOs, the combination of an expanding but moderately concentrated market (top-three firms representing a material share of capacity, and the top-five approaching a clear majority) means competitive dynamics will favor vendors that combine product breadth with regulatory and integration expertise. Our report converts these macro signals into procurement roadmaps and vendor scorecards that reflect both risk and opportunity.
Top Collection Jewelry Insurance Market
What the report contains — practical, transaction-ready deliverables
- Executive synthesis with scenario-driven market sizing — base case, energy-constrained, and accelerated-AI adoption paths.
- Proprietary market model (xls) with modular inputs so clients can stress-test price, adoption rate, and replacement cycles against their own fleet profiles.
- Vendor capability maps and a modular RFP template tuned for security certification, latency, and scalability requirements.
- Five procurement playbooks — for hyperscalers, colocation operators, government/defense, broadcast/control-rooms, and SMB/office deployments — each with negotiation play points and SLA checklists.
- TCO and lifecycle calculators that quantify CAPEX/OPEX tradeoffs for copper vs fiber, analog vs IP, and console consolidation strategies.
- Integration checklists, common failure-mode mitigation measures, and an implementation timeline matrix for phased rollouts.
We deliberately present deep operational content: sample RFP clauses for NIAP and TAA contexts, a matrix of technical acceptance tests (4K/8K throughput, packet jitter tolerance, failover procedures), and service-level templates for hybrid on-prem/remote access deployments. At the same time, consistent with our “trailer” principle, the report reserves full sub-segment numbers, regional splits and vendor revenue shares for the downloadable study—ensuring buyers consult the full dataset to align procurement with precise market benchmarks.
Data-driven strategic insights you can act on in 2026
- Macro trajectory and investment timing: With the market growing at a mid-single-digit CAGR, replacement cycles and integration projects should be staggered to avoid vendor bottlenecking in the mid-2026 to 2028 window. Capital plans for 2026 must include marginal allocations for high-performance IP upgrades where low-latency remote console access is critical.
- Security is a procurement differentiator: NIAP PP 4.0 and related certification trends are no longer niche. Recent vendor certifications and compliant product launches indicate that security compliance will become a gating item in public and regulated procurements; your procurement templates must include compliance verification steps and acceptance tests.
- Fiber vs copper tradeoffs: Technical-grade fiber KVM matrix approaches often deliver superior reach and signal integrity, but they can carry a 30–50% higher upfront cost than copper-based alternatives. Our TCO models show that for long-haul or mission-critical installations the total-cost-of-ownership can favor fiber within a five- to seven-year horizon when availability and performance risk are material.
- Latency and video fidelity as service-level metrics: Demand for 4K/8K console support and near-zero frame loss in broadcast and control-room applications is pushing buyers to treat video fidelity and jitter as contractual KPIs, not just product specs.
- Concentration and partner selection: With the market exhibiting meaningful concentration at the top, strategic sourcing should blend marquee vendors (for scale and integration) with niche specialists (for mission-specific requirements such as NIAP-cert secure KVMs or fiber matrix expertise).
Competitive landscape — how vendors are positioning for 2026
The report’s vendor analysis goes beyond logos and product catalogues to assess go-to-market approaches, channel coverage, certification posture, and integration capabilities. Key vendor archetypes and illustrative strengths include:
- Data-center and enterprise systems integrators: Companies with integrated power and server-management portfolios bring compelling bundled value for large deployments and can accelerate procurement cycles through existing relationships.
- High-performance matrix specialists: Vendors focused on broadcast, control-room and mission-critical deployments emphasize low-latency, fiber-based matrix solutions and multi-site synchronous management.
- Secure KVM and certified vendors: A cluster of firms is prioritizing NIAP compliance, CAC/TAA support, and other national security-oriented certifications—important for government, defense, finance, and healthcare customers.
- SMB and desktop-focused suppliers: Broader IT peripherals firms are competing on price, ease-of-use, and distribution footprint; they are winning deals where security and extreme latency performance are not primary constraints.
Recent market moves further crystallize positioning: a number of established vendors announced NIAP-compliant secure KVM product lines in late 2025 and early 2026, and strategic partnerships have been launched to address the growing IP-based KVM opportunity for modern AV and control-room ecosystems. For buyers, these developments mean that certification and ecosystem compatibility should carry weight commensurate with price during vendor evaluations.
Priority recommendations for 2026 procurement and architecture teams
- Embed certification gates into procurement: Require evidence of NIAP or equivalent compliance where regulatory risk exists, and include independent verification clauses in purchase agreements.
- Run hybrid pilots before widescale migration: For IP-over-KVM or fiber-matrix transitions, execute a two-phase pilot—functional acceptance plus scaled stress tests—before full rollout to protect operations during cutover.
- Use our dynamic TCO model to compare options: Don’t make decisions on sticker price alone. Our model quantifies replacement cadence, service costs, and failure risk premiums for fiber vs copper and analog vs digital architectures.
- Structure RFPs around operational KPIs: Specify jitter tolerance, frame-loss ceilings, failover recovery windows, and remote management API compatibility rather than only video-resolution specs.
- Plan for regulatory escalation: Align procurement windows with anticipated policy shifts (state-level interconnection bills, EU efficiency reporting) to avoid cost surprises tied to data-center energy or siting mandates.
How organizations will use the full report
Clients who download the full PW Consulting report receive: the master dataset (editable), vendor scorecards with a supplier short-list calibrated to user requirements, contract-language templates for security and performance, and a quadrant-style competitive map that contextualizes vendor capability against the market’s concentration metrics. For boards and procurement committees, we also include a two-page strategic brief that translates the market forecast into budgetary impacts and a recommended procurement cadence for 2026.
We designed the publication to be both an intelligence product and a working toolkit: it is intended to be opened, edited, and inserted into vendor evaluation workflows. We intentionally keep some subsegment-level tables and vendor revenue splits gated behind the full report to preserve the value of the proprietary dataset—clients who require segment-level benchmarks and granular regional forecasts will find those in the downloadable study.
Concluding guidance
Heading into 2026, KVM decision-making is as much about regulatory compliance, lifecycle economics, and integration discipline as it is about raw product features. The market is maturing—projected to grow from roughly USD 3.28 billion in 2025 at a 4.8% CAGR through 2032—while vendor positioning is sharpening around security, fiber-based high-performance matrices, and IP-first architectures. PW Consulting’s Worldwide KVM Devices Market report translates these macro dynamics into executable procurement playbooks, measurable TCO models, and vendor scorecards so that teams can convert market intelligence into defensible, low-risk decisions.
Access the full report to obtain the granular segmentation tables, region- and application-level forecasts, and the complete vendor short-lists required to finalize 2026 sourcing and integration plans.
For detailed analysis of this topic, please visit the official page: Worldwide KVM Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com