

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide NF3 and F2 Market Poised to Reach USD 2,464.84 Million by 2032, Growing at a 7.15% CAGR

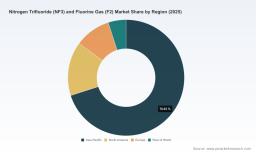
Worldwide Nitrogen Trifluoride (NF3) and Fluorine Gas (F2) Market — Strategic Preview for 2026 Decision-Makers
Executive summary
PW Consulting’s latest market study—covering historical performance (2020–2025, base year 2025) and forward-looking forecasts to 2032—provides a pragmatic roadmap for executives making capital, sourcing, and regulatory-compliance choices in 2026. The combined NF3 and F2 market is entering a phase of measured expansion: our base-year estimate places 2025 global revenue at approximately USD 1,520 million, with the market projected to grow at a compound annual growth rate (CAGR) of 7.15% through the 2026–2032 forecast period. By 2032, the market is expected to approach the mid‑two‑billion USD range, underscoring substantial upside for well-positioned participants while amplifying strategic risks for those reliant on narrow supply chains or single-region demand.
Worldwide Cell Culture Sampling Device Market
Why this matters for 2026 strategy
- Capital planning: The reported growth trajectory supports selective capacity investment in high-purity NF3 and specialized F2 handling capabilities, but the timing and location of that investment must account for regulatory and logistics headwinds.
- Sourcing and procurement: Volatility in upstream inputs and transport complexity will force procurement teams to shift from lowest-cost sourcing to resilience-driven portfolios.
- M&A and partnerships: A market with high top-tier concentration and predictable growth incentivizes bolt-on acquisitions, alliance formation with regional producers, and long-term offtake agreements.
Market structure and concentration — what it implies
Our analysis shows that the NF3/F2 market is numerically concentrated: the top three players account for roughly 68% of market share, while the top five approach 82%. This concentration produces three strategic realities for executives:
Worldwide BOPP Touch Film Market
- Pricing and specification leadership are held by established industrial gas firms and specialty chemical producers; entrants must either innovate on purity, delivery model, or cost-to-serve to create space.
- Regulatory and compliance investments are a barrier to scale. Scale players can amortize the fixed costs of high-integrity handling, certification, and safety systems more readily than smaller competitors.
- Commercial negotiation dynamics favor integrated buyers willing to commit to multi-year contracts, but those contracts will increasingly carry clauses tied to regulatory compliance, force majeure, and export-control contingencies.
Key demand drivers and downside risks
Demand continues to be anchored in electronics manufacturing — semiconductor fabrication and advanced display production — with secondary uptake in specialty fluorination for pharmaceuticals and solar. Three strategic drivers will define winners in 2026:
Worldwide Channel Marketing Management Software Market
- Technology migration in semiconductors and flat-panel displays that increases the requirement for ultra-high-purity NF3 and tailored F2 grades.
- Regulatory tightening around emissions and chemical stewardship, creating a premium for certified low-emission supply chains.
- Geopolitical supply-chain fragmentation and export-control regimes that fragment markets and raise the cost of cross-border flows.
Countervailing risks include cyclical softness in capex-intensive end-markets and episodic upstream raw-material shocks that can compress margins unpredictably.
Cost and supply-side dynamics executives must model now
Two supply-side notes require immediate attention in 2026 planning cycles:
- Raw-material inflation: Anhydrous hydrogen fluoride (AHF), a core feedstock, experienced notable price pressure in late 2024 driven by regional supply disruptions. Buyers should model scenarios that incorporate sustained higher feedstock costs and evaluate index-linked offtake contracts or hedging strategies where available.
- Transport and handling complexity: Fluorine (UN 1045) classification necessitates specialized cryogenic transport and handling infrastructure, which materially increases logistics cost and delivery lead time. Buyers and suppliers must factor an effective logistics premium into landed-cost calculations and contingency planning.
Regulatory and trade dynamics — a new operating environment
Regulation and trade policy are active drivers for 2026 strategy:
- Regulatory tightening: Authorities in major markets have increased reporting requirements for NF3 emissions and tightened environmental oversight. Companies should prioritize investment in emissions monitoring, transparent reporting systems, and third-party verification to preserve market access and corporate reputation.
- Export controls: Expanded controls on F2 exports to certain markets are already disrupting traditional trade flows. Commercial teams need to refresh compliance playbooks, re-evaluate sourcing geographies, and build alternative pathways for constrained markets.
Competitive landscape — what the majors signal
Our report profiles the leading global producers, with operative insights into manufacturing footprints, product-grade segmentation, and strategic moves that matter for 2026:
- Solvay (Belgium) — continues to leverage a broad product portfolio across NF3 and F2, supplementing production in Europe and Asia with product-grade innovation aimed at pharmaceutical fluorination and specialty synthesis.
- Air Products (USA) — has targeted capacity to meet regional semiconductor demand and remains a strategic supplier for high-purity NF3. Recent capacity expansions underscore the company’s play for long-term supply agreements with foundries and OEMs.
- Linde (Germany) — combines NF3 and F2 offerings with a global logistics and safety infrastructure; recent certification upgrades signal a focus on compliance-led differentiation.
- Kanto Denka Kogyo and Morita Chemical Industries (Japan) — focused on ultra-high-purity grades for Asian electronics clusters; their geographic proximity to end-users is a competitive advantage where on-time delivery and purity are decisive.
- Hyundai Steel (Green Gas) and Pelchem (Peltzer Group) — regional producers that fill important niche roles; their presence underscores the need for diversified supplier matrices, especially for regional OEMs.
Recent public actions by market leaders—capacity expansions, new product grades, and certification upgrades—spell two messages: incumbents are defending their technical edge, and the market will reward suppliers that can demonstrate traceable supply chains and certified handling regimes.
What PW Consulting’s report delivers — practical, decision-grade outputs
We designed the study as an operator’s toolkit for 2026. Highlights include:
- Demand-supply models calibrated to 2020–2025 historicals and stress-tested across multiple 2026–2032 scenarios; models are provided in editable formats to support client-specific assumptions.
- Risk-adjusted price and cost models that capture feedstock volatility, logistics premiums associated with specialized transport, and regulatory compliance cost trajectories.
- Commercial playbooks: procurement contracting templates, clauses for export-control and emissions contingencies, and negotiation benchmarks for long-term vs spot sourcing.
- M&A and JV target screen: a prioritized list of mid-sized regional producers and specialty suppliers whose integration case is supported by synergies in certification, distribution, or product-grade expansion (detailed valuations and integration checklists available in the full report).
- Regulatory roadmaps: jurisdiction-specific compliance actions through 2026 for major markets, plus a set of mitigation strategies to preserve cross-border trade in controlled chemistries.
- Supplier resilience diagnostics and a scorecard to qualify partner reliability on 12 operational dimensions including certification, inventory posture, and logistics capability.
How to use these insights in real decisions
For C-suite and commercial leaders, the most immediate uses of the PW Consulting study in 2026 are:
- Revising capital-allocation priorities: prioritize upgrades that reduce unit handling risk, improve grade differentiation, or shorten lead times to strategic customers.
- Reconfiguring supply portfolios: implement a two-tier sourcing strategy that balances cost-competitive bulk suppliers with regional, certified partners for critical high-purity flows.
- Embedding regulatory contingency into contracts: ensure that pricing and delivery frameworks account for unanticipated export-control actions or new emissions reporting requirements.
- Targeting M&A selectively: pursue assets that add certified capacity, local customer access, or proprietary purification technology rather than chasing volume alone.
Conclusion — the strategic opportunity for 2026
The NF3 and F2 market presents a classic industrial-growth opportunity: steady, technically complex demand combined with regulatory and logistical friction. Our forecast shows a clear expansion path from a 2025 base, and the concentration of supply means that well-capitalized, compliance-led players will capture outsized returns. For buyers and investors, the imperative for 2026 is to convert insight into resilience—invest in certified supply, lock in flexible offtake arrangements, and prioritize partners that demonstrate both technical grade control and geopolitical-savvy trade operations.
Learn more
PW Consulting’s full Worldwide Nitrogen Trifluoride (NF3) and Fluorine Gas (F2) Market report contains the granular data, country- and application-level scenarios, editable financial models, and actionable templates referenced above. For access to the complete intelligence package and bespoke briefings that apply these findings to your portfolio or operations in 2026, please visit our report page or contact your PW Consulting representative.
For detailed analysis of this topic, please visit the official page: Worldwide Nitrogen Trifluoride (NF3) and Fluorine Gas (F2) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com