

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Acetylated Starch Market Set to Expand at a 4.81% CAGR During 2026–2032

PW Consulting Releases Strategic Briefing: Worldwide Acetylated Starch Market — What Leaders Must Know Ahead of 2026
PW Consulting today publishes an executive-level briefing synthesizing the strategic implications of our full Worldwide Acetylated Starch Market report (base year: 2025; historical window: 2020–2025; forecast: 2026–2032). Built for C-suite decision-makers in food ingredients, specialty chemicals, pharmaceuticals and paper/textiles, this briefing highlights the macro trajectory, supply-chain stress points, competitive moves and the high-leverage choices firms should prioritize as they enter 2026 planning cycles.
Robotics for K-12 Education Market
Market trajectory: steady growth, rising strategic complexity
Acetylated starch is a mature specialty ingredient whose global revenue footprint expanded from roughly USD 508 million in 2020 to about USD 644 million in 2025. Looking forward, the market is projected to grow through the 2026–2032 forecast window at a compound annual growth rate (CAGR) of approximately 4.81%, reaching an estimated market size near USD 894 million by 2032. That growth profile signals continued, predictable demand driven by food texturizing, paper and industrial uses, while leaving room for disruptive entrants and product innovation to reshape share dynamics.
Worldwide Cloud Management Suite Market
Why 2026 is a pivotal year for strategic choices
- From cost management to capability bets: With steady top-line growth but persistent raw-material and regulatory volatility, 2026 will separate firms that optimize procurement and operational resiliency from those that pursue margin recovery through product- or market-led strategies.
- Portfolio clarity matters: The market’s moderate concentration (CR3 ~32.4%; CR5 ~46.8%) indicates leading incumbents hold substantial scale advantages, but meaningful share remains addressable for agile challengers. Investment allocation — whether R&D in clean-label systems, capacity expansions, or M&A — must be aligned to realistic share-opportunity maps.
- Regulatory and formulation windows: Evolving safety evaluations and clean-label trends create windows for differentiated, value-added acetylated starch grades. Companies that lock in development and regulatory approvals in 2026 will enter 2027 with a first-mover edge.
Supply-chain and input cost dynamics to watch
Input volatility is the proximate driver of margin swings. Several recent sector signals should shape purchasing and sourcing strategies for 2026:
Worldwide Gas Gravitometers Market
- Feedstock pricing remains a cross-border risk: For example, corn — a principal raw material in many acetylated starch processes — exhibited notable price volatility in recent marketing cycles. Procurement strategies that combine forward coverage with flexible supplier options will materially reduce P&L volatility.
- Regional feedstock tightness can create substitution pressure: Potato starch markets in Europe experienced supply-driven price upticks following acreage reductions, prompting formulators to reassess source mixes and to accelerate qualification of alternative starches for key applications.
- Catalyst and reagent pricing moves matter: Spot prices for acetic acid in major producing hubs have oscillated; oversupply in certain regions recently pushed prices down materially, which can compress downstream costs if logistics and inventory alignment are spot-on.
- Trade policy remains a non-trivial constraint: Tariff actions affecting starch flows between major producing and consuming geographies create both risk and opportunity for vertically integrated producers and traders.
Segmentation and end-market dynamics (what the full report contains)
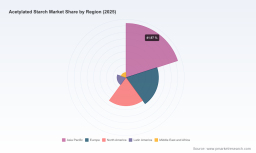
Our full report decomposes demand by region, source (corn, tapioca, potato, wheat and others) and application (food & beverages, paper & textiles, pharmaceuticals, and industrial uses). Rather than reproducing granular splits here, we surface three strategic takeaways:
- Source flexibility matters: End-users and ingredient makers benefit from capability to re-blend or reformulate across starch sources when regional feedstock tightness or regulatory changes occur.
- Application-driven premiumization: Specific applications (e.g., frozen bakery, dairy analogs, pharmaceutical excipients) reward tailored acetylation chemistries — investing in application-focused R&D can unlock premium pricing.
- Regional dynamics are operational levers: Market access, logistics costs, and local regulation affect where to place capacity and whom to partner with. The full report includes regional scenario models that quantify these trade-offs for candidate expansion plans.
Competitive landscape — profiles and strategic posture
The acetylated starch space blends global ingredient giants with specialized regional players. Our competitive analysis synthesizes public profiles, product focus and strategic posture for the most relevant players, including:
- Cargill Inc. (Minneapolis, MN, USA) — a global leader in modified starches, with a broad portfolio including acetylated grades designed for food stability and texture. Their scale and integrated raw-material positioning make them a natural consolidator and solutions partner.
- Ingredion Incorporated (Westchester, IL, USA) — offers targeted clean-label acetylated blends for sauces and bakery under well-known brands. Ingredion’s strength lies in customer co-development and application engineering.
- Tate & Lyle PLC (London, UK) — focuses on esterified and acetylated starches for performance in challenging processing conditions such as freeze-thaw cycles in frozen foods.
- Roquette Frères (Lestrem, France) — deep presence in pharmaceutical-grade acetylated starches and emulsification technologies tied to tablet and oral-formulation applications.
- Avebe U.A. (Veendam, Netherlands); Emsland Group (Emlichheim, Germany); AGRANA (Vienna, Austria); and KMC Kartoffelmelfabrik A/S (Hammel, Denmark) — each brings differentiated source expertise (notably potato and corn) and application-specific platforms across dairy analogs, adhesives, and pet food.
Across these firms, the most consequential strategic moves to monitor in 2026 will be bolt-on M&A to secure feedstock, investments in application labs and co-manufacturing tie-ups with CPG customers to lock-in specifications.
Operational and commercial playbook for 2026
Based on our scenario modeling and supplier interviews, PW Consulting recommends executives consider the following prioritized actions as part of 2026 planning:
- Hedge smartly, not blindly: Combine a rolling forward-buy program for high-risk feedstocks with options to convert between starch sources where possible. This reduces tail-risk from crop shocks while preserving upside if prices fall.
- Invest in application engineering: Allocate R&D capacity to the top two application clusters that align with your route-to-market; differentiated formulations command higher margins and customer stickiness.
- Lock capacity through partnerships: Where capex lead times are long, secure output via tolling agreements, JV minority stakes or long-term offtake contracts rather than sole reliance on brownfield expansion.
- Regulatory readiness: Prioritize resources to track regional safety re-evaluations and clean-label guidance; early dossier submissions and transparent data-sharing accelerate approvals and reduce time-to-market for new grades.
- Commercial sophistication: Shift commercial incentives to value-based pricing for functional benefits (freeze-thaw stability, binder strength, etc.) rather than competing solely on cost-per-kilogram.
What’s inside the full PW Consulting report (operationally actionable)
The complete Worldwide Acetylated Starch Market report is designed as an operational toolkit for 2026 decision cycles. Key deliverables include:
- Detailed historical demand and a 2026–2032 forecast model with scenario toggles for feedstock price shocks, regulatory restrictions and application penetration rates.
- Regional supply-demand balance sheets and logistics cost maps to guide capacity siting and inventory policy.
- Competitive capability matrix and 10+ company profiles with strategic posture and likely next moves.
- Supplier risk heatmap and procurement playbooks (contract structures, hedge approaches, alternative sourcing pathways).
- Commercial playbooks for marketers and sales teams, including value-based pricing calculators and customer segmentation frameworks.
- Regulatory tracker and dossier templates for formulations subject to food-safety re-evaluations.
How to use this intelligence in 2026 planning
Leaders should treat the report not as an academic exercise but as decision infrastructure. Use the forecast model to stress-test EBITDA under alternative feedstock and tariff scenarios. Use the supplier heatmap to prioritize which supplier relationships to deepen in H1 2026. And use the application roadmaps to determine where to place limited R&D dollars for the highest ROI over the next three years.
Closing: a selective intelligence approach
PW Consulting’s full report delivers the granular segmentation and proprietary models that underpin the strategic guidance summarized here. In keeping with our “trailer” approach, we have intentionally withheld the report’s detailed regional and application splits in this briefing to encourage practitioners to engage the underlying datasets and scenario tools directly. Firms that pair this macro view with the report’s micro-level models will be positioned to move first and with conviction as 2026 unfolds.
For access to the full Worldwide Acetylated Starch Market report, the forecast model and the procurement playbooks, please visit our report page or contact PW Consulting’s Industry Desk to schedule a briefing and model walkthrough.
For detailed analysis of this topic, please visit the official page: Worldwide Acetylated Starch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com