

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Agricultural Nanotechnology Market Set to Surge to USD 816.02 Million by 2032 on a 14.03% CAGR

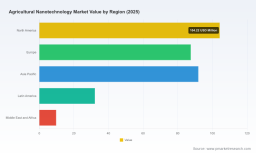
Worldwide Agricultural Nanotechnology Market 2026 Strategic Preview — Actionable Paths to Scale, Safety, and Commercial Success
PW Consulting’s new market study on Worldwide Agricultural Nanotechnology delivers a practical, decision-ready intelligence package tailored to senior executives, corporate strategy teams, and investors who must make consequential resource-allocation decisions in 2026. Using 2025 as the analytical base year and a detailed historical review covering 2020–2025, our forecast through 2026–2032 models sector trajectories under multiple adoption and regulatory scenarios. The picture is clear: the market has expanded rapidly in recent years and is projected to sustain a robust compound annual growth rate (CAGR) of 14.03% through 2032, crossing meaningful commercial scale during the forecast window. This briefing highlights the strategic value of the report while preserving the granular segment-level intelligence for readers who download the full study.
Worldwide Freight Audit and Payment Market
Why this report matters for 2026 decisions
-
Accelerated commercialization window: Technology maturation and early field wins are converting laboratory promise into farm-level commercial opportunities. Our model shows a clear inflection in market size beginning in the mid-2020s, creating a narrow window for first-mover advantage in target geographies and use-cases.
Worldwide Mobile Identity Software Market -
Capital-allocation clarity: With an aggregated, data-driven market size baseline and scenario modeling, the report helps CFOs and corporate strategy teams prioritize R&D and capital investments across product pipelines, manufacturing, and go-to-market activities.
Point Source Carbon Capture Device (PSCD) Market -
Regulatory and reputational risk framing: We translate nascent regulatory signals and ecotoxicology concerns into pragmatic action steps corporate legal and regulatory teams can use to structure trials, regulatory submissions, and public communications.
-
M&A and partnership timing: Market concentration metrics indicate a competitive landscape that is neither fully consolidated nor atomized—creating openings for targeted acquisitions, joint ventures, and licensing strategies to buy scale or capability.
What’s inside the report — practical, operational deliverables
-
Executive dashboards with base-year calibration (2025) and transparent scenario assumptions for 2026–2032, enabling stress-testing of investment cases under alternative adoption and regulatory outcomes.
-
Technology readiness and commercialization matrices that map materials, formulation approaches, and sensor integrations to pilot-to-scale pathways and expected time-to-revenue.
-
Unit-economics and ROI playbooks at farm and distributor levels, including sensitivity analyses on price premia, application frequency, and yield uplift—designed for rapid use in board-level investment debates.
-
Regulatory pathway maps and recommended dossier contents for major jurisdictions, with tactical checklists for ecotoxicology, environmental monitoring, and traceability requirements.
-
Supply-chain and raw-material sourcing blueprints, including low-cost pathways using agricultural waste biomass for nanomaterial production and contingency plans for critical precursor shortages.
-
Commercialization toolkits: pilot designs with KPI templates, farmer adoption playbooks, distributor incentive schemes, and sample contract provisions for toll manufacturing and licensing.
-
Risk matrices and mitigation plans tied to public acceptance, nanoparticle toxicity concerns, and environmental monitoring obligations.
-
Strategic M&A and partner screening frameworks: target archetypes, valuation drivers, and integration checklists for technology and route-to-market plays.
Competitive landscape — who’s shaping the field and why it matters
The industry is evolving through two parallel forces: specialized innovators delivering product-level differentiation and incumbent crop-input players scaling nano-enabled portfolios into existing distribution channels. Our competitive analysis synthesizes company profiles, technology positioning, and recent corporate moves to reveal practical implications for potential partners, acquirers, and competitors.
-
Specialist innovators: Companies focused on nano-enabled nutrient delivery and crop enhancement have demonstrated the fastest path from field trial to commercial pocket sales. These firms have built differentiated formulations and farmer-facing value propositions that reduce application rates while improving nutrient uptake efficiency—making them attractive M&A targets or co-development partners for larger players seeking rapid entry.
-
Large agri-input incumbents: Major crop-protection and fertilizer companies are accelerating development of nano-formulations and targeted delivery systems to integrate with their scale advantage. Recent strategic moves show incumbents prioritizing product development and portfolio expansion in nano-enabled seed treatment and crop protection—signaling consolidation pressure in higher-value formulation segments.
-
Material suppliers and advanced-nanotech labs: Firms supplying base nanomaterials and offering molecular-scale expertise are critical enablers. Their role in ensuring reproducibility, safety, and scalable manufacturing makes them preferred strategic partners or acquisition priorities for integrated players.
Notable signals we tracked include major incumbent acceleration of nano-enabled crop protection programs and portfolio expansions by leading precision-agriculture firms, alongside recognition and growth of several private innovators. Independent verification and field-trial validation by third-party labs have also begun to shape purchasing decisions, elevating the importance of transparent safety and efficacy data in commercial negotiations.
Market structure and concentration — what it implies
Our market concentration analysis finds moderate concentration at the top: the three- and five-firm concentration ratios indicate that a handful of firms are influential but do not dominate the industry entirely. This structure rewards both scale (for distribution and regulatory reach) and nimbleness (for product innovation and targeted adoption trials). For strategy teams, this means parallel plays—invest in scale where distribution and regulatory capability matter, and use M&A or partnerships to acquire niche science and field expertise where necessary.
Key strategic imperatives for 2026
-
Prioritize a small number of high-probability use-cases with measurable farm-level economics and run tightly controlled pilots to produce defensible ROI evidence for distributors and buyers.
-
Invest in rigorous environmental and human-safety testing now—regulatory windows are opening, and early dossiers that show comprehensive risk mitigation accelerate approvals and reduce reputational exposure.
-
Secure diversified raw-material pathways, including validated processes using agricultural waste biomass, to reduce upstream price and supply volatility.
-
Build commercial partnerships that combine nano-formulation expertise with incumbent distribution networks; consider licensing rather than full vertical integration when speed to market is critical.
-
Design pricing that reflects higher upfront production costs but demonstrates lower total cost of ownership (TCO) for farmers through yield improvement, lower application frequency, and reduced environmental compliance costs.
-
Create a transparent field-data strategy: independent validation, continuous monitoring via nano-biosensors, and open communication to build farmer trust and preempt public concerns.
-
Use M&A selectively to buy scale or unique IP—targets with field-validated formulations and distribution traction command premium valuations.
Risk profile and mitigation
The principal near-term risks are regulatory uncertainty, environmental and soil-ecology impacts of persistent nanoparticles, public perception, and higher initial production costs relative to conventional inputs. Mitigations that deliver strategic advantage include early investment in third-party ecotoxicology studies, transparent LCA reporting, traceability systems, stakeholder engagement programs, and staged rollout strategies that pair product launches with measurable soil-health monitoring.
Investor implications — where value will be created and recognized
For investors, the sector presents multiple value-creation levers: owning proprietary formulations with demonstrable yield or cost advantages, controlling scale manufacturing or unique material supply chains, and forming distribution agreements with established agribusiness channels. The market’s projected trajectory through 2032, underpinned by a double-digit CAGR, makes 2026 an inflection year: investment now can capture asymmetric returns if combined with disciplined pilot validation and regulatory de-risking.
Next steps
PW Consulting’s full report includes the detailed models, risk-adjusted forecasts, proprietary vendor scoring, and legal/regulatory playbooks necessary to convert strategy into execution. We designed it as an operational guide for teams that need to act this year—whether to invest, partner, or accelerate internal programs.
To access the full dataset, scenario models, and the actionable annexes (pilot templates, regulatory checklists, and M&A target profiles), please request the Worldwide Agricultural Nanotechnology Market report through PW Consulting’s research portal. The full study contains the granular segmentation and company-level detail that underpins the high-level strategic guidance presented here.
For detailed analysis of this topic, please visit the official page: Worldwide Agricultural Nanotechnology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com