

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Centrifugal Lorry Washing Pump Market to Reach USD 626.82 Million by 2032 at a 5.14% CAGR — Automated Truck Wash Systems Lead with USD 288.0M, North America Tops at USD 141.03M

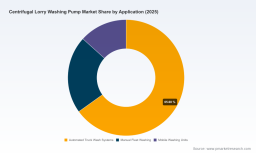
Worldwide Centrifugal Lorry Washing Pump Market: Strategic Imperatives for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide Centrifugal Lorry Washing Pump Market is released as companies and public fleets confront accelerating sustainability mandates, tightening labor markets, and a sharpened focus on total cost of ownership. This briefing synthesizes the report’s strategic value for 2026 planning cycles: why the market’s macro trajectory matters, how competitive dynamics are evolving, and which operational choices will drive durable advantage over the 2026–2032 forecast horizon.
Three Phase ANSI Meter Market
Executive snapshot (what matters for 2026)
-
Market scale and momentum: The centrifugal lorry washing pump market has expanded meaningfully in the first half of the decade and reached approximately USD 442.5 Million in the base year (2025). The study projects continued growth into 2026 and beyond, driven by fleet electrification trends, water reuse adoption, and efficiency upgrades.
Worldwide Business Projectors Market -
Forward growth profile: PW Consulting’s forecast layer shows a compound annual growth rate (CAGR) of 5.14% across the 2026–2032 horizon, with the market approaching roughly USD 627 Million by the end of the forecast period.
Worldwide Emergency Response System Towers Market -
Market structure: The market shows moderate concentration—the top three suppliers account for a meaningful share, and the top five firms control just over half of market value—pointing to both established leaders and whitespace for focused challengers.
Why 2026 is a pivotal decision point
-
Regulatory and sustainability inflection: Municipal and industrial wash facilities face tighter water reclamation and discharge standards. Proven filtration and recycling modules can reduce freshwater withdrawal dramatically—owners who move early capture both compliance and operating savings.
-
Energy and efficiency mandates: Energy-efficiency regulations and internal decarbonization goals are accelerating adoption of variable frequency drives (VFDs) and system-level pump controls. In many truck-wash applications, VFD retrofits demonstrate payback windows short enough to be compelling within a single budget year, reshaping procurement priorities.
-
Materials and procurement risk: Stainless steel alloys and durable thermoplastics are core components for corrosion and abrasion resistance. Fluctuations in raw-material availability and pricing create procurement pressure that must be managed through supplier diversification and long-lead inventory strategies.
-
Labor and automation vectors: Automation—touch-free gantry systems, integrated high-pressure modules, and remote diagnostics—reduces dependence on scarce labor and changes the buyer’s calculus from capex-only to lifecycle service models.
What PW Consulting’s report delivers to enterprise teams
-
Actionable market sizing and scenario forecasts: An interactive model that lets procurement, finance, and product teams stress-test demand under regulatory, fuel-price, and labor scenarios—so they can understand mid-year budget impacts and multi-year CapEx needs.
-
Supplier benchmarking and playbooks: A pragmatic supplier scorecard that evaluates product portfolios, aftermarket capability, service-response SLAs, and innovation traction—accompanied by negotiation playbooks to reduce initial procurement premium and lower Opex through service contracts.
-
Technology and materials roadmap: Guidance on choosing between stainless steel and engineered thermoplastic designs for different wash chemistries and salt-exposure profiles, plus migration plans for VFDs and telemetry retrofits that protect ROI.
-
CapEx/Opex templates and ROI calculators: Ready-to-use templates for total cost of ownership, incorporating water-reuse savings, energy reductions from VFDs, and labor delta associated with automation—designed to support board-level investment approval.
-
M&A and partnership screens: A shortlist of target archetypes and financial thresholds tailored to companies seeking inorganic scaling—ranging from regional service specialists to systems integrators with water-treatment competencies.
-
Regulatory scenario mapping: Local-to-international policy scenarios that quantify exposure and upside for early adopters of water recovery and energy-efficiency technologies.
Competitive landscape — read between the lines
-
Cat Pumps (Minneapolis) remains a reference point for high-pressure cleaning solutions in truck-wash applications. Their emphasis on VFD-ready options and high-pressure regimes positions them strongly in automated, high-throughput installations where energy-tied ROI is a procurement priority.
-
MP Pumps (Detroit) and Ampco Pumps (Menomonee Falls) occupy complementary positions: reliable centrifugal and self-priming architectures that address corrosion and wastewater handling in demanding environments. Expect these firms to emphasize robustness and aftermarket uptime guarantees.
-
Pacer Pumps’ thermoplastic specialization gives it differentiation where chemical resistance and lightweight installations matter—an attractive value proposition for mobile and retrofit markets where cost and serviceability are paramount.
-
Xylem (Goulds) and Grundfos deliver performance and systems integration capabilities across single- and multistage platforms, often bundled with control and booster solutions. These players will continue to compete on energy efficiency, reliability, and branded service networks.
-
Kärcher functions as a systems integrator, marrying pumps with water treatment, controls, and operator-friendly interfaces. For buyers prioritizing turnkey outcomes—compliance, reduced labour, and predictable uptime—integrators like Kärcher are natural partners.
-
Market activity indicators: Recent trade-show participation and product demonstrations—from high-pressure showcases to high-capacity centrifugal launches—signal an industry preparing for a refresh cycle of both new installations and high-value retrofits.
Practical recommendations for 2026 planning
-
Run prioritized retrofit pilots in Q1–Q2 2026: Target a small set of sites for VFD-enabled pump retrofits combined with basic water-reuse filtration to validate sub-12‑month payback cases in your operating profile.
-
Shift procurement KPIs toward lifecycle cost and service-at-risk: Renegotiate RFP templates to weight spare-part availability, remote diagnostic capabilities, and guaranteed response times more heavily than headline capital price.
-
Modularize product roadmaps: Design or procure pump platforms that allow rapid conversion between single-stage and multistage configurations and permit thermoplastic or stainless wet-end options to control unit economics across markets.
-
Invest in aftermarket analytics: Early investment in predictive maintenance and telematics will create a two-sided revenue benefit—reduced downtime for operator clients and a recurring-service revenue stream for manufacturers or integrators.
-
Hedge raw-material exposure: Adopt multi-sourcing, strategic safety stock, and indexed contracts for key alloys to dampen input-cost volatility.
-
Explore partnership plays rather than broad M&A in 2026: Joint pilots with water-treatment specialists or local service networks unlock faster route-to-market for compliance-driven installations with lower integration risk.
How to integrate the report into your 2026 decision cycle
-
Board and budget alignment: Use the report’s CapEx/Opex models to align procurement cycles with finance—translate mid-term forecast sensitivity into purchase phasing that optimizes tax and depreciation outcomes.
-
R&D and product planning: Field-test the report’s technology roadmaps against your R&D backlog; reprioritize feature development that shortens installation time and improves remote-serviceability.
-
Commercial deployment: Segment go-to-market plays into retrofit-first (short-term payback) and greenfield systems (embedded water-treatment and automation) and assign dedicated commercial leads to each funnel.
-
M&A diligence: Apply the supplier scorecard and market-concentration analytics to screen targets—focusing on service coverage, spare-parts economics, and complementary product synergies—before committing to deep diligence.
PW Consulting’s full report provides the detailed regional and application breakdowns, supplier scorecards, and downloadable financial models that underpin these recommendations. The summary above is intentionally focused on strategic implications to support rapid assimilation by executive teams; the granular subsegment data and vendor-level financials are available in the complete study for teams ready to execute procurement, product, and M&A initiatives in 2026.
For leadership teams building resilient, compliant, and cost-optimized lorry-washing portfolios, 2026 is a window for decisive moves: prioritize pilots that deliver measurable ROI, lock in supplier-service partnerships that protect uptime, and structure procurement to capture the water- and energy-efficiency upside. PW Consulting stands ready to support implementation, from pilot design to supplier negotiation and M&A screening.
For detailed analysis of this topic, please visit the official page: Worldwide Centrifugal Lorry Washing Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com