

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Soft Shackle Market to Reach USD 545.43 Million by 2032 as UHMWPE Drives Demand

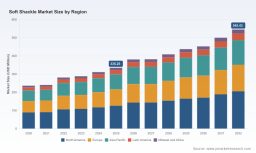
Worldwide Soft Shackle Market: Strategic Imperatives for 2026 — A PW Consulting Preview
The soft shackle market is entering a maturation phase that will reframe supplier strategies, procurement practices, and product engineering roadmaps in 2026. Our new market study — the Worldwide Soft Shackle Market — synthesizes five years of historic performance (2020–2025) and delivers a scenario-driven forecast through 2032. In brief: the market reached roughly USD 335.3 million in 2025 and is projected to accelerate to the mid‑hundreds by the end of our forecast horizon, underpinned by a compound annual growth rate (CAGR) of 7.21% for the forecast period. This release note outlines the report’s strategic value, the practical outputs executives can act on immediately, and a curated competitive read of leading providers shaping 2026 decisions.
Worldwide Plating Bath Analysis Services Market
Market Snapshot: Macro momentum and what it signals for 2026
-
Macro performance: After steady expansion during the historical window (2020–2025), the market is expected to continue growing at a healthy pace (CAGR ~7.2%). Our base-year analysis (2025) and first‑year forecast (2026) indicate notable step‑change demand driven by safety regulation adoption, wider acceptance across marine and industrial lifting, and cross‑sector substitution away from steel hardware.
Worldwide Golf Clothing Market -
Future sizing: By modeling multiple uptake scenarios we find the market moving from a niche commodity to a mainstream engineered component in several end‑use categories by the end of the decade. The 2032 outcome in our central scenario projects a materially larger installed base, reflecting both unit growth and premiumization of feature sets (coatings, traceability, certified lifting grades).
Medical Wound Care Antimicrobial Dressings Market -
Concentration and competitive structure: The market remains fragmented. The leading suppliers collectively hold a relatively modest share, leaving significant whitespace for challenger brands, contract manufacturers, and upstream fiber suppliers to scale quickly if they execute on quality, certification, and channel strategies.
How this report supports 2026 decision-making — pragmatic deliverables
PW Consulting designed this report as a decision‑support toolkit. We do not stop at macro numbers; the deliverables are built for immediate operational and strategic use by procurement, product, and corporate development teams:
-
Interactive financial model: revenue and margin scenarios calibrated to raw‑material cost paths, regional demand sensitivity, and product mix premiuming.
-
Supplier scorecards: qualitative and quantitative assessments across manufacturing quality, capacity, traceability, certification readiness, and go‑to‑market orientation.
-
Procurement playbook: sample RFx templates, testing requirements, acceptance criteria, and contract language for warranties, traceability, and safety certification.
-
Product roadmaps and engineering checklists: specification differentials (abrasion covers, coatings, serialized traceability) and testing protocols to convert field reliability into commercial premium.
-
Risk maps and mitigation plans: fiber supply concentration, price volatility scenarios, and recommended hedging/forward procurement tactics.
-
M&A and partnership scorecard: prioritized target archetypes and diligence checklists for bolt‑on acquisitions or JV structures to gain scale fast.
Competitive landscape — profile analysis and strategic implications
Our vendor analysis focuses on firms that define modern soft‑shackle performance and procurement expectations. We profile them through product architecture, manufacturing governance, certification posture, and target end‑markets. Below are synthesized strategic takeaways for each highlighted player.
-
ASR Offroad (USA) — Positioned as a premium, traceable manufacturer with an emphasis on abrasion protection and braided guards. Their ISO 9001:2015 certified US facility and use of domestically sourced fibers provide a clear value proposition for customers prioritizing provenance and quality assurance. Strategic implication: ASR is a natural partner for OEMs and public‑sector buyers who require manufacturing controls and localized supply.
-
Factor 55 (USA) — Differentiates via engineered coatings and consistent minimum breaking strengths validated by lab/field tests. Their product set targets closed‑system winch applications and truck fleets seeking certified performance. Strategic implication: Factor 55’s approach supports premium pricing and loyalty among professional users; competitors should consider comparable test evidence and quality guarantees to compete.
-
Bubba Rope (USA) — Emphasizes strength-to-weight and corrosion resistance, with broad adoption across off‑road, agriculture, and marine towing. Strategic implication: Their brand strength in consumer and light‑commercial channels underscores the importance of distribution and brand messaging for growth.
-
Safe‑Xtract (USA) — Military‑approved lines, Berry Amendment and Buy American Act compliance, serialized traceability and factory load‑testing define a defense‑grade offering. Strategic implication: Firms pursuing defense and public‑procurement opportunities must match traceability, serialization and compliance processes to compete effectively.
-
Cortland Company (USA) — Focused on engineered alternatives (e.g., AeroLock connectors) with rigorous fatigue and lifting performance testing. Strategic implication: Cortland’s testing‑led innovation highlights an avenue for suppliers to capture industrial lifting and rigging spend by investing in certified performance data.
-
Erickson Manufacturing (USA) — Targets towing and load securement with lightweight UHMWPE solutions. Strategic implication: The product mix is attractive to buyers seeking substitution of steel for weight and corrosion advantages in transport fleets.
-
Robship (Marine) — Integrates rope manufacturing and machine stretching to deliver compact, strong marine shackles. Strategic implication: Vertical integration remains a winning tactic in marine markets where product consistency and local service matter.
-
Wichard (France) — A specialist in sailing and marine soft links, with strong brand recognition among sailors and marine professionals. Strategic implication: Niche brand heritage combined with performance can sustain price premiums in specialty channels.
-
Fulcrum Lifting — Plays to lifting and rigging buyers by offering certified alternatives to metal shackles. Strategic implication: Certification and a documented safety case enable access to higher‑value industrial contracts.
-
Dynamica Ropes — European HMPE specialist with product breadth in diameters and protective covers. Strategic implication: Flexible product configurations and optional abrasion covers give suppliers entry points into engineering‑led spec decisions in Europe.
Supply‑chain and raw‑material dynamics: risk and opportunity
Ultra high molecular weight polyethylene (UHMWPE) fibers — marketed under trade names such as Dyneema or Plasma — remain the dominant feedstock, delivering steel‑competitive strength with lighter weight, corrosion resistance, and flotation. Our analysis highlights several implications for 2026:
-
Supplier leverage: Fiber producers with excess capacity or long‑term contracts will command negotiating leverage; buyers should consider multi‑sourcing and forward purchases to stabilize input costs.
-
Quality variance: Not all UHMWPE processes are equivalent — heat‑treatment, coating and final forming affect fatigue life. Buyers must codify testing regimes into procurement specifications.
-
Regulatory tailwinds: Military compliance frameworks and domestic content rules create pull‑through demand for domestically‑certified production lines, an opportunity for suppliers that invest in compliant manufacturing footprints.
Safety, certification and product liability — practical mandates for buyers
Adoption in lifting and industrial environments requires certainty on safety and endurance. Two practical factors matter for 2026 procurement:
-
Tested safety factors: Vendors can deliver shackles tagged with a 5:1 safety factor for overhead lifting on request; however, documented lab and field testing, fatigue data and inspection protocols must accompany product delivery to satisfy industrial customers.
-
Traceability and compliance: Serialized products with end‑to‑end traceability (as evidenced by military suppliers) reduce warranty disputes and support liability management. ISO 9001:2015 manufacturing governance is a clear differentiator for buyers requiring consistent quality.
Recommended strategic plays for 2026 — where to focus resources now
-
For OEMs and Tier‑1 buyers: Lock in multi‑year supply agreements with certification clauses and performance SLAs. Insist on lab data and on‑field fatigue evidence as a precondition for qualification.
-
For suppliers and contract manufacturers: Prioritize ISO certification, serialized traceability, and military compliance capabilities. Invest in abrasion‑resistant covers and coating technologies that support premiumization.
-
For distributors and channel partners: Build training programs and inspection services as a value proposition — buyers will pay for lifecycle assurance beyond the physical product.
-
For private equity and strategic buyers: Target bolt‑on assets that add domestic manufacturing capacity, testing laboratories, or traceability capabilities to accelerate entry into defense and industrial lifting segments.
What we intentionally hold back — and why you should request the full study
In this preview we present the strategic logic, competitive context, and operational playbook elements that matter for 2026. To preserve the actionable edge for subscribing organizations, the full report contains granular data we do not publish here — including detailed regional and application splits, supplier‑level market shares, price curve elasticities, and downloadable model files that you can use to run custom scenarios. These datasets are embedded alongside reproducible methodology notes, primary interview transcripts, and testing protocol appendices.
Next steps — how to use this insight in your 2026 planning
-
Incorporate the report’s interactive model into your budget cycle to stress‑test procurement strategies under raw material volatility scenarios.
-
Use supplier scorecards to prioritize qualification pathways and to structure RFPs around certified performance and traceability.
-
For strategic planning, map M&A targets from our shortlist to accelerate footprint expansion into defense, industrial lifting, or marine sectors where certification premiums justify acquisition multiples.
PW Consulting’s Worldwide Soft Shackle Market report is designed to be the operative intelligence set for teams making resource allocation, procurement, and product development decisions in 2026. For access to the complete datasets, supplier rankings, and downloadable financial model that power the foregoing recommendations, please visit the PW Consulting research portal and request the full report package.
For detailed analysis of this topic, please visit the official page: Worldwide Soft Shackle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com