

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Surgical Tray Market Poised to Expand at a 5.81% CAGR Through 2032

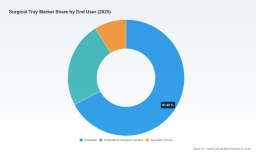
Worldwide Surgical Tray Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
PW Consulting’s latest market intelligence on the Worldwide Surgical Tray Market delivers an operationally focused playbook for executives planning resource allocation, product strategy, and M&A activity in 2026. Built on a 2025 base year and a 2026–2032 forecast horizon, the study models a market growing at a compound annual growth rate (CAGR) of 5.81% and tracks the market’s steady recovery and structural re‑balancing since 2020. The global market size reached USD 540.2 million in 2025 and we model a near‑term increase to an estimated USD 588.0 million in 2026, with multiple scenarios that extend to 2032 under alternative clinical, regulatory and raw‑material assumptions.
Worldwide Beta Testing Software Market
Why 2026 Is a Pivotal Year for Buyers and Suppliers
-
Regulatory inflection: Compliance requirements (e.g., ISO 17665‑1 for moist heat sterilization and the US FDA’s Class II 510(k) pathways) are tightening validation expectations for both reusable and single‑use systems. This raises upfront engineering and documentation costs for product introductions and line extensions.
Worldwide Car Ramp Market -
Procurement and reimbursement pressure: Public payors and private systems continue to optimize DRG and bundled payment approaches, changing how procedure kits and trays are purchased and reimbursed — creating incentives for cost transparency and service‑based contracts.
Worldwide Social Media Integration Market -
Operational hygiene standards: Clinical guidance documents (notably AAMI ST79) are increasing scrutiny on cleaning and sterilization validation, which materially affects life‑cycle costs and the comparative economics of reusable vs. disposable trays.
-
Supply‑side volatility: Raw material and manufacturing cost drivers (for example, medical‑grade 316L stainless steel price dynamics) and sterilization container innovations are shifting supplier economics and competitive advantage.
What the Report Contains — Practical, Decision‑Ready Content
-
Macro model and proprietary forecasts: Baseline and three scenario tracks (conservative, base, upside) for 2026–2032 with sensitivity to procedure volumes, sterilization capital spend, and raw material cost shocks.
-
Supplier scorecards: Comparative capability matrices for product range, sterilization compatibility, custom tray programs, manufacturing footprint and contract performance.
-
Procurement playbook: Tactics for contract design, total cost of ownership (TCO) modelling, negotiation levers, and transition planning for systemwide rollouts.
-
Regulatory & validation checklist: Step‑by‑step roadmap for 510(k) preparation, sterilization validation (ISO 17665‑1), and AAMI ST79 cleaning protocol adoption relevant to reusable tray programs.
-
Operations & CAPEX guidance: Toolkits for central sterile supply department (CSSD) investments, throughput modelling and disposal/waste management for single‑use options.
-
M&A screening framework: Criteria‑driven target profiles, valuation multipliers based on profitability levers, and post‑merger integration risk maps.
-
Primary research and case studies: Interviews with hospital procurement leads, CSSD managers and OEM executives plus anonymized case studies that demonstrate measurable savings and risk mitigation strategies.
Data‑Driven Insights — Select Highlights (Teaser)
-
Steady growth, but uneven economics: After a consistent rise from 2020 through 2025, the market’s base projection for 2026 shows continued positive momentum driven by rising procedure volumes, expanded ambulatory surgery capacity, and renewed capital investments in sterilization infrastructure.
-
Moderate market concentration creates tactical windows: The market exhibits moderate concentration among the largest suppliers (three‑ and five‑firm concentration metrics indicate meaningful but incomplete consolidation). For buyers and mid‑market suppliers this means there are short‑term opportunities to secure differentiated contracts or to accelerate bolt‑on M&A to close capability gaps.
-
Material and process choices matter more than ever: The life‑cycle cost calculus between reusable stainless solutions and disposable polymer trays is being re‑written by sterilization validation costs, labor and throughput constraints, and waste‑handling rules. Our TCO scenarios show how relatively small changes in sterilization cycle efficiency or labor hours per tray can swing procurement decisions.
-
Sterilization innovation lowers barriers: Recent product introductions in rigid container systems and optimized perforated tray designs materially reduce turnaround time in CSSDs — a lever that hospitals and ASC operators are using to justify CAPEX for reusable programs.
Competitive Landscape — Who’s Shaping the Market and How
-
Large OEMs with integrated sterile‑procedure offerings retain strong purchase momentum through national contracts and custom tray programs. Their strengths are scale, integrated logistics, and the ability to bundle products with consumables and services.
-
Specialist players focused on sterilization containers, perforated instrument trays, and procedure‑specific kits continue to capture premium margin where clinical fit and validation support yield measurable throughput or safety improvements.
-
Recent corporate developments illustrate tactical plays: tier‑one incumbents are expanding both product breadth (catalog updates and new modular offerings) and service depth (multi‑year supply agreements and next‑generation container systems). These moves compress time‑to‑value for hospital partners but also raise the bar for new entrants.
-
For 2026, the key competitive questions are: Can suppliers accelerate sterilization validation support to shorten procurement cycles? Can they offer bundled service agreements that align incentives under bundled payment models? And can mid‑market players create defensible niches through product specialization or CSSD service partnerships?
Actionable Strategies for 2026
-
For hospital systems and ASCs: Prioritize a SKU rationalization pilot linked to a validated sterilization throughput improvement. Use the results to renegotiate master supply agreements with performance‑based clauses.
-
For OEMs and manufacturers: Invest in sterilization compatibility testing and third‑party validation documentation now — it shortens customer acceptance cycles and reduces procurement friction in 2026.
-
For investors and corporate development teams: Target acquisitions that add sterilization engineering, CSSD service capabilities, or modular tray designs that can be cross‑sold into existing distribution networks.
-
For private payors and policy teams: Recognize that aligning reimbursement policy with sterilization and waste management outcomes can unlock significant total system savings; consider pilot programs that reward lifecycle efficiency rather than unit price.
Operational Playbook — Priorities and 90‑Day Moves
-
Immediate (0–90 days): Conduct a TCO audit of tray spend; map sterilization bottlenecks; prioritize three high‑volume tray families for pilot redesign or SKU consolidation.
-
Near term (3–9 months): Implement validation pilots under ISO 17665‑1 and AAMI ST79 guidance; negotiate short‑term performance guarantees with suppliers tied to CSSD throughput and defect rates.
-
Medium term (9–18 months): Roll out service‑based contracting for selected departments; evaluate CAPEX for container investment versus outsourced sterilization; embed environmental and waste fees into procurement evaluations.
M&A and Investment Signal Map
-
Look for targets that strengthen sterilization engineering, proprietary perforation or container IP, or that provide immediate scale in strategically important clinical segments. Given the current market concentration profile, carefully priced bolt‑ons can deliver fast accretion.
-
Valuation discipline is critical: prioritize deals with clearly identified synergies in procurement, distribution, or CSSD service delivery and allocate a portion of purchase price to measurable post‑close integration milestones.
Why This Report Is Strategic for 2026 Decision‑Making
-
Actionable intelligence: The report translates macro projections into per‑decision playbooks — from SKU rationalization and sterilization validation to contracting and M&A prioritization.
-
Proprietary scoring and scenarios: Our supplier scorecards and scenario models allow procurement teams and investors to stress‑test vendor strategies under realistic regulatory and raw‑material shocks.
-
Operational orientation: Unlike high‑level summaries, the deliverable includes checklists, regulatory templates, TCO models and pilot designs that procurement, clinical engineering and supply chain teams can use directly.
PW Consulting’s Worldwide Surgical Tray Market report provides the strategic context and practical tools that leaders need to make defensible decisions in 2026. For organizations that require the granular market splits, supplier rankings and downloadable modelling workbooks referenced in this preview, access to the full report and supporting datasets is available on our publications portal.
To request a report summary, schedule a briefing with our senior industry analysts, or commission a tailored TCO or M&A diligence project aligned to your 2026 planning cycle, contact PW Consulting’s Healthcare Practice.
For detailed analysis of this topic, please visit the official page: Worldwide Surgical Tray Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com